
IDEX (IEX) Lifted Guidance And Extended Its Dividend, Is It Still 12% Undervalued?
IDEX (IEX) is back in focus after its board approved a regular quarterly cash dividend of $0.73 per share, extending the company’s record to 128 consecutive quarterly payments.
That dividend decision comes after a strong run for IDEX, with the share price up 26.04% year to date and a 1-year total shareholder return of 43.69%. However, the recent 30-day share price return of 3.71% suggests some momentum has cooled following upbeat Q2 results, higher full-year guidance, and improving sentiment around demand in data centers, semiconductors, and space and defense end markets.
Scan beyond IDEX and compare this dividend story with 29 high quality undervalued stocks, which pairs shareholder payouts with solid cash flows and balance sheets.
After that kind of run in IDEX, with guidance higher and a long dividend track record in place, the real issue now is whether the current valuation still offers an appealing entry point.
Most Popular Narrative: 11.8% Undervalued
On Simply Wall St’s most followed narrative, IDEX screens as undervalued, with a fair value of $255.93 against the last close of $225.69. This puts the spotlight squarely on how much of the HST and backlog story is already embedded in the price.
Record company backlog of more than US$1b with 28% organic order growth in Q2 2026 and multi quarter visibility in HST and parts of FMT, including future dated data center bookings that extend into 2027, provides a pipeline that can support revenue and cash flow growth beyond what is already recognised.
See why 7 investors see IDEX as 12% undervalued.
Result: Fair Value of $255.93 (UNDERVALUED)
Still, the IDEX story can break if policy shocks or weaker returns in legacy units persist, especially alongside recent insider selling that may temper confidence.
Find out about the key risks to this IDEX narrative.
Another View: What IDEX’s P/E Is Telling You
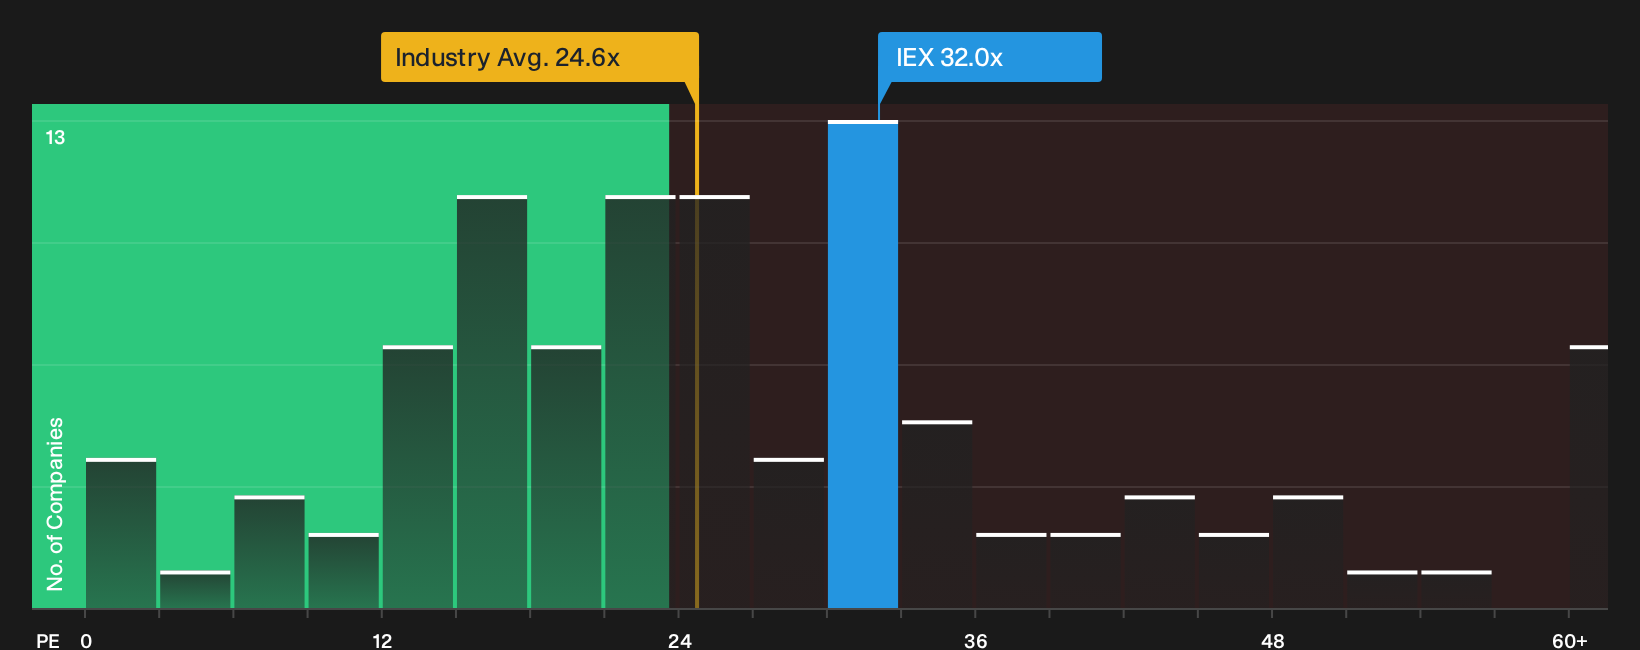
On the narrative and DCF work, IDEX screens as undervalued. On simple P/E though, the picture looks less forgiving. The shares trade on roughly 32x earnings, compared with about 24.3x for the US Machinery industry, a 31.4x peer average, and a fair ratio estimate of 23.7x. That gap suggests investors are already paying up for quality and future execution. The key question is how comfortable you are owning a stock where much of the story may already be in the multiple.
For a closer look at how this pricing stacks up against the underlying cash flows, take a look at the SWS DCF work on IDEX, then compare it with the earnings multiple story using See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Feeling encouraged by the tone around IDEX and its valuation debate today. Act quickly, pressure test the upside and risks, and then weigh the 3 key rewards.
Looking for more investment ideas beyond IDEX?
Do not stop your research with IDEX alone. Broaden your watchlist, compare quality, and pressure test your thesis against other opportunities that might fit your style even better.
- Target resilient opportunities with steadier profiles by checking companies in the 30 resilient stocks with low risk scores.
- Hunt for strong businesses that the market may be pricing too cautiously by scanning the 16 high quality undiscovered gems.
- Prioritize balance sheet strength and fundamentals when markets get choppy by reviewing the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com