
Convertible Note Offering Could Be A Big Deal For Axon Enterprise (AXON)
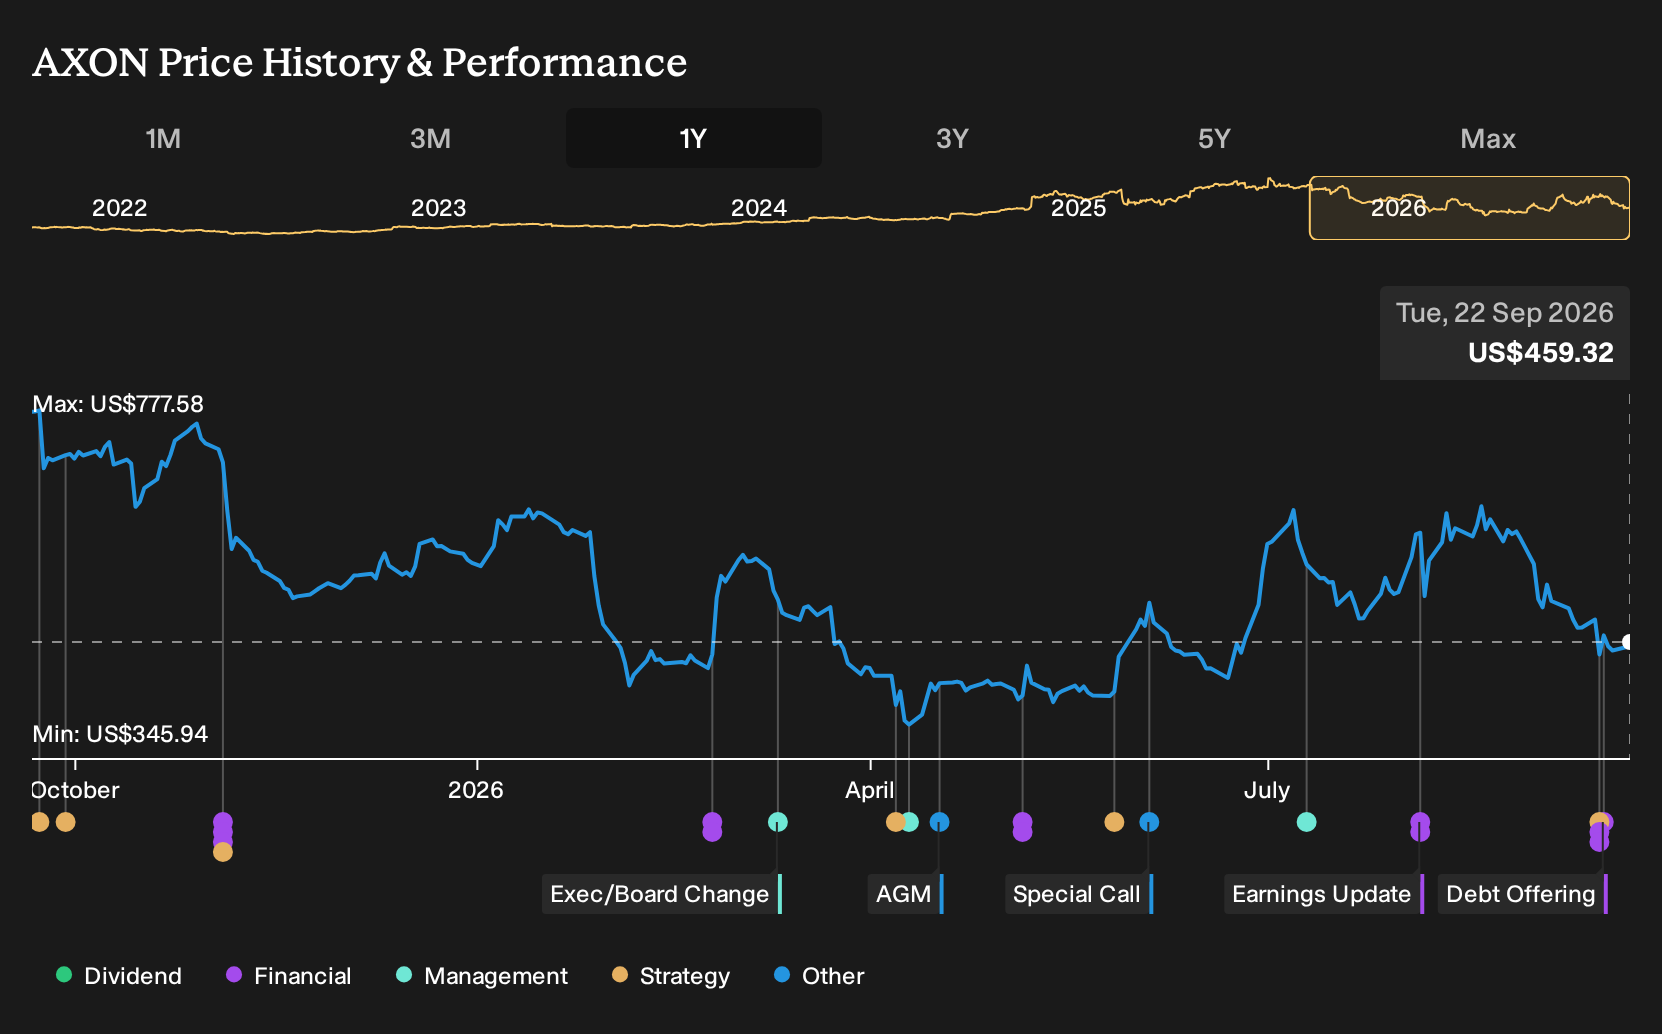
- Axon Enterprise completed a US$1b zero coupon convertible note issue due 2031, paired with an expanded revolving credit facility tied to detailed leverage and interest coverage covenants.
- The zero coupon, potentially dilutive structure and planned use of proceeds for capped call transactions, general purposes, and acquisitions highlight a significant shift in how Axon Enterprise is funding growth and product expansion.
- Next, the focus turns to how Axon Enterprise's large 0% convertible raise may reshape the existing bullish, recurring revenue driven investment narrative.
Compare how Axon Enterprise is funding expansion with other potential opportunities by scanning our curated list of list of solid balance sheet and fundamentals (23 results).
Axon Enterprise Investment Narrative Recap
To own Axon Enterprise, you need to believe its public safety ecosystem keeps drawing agencies into larger, recurring software and device bundles, even as profit margins and one off items make earnings choppy. The core near term catalyst is continued adoption of AI Era plans, Axon Assistant, TASER 10 and counter drone offerings across more jurisdictions.
The biggest near term risk sits in execution and capital allocation. Newer hardware and higher memory costs are already weighing on connected devices profitability. The 0% convertible raise adds dilution and leverage questions, so investors are watching how efficiently Axon Enterprise converts this extra balance sheet flexibility into durable, contract based cash generation.
The clearest related announcement is the US$1b zero coupon convertible note issue due 2031, paired with an expanded revolving credit facility. Both moves lift available funding for Axon Enterprise at a time when international bookings, AI bundles and counter drone programs are key operational swing factors.
This financing structure matters because it intersects directly with those catalysts and risks. Capped call transactions may help offset some dilution if the share price recovers, while the higher credit line comes with leverage and interest coverage covenants. Your focus as a shareholder is whether these constraints still leave enough room for disciplined product rollout, acquisitions and long term recurring contract growth.
Axon Enterprise Forecasts Behind The New Capital Raise
Analyst models around Axon Enterprise help explain why management is comfortable layering a 0% convertible on top of the balance sheet. The consensus view has revenue growing at about 28.8% per year over the next three years, with profit margins edging from 6.2% today to 6.5% by 2029. Earnings are projected to move from US$199.3 million today to US$445.3 million by 2029, meaning profit would need to rise by roughly US$246 million over that period. On those estimates, Axon Enterprise is modeled to generate about US$6.9b of revenue and US$445.3 million of earnings in 2029. This underpins the analyst price target framework, which is tied to a 176.6x P/E multiple on those projected results.
Axon Enterprise's narrative projects about US$6.9b in revenue and US$445.3 million in earnings by 2029. This setup assumes 28.8% yearly revenue growth and an earnings increase of roughly US$246 million from US$199.3 million today.
Uncover why Axon Enterprise's fair value indicates a 53% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses less on Axon Enterprise’s new product pipeline and more on the risk that AI cameras and cloud tools become commodities. The most cautious analysts were already working off roughly US$6.6b of 2029 revenue and US$540.2 million of earnings. Both narratives predate this 0% convertible, so opinions may shift as new information filters through estimates.
Explore 5 other Axon Enterprise fair value estimates, including one that suggests it could be worth just $440.98.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own research and judgment.
- A great starting point for your Axon Enterprise research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Axon Enterprise. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Axon Enterprise's overall financial health at a glance.
Looking For More Investment Ideas Beyond Axon Enterprise?
If Axon Enterprise is already on your radar and you want a broader watchlist, the Simply Wall St Screener can help you quickly filter the market by balance sheet strength, valuation, income potential and more.
- For investors who care most about financial resilience and low debt, start with our curated list of solid balance sheet and fundamentals (23 results) to see which businesses meet a higher bar for balance sheet quality.
- If upside potential is your priority and you prefer stocks priced below their estimated worth, filter for value opportunities using the 29 high quality undervalued stocks and compare them with Axon Enterprise on your own terms.
- Those building a portfolio around steady cash payouts can focus on income ideas through the 7 dividend fortresses and line them up against Axon Enterprise's total return profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com