
LyondellBasell Industries (LYB) Could Be 6% Overvalued As Conference Spotlight Returns
LyondellBasell Industries (NYSE:LYB) is back in the spotlight as management prepares to speak at Morgan Stanley's 14th Annual Laguna Conference, scheduled for September 15, 2026, in Laguna Beach, California.
The upcoming conference spot comes after a choppy few weeks for LyondellBasell Industries, with the 7-day share price return down 9.46% and the 30-day share price return down 12.28%. This is occurring even though the year-to-date share price return is up 33.45% and the 1-year total shareholder return is 25.02%, while the 3-year and 5-year total shareholder returns remain negative. This points to longer term holders still assessing how durable the recent momentum really is.
Scan how LyondellBasell Industries compares with other materials players under pressure by checking our hand picked list of list of solid balance sheet and fundamentals (23 results)
LyondellBasell Industries looks like a sizeable global chemicals platform with recent share price strength, but the stock has pulled back hard in the past month. Is that a reset that leaves the valuation sensible, or still stretched?
Most Popular Narrative: 6% Overvalued
LyondellBasell Industries closed at $59.24 against a widely followed fair value estimate of $56.00, which frames the current pullback as a move back toward what more cautious analysts consider a stretched valuation.
The accelerating global push for sustainability and the circular economy is likely to impose stricter regulations on single-use plastics and fossil-fuel-based chemicals. This could result in shrinking long-term demand for LyondellBasell's core polyolefin and petrochemical products and put consistent downward pressure on revenue growth.
The rapid pace of adoption for alternative materials such as bioplastics, degradable options, and recycled polymers threatens to displace demand for LyondellBasell's traditional product lines. This has the potential for lasting market share losses and reduced pricing power, which would negatively impact top-line revenue and operating margins.
See why 8 investors see LyondellBasell Industries as 6% overvalued.
Result: Fair Value of $56.00 (OVERVALUED)
Still, if LyondellBasell Industries executes on recycling technologies like MoReTec and tightens its cost base, that could blunt margin pressure faster than bearish models assume.
Find out about the key risks to this LyondellBasell Industries narrative.
Another View On LyondellBasell Industries Valuation
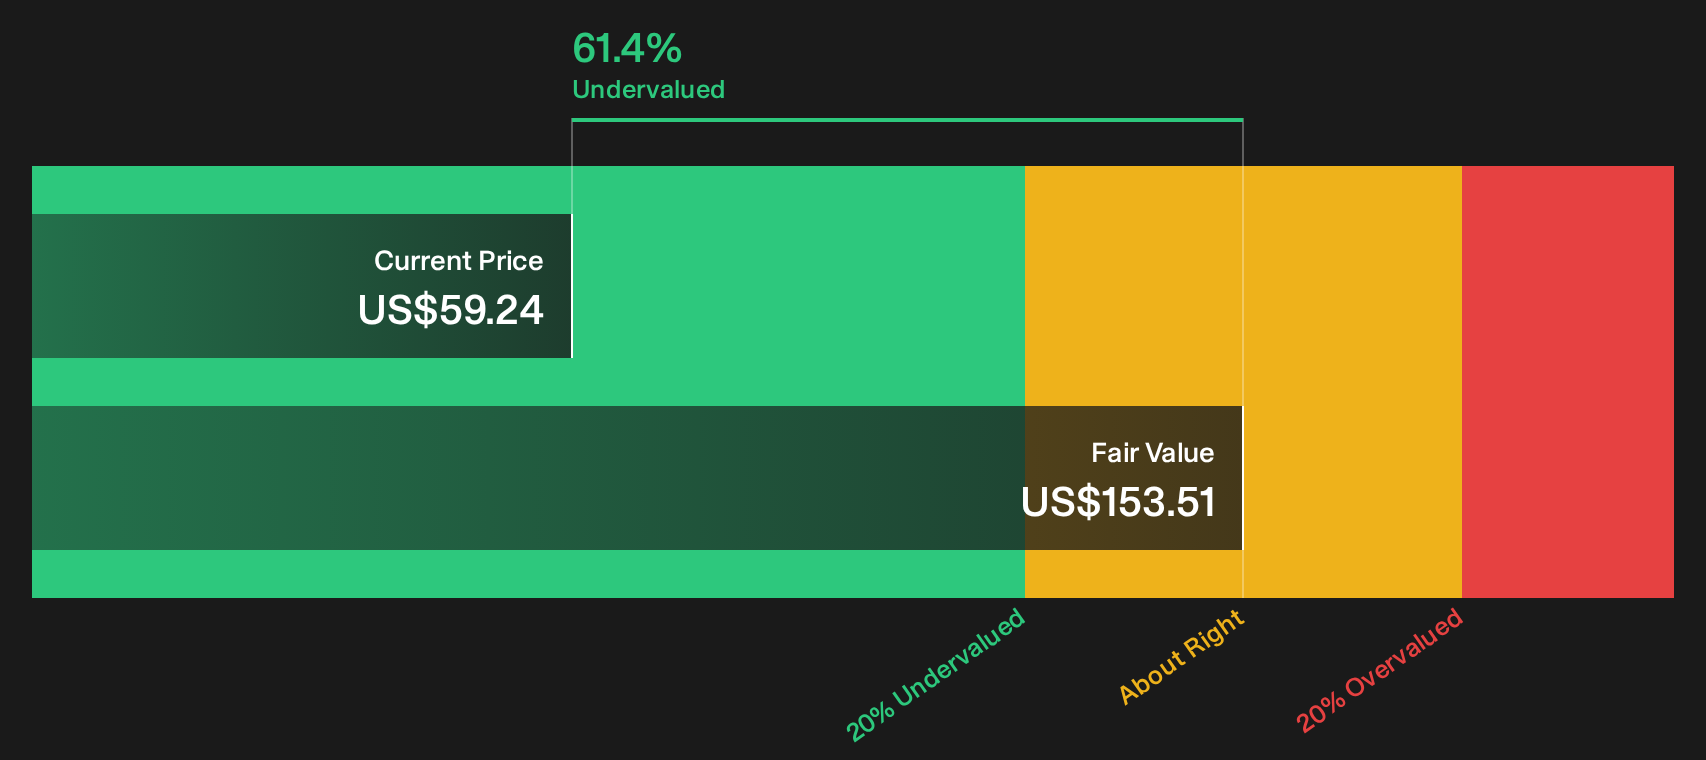
The bearish narrative pegs LyondellBasell Industries at a fair value of $56.00 and calls the stock overvalued. A different lens tells a very different story. Our DCF model on future cash flows suggests LyondellBasell Industries might be trading well below that implied value, with the current $59.24 price compared to a future cash flow value estimate of $153.51.
When one framework flags overearning risk and stretched pricing, while the SWS DCF model points to a large discount, it sets up a simple question for you: Are analyst earnings paths too cautious, or is the cash flow model leaning on assumptions you do not accept?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals often create a strong testing ground for your own thinking. Act while the facts are fresh and weigh both sides by reviewing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond LyondellBasell Industries?
Do not stop your research with LyondellBasell Industries. Broaden your watchlist with focused stock ideas built from clear financial rules so you are not chasing headlines.
- Start with income potential by scanning companies that show up as 7 dividend fortresses and see which payouts may better match your cash flow goals.
- Sharpen your margin of safety by reviewing the 16 high quality undiscovered gems that combine quality fundamentals with underfollowed stories and cleaner entry points.
- Protect your downside first and look through 30 resilient stocks with low risk scores that score well on resilience so you are not relying on luck when markets turn.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com