
Does Jets Partnership Change The Bull Case For Paylocity (PCTY)?
- In September 2026, Paylocity Holding entered into a new US$1.75b senior secured revolving credit facility maturing in 2031, and earlier in the month the New York Jets named Paylocity Corporation their official HCM platform to manage HR, payroll and spend management on a single system.
- The enlarged revolving credit agreement and marquee Jets partnership together signal management’s focus on long term funding flexibility and higher profile enterprise demand for Paylocity’s multi module HR and finance platform.
- We will now assess how Paylocity Holding’s investment narrative is affected by this larger revolving credit facility and high profile Jets partnership.
Compare how Paylocity Holding stacks up on funding flexibility and customer momentum against a curated group of peers by scanning the list of solid balance sheet and fundamentals (23 results), which is aligned with similar balance sheet strength and fundamentals.
Paylocity Holding Investment Narrative Recap
To own Paylocity Holding, you need to believe the platform can keep turning AI driven products and broader HR, finance and IT coverage into steady earnings, even as revenue growth guidance points to a slower pace. The enlarged US$1.75b revolving credit facility mainly affects funding flexibility rather than the core product and sales engine in the near term.
The short term swing factor still sits in how mid market clients adopt premium AI SKUs and adjacent modules without hurting retention. The main risk remains that already moderated growth and a relatively full P/E leave little room for disappointment if sales or margins soften further.
The New York Jets HCM partnership is the clearest operational tie in to this funding move. It puts Paylocity Holding in front of a high visibility client that is using the platform for HR, payroll and spend management. This showcases the multi module approach that underpins the ARPU and margin story.
For catalysts, investors can watch how effectively management converts that type of reference customer into broader enterprise demand and deeper usage of finance and IT tools. If large organizations lean into more modules, it supports the cross sell thesis, while slow adoption would keep the growth versus valuation tension front and center.
Paylocity Holding's current analyst narrative connects a forecast for revenues of about US$2.2b and earnings of roughly US$428.1 million by 2029 with an assumed 7.3% yearly revenue growth rate and an earnings increase of about US$158.4 million from US$269.7 million today.
Uncover how Paylocity Holding's fair value indicates an 18% potential upside to its current price before the market closes that gap.
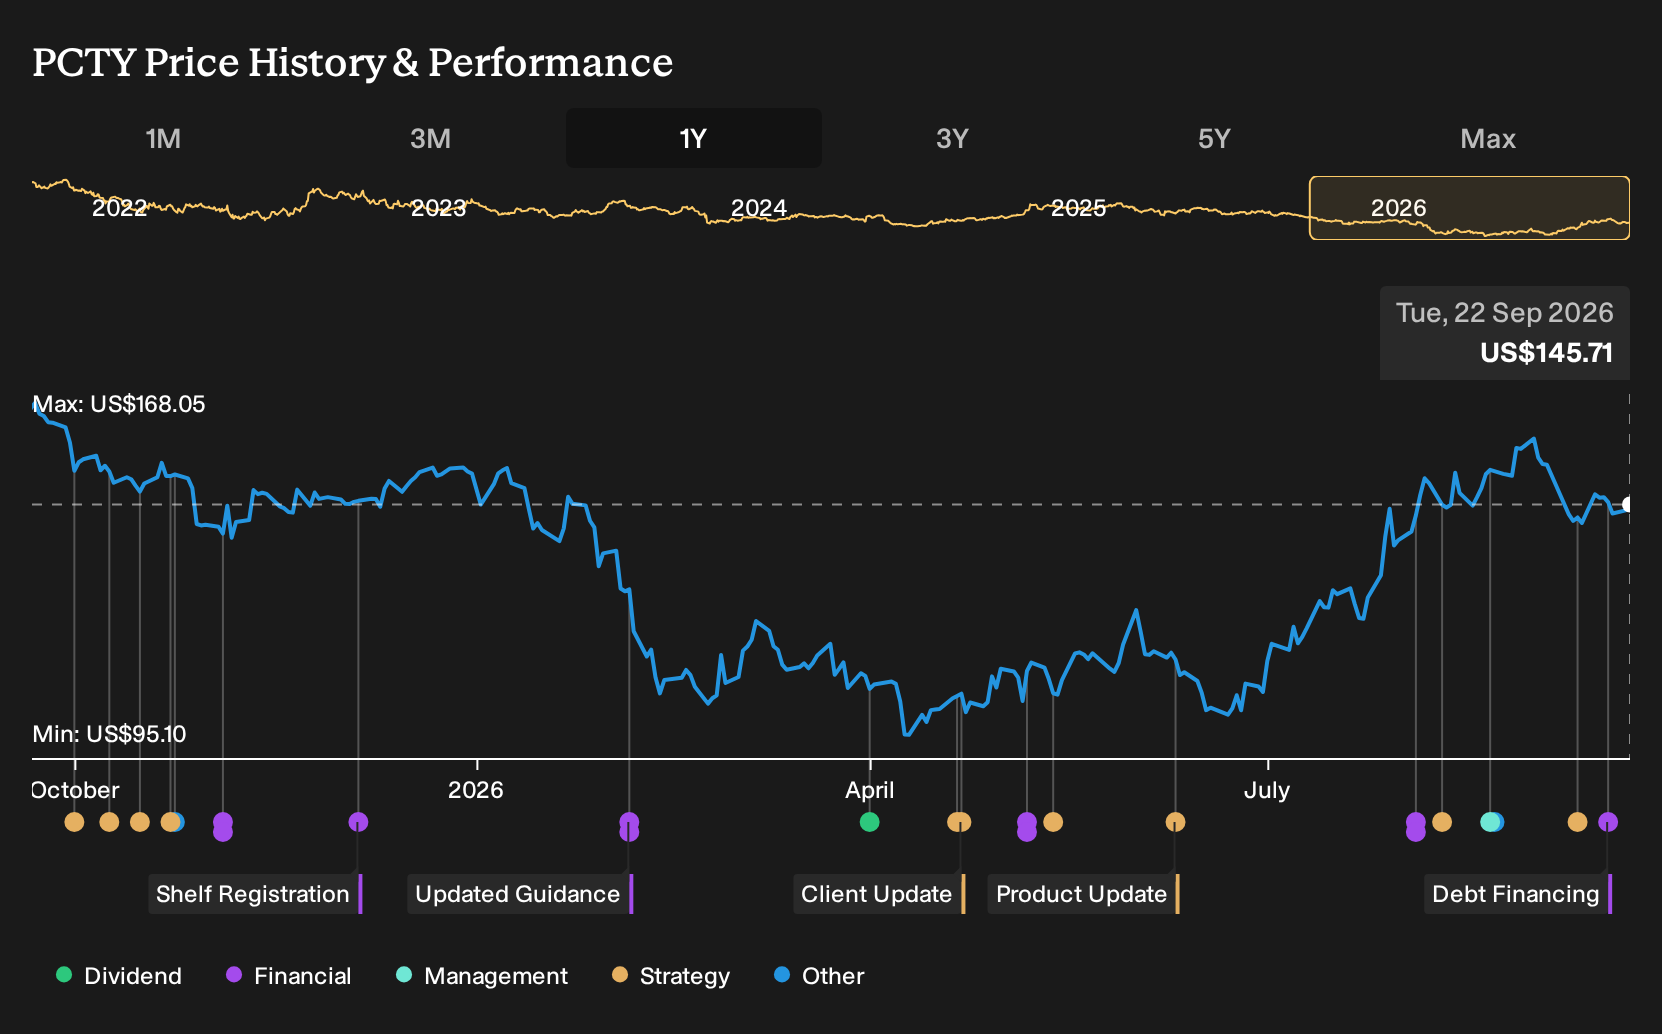
Exploring Other Perspectives
For Paylocity Holding, the alternate narrative leans on a catalyst that current models may not fully capture. The most optimistic analysts were already penciling in about US$2.4b of revenue and US$449.6 million of earnings by 2029, assuming rapid AI driven adoption. Those views came before this expanded credit facility and Jets deal, so opinions may change as new information lands.
Explore 2 other Paylocity Holding fair value estimates, including one that suggests as much as 92% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Paylocity Holding research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Paylocity Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Paylocity Holding's overall financial health at a glance.
Looking for more investment ideas beyond Paylocity Holding?
Once you have formed a view on Paylocity Holding, it can help to cross check that thesis against other companies with different balance sheet profiles, cash generation and income characteristics. The Simply Wall St Screener lets you compare these themes quickly so you can decide where to spend your research time.
- For investors who want income first and growth second, review a curated set of higher yielding opportunities through the 7 dividend fortresses.
- If capital preservation and steadier risk profiles matter more to you than rapid expansion, filter for companies using the 30 resilient stocks with low risk scores.
- To hunt for potential up and comers with solid fundamentals that are not widely followed yet, scan the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com