
How Investors Are Reacting To VEON (VEON) Kazakhstan Payments Deal
- VEON Digital Financial Group and Beeline Kazakhstan signed a five year cooperation memorandum with the National Bank of Kazakhstan to explore integrating VEON’s digital services with national payment infrastructure, while JazzCash was shortlisted for two Money Awards 2026 categories for welfare disbursement and health insurance in Pakistan.
- The Kazakhstan agreement and JazzCash recognition both point to VEON using telecom reach to embed payments, transfers and micro insurance into everyday digital usage. This can affect transaction volumes, fee pools and the economics of its broader digital services strategy.
- We will now examine how VEON's push into regulated digital payments with Kazakhstan's central bank could reshape its broader investment narrative.
Scan beyond VEON and this news by reviewing a curated set of telecom and fintech plays with resilient digital economics in our list of solid balance sheet and fundamentals (23 results)
VEON Investment Narrative Recap
To own VEON, you need to believe the telecom footprint can support a much bigger digital services and fintech layer across Pakistan, Ukraine, Kazakhstan, Bangladesh and Uzbekistan. The key near term swing factor is whether digital products like payments and micro insurance can scale cleanly on top of that base without further compressing already thin 1.2% net margins.
The biggest risk stays the same. High gross debt of about US$4.6b and interest that is not well covered leave little room for execution missteps, especially in volatile currencies. The Kazakhstan memorandum and JazzCash awards help the long term story, but they do not materially change that immediate financing and margin pressure.
The JazzCash recognition at The Money Awards 2026 is the clearest operational proof point connected to this news. Digital disbursement of more than PKR 100b to over 3 million welfare beneficiaries and 2.38 million active Sehat+ health insurance customers shows VEON can run large scale, regulated financial services through its telecom rails.
If VEON can apply that JazzCash experience to Kazakhstan under the new memorandum, the main potential upside is clearer monetisation of digital financial services on top of connectivity. The execution watchpoints are licensing in Kazakhstan, integration with the National Payment Corporation infrastructure and the cost of compliance in markets that already carry macro and FX risk.
VEON's narrative projects US$5.7b revenue and US$645.7m earnings by 2029. This implies 7.6% yearly top line growth and an earnings increase of about US$113.7m from US$532.0m today.
Uncover how VEON's fair value indicates a 20% potential upside to its current price, which could narrow quickly.
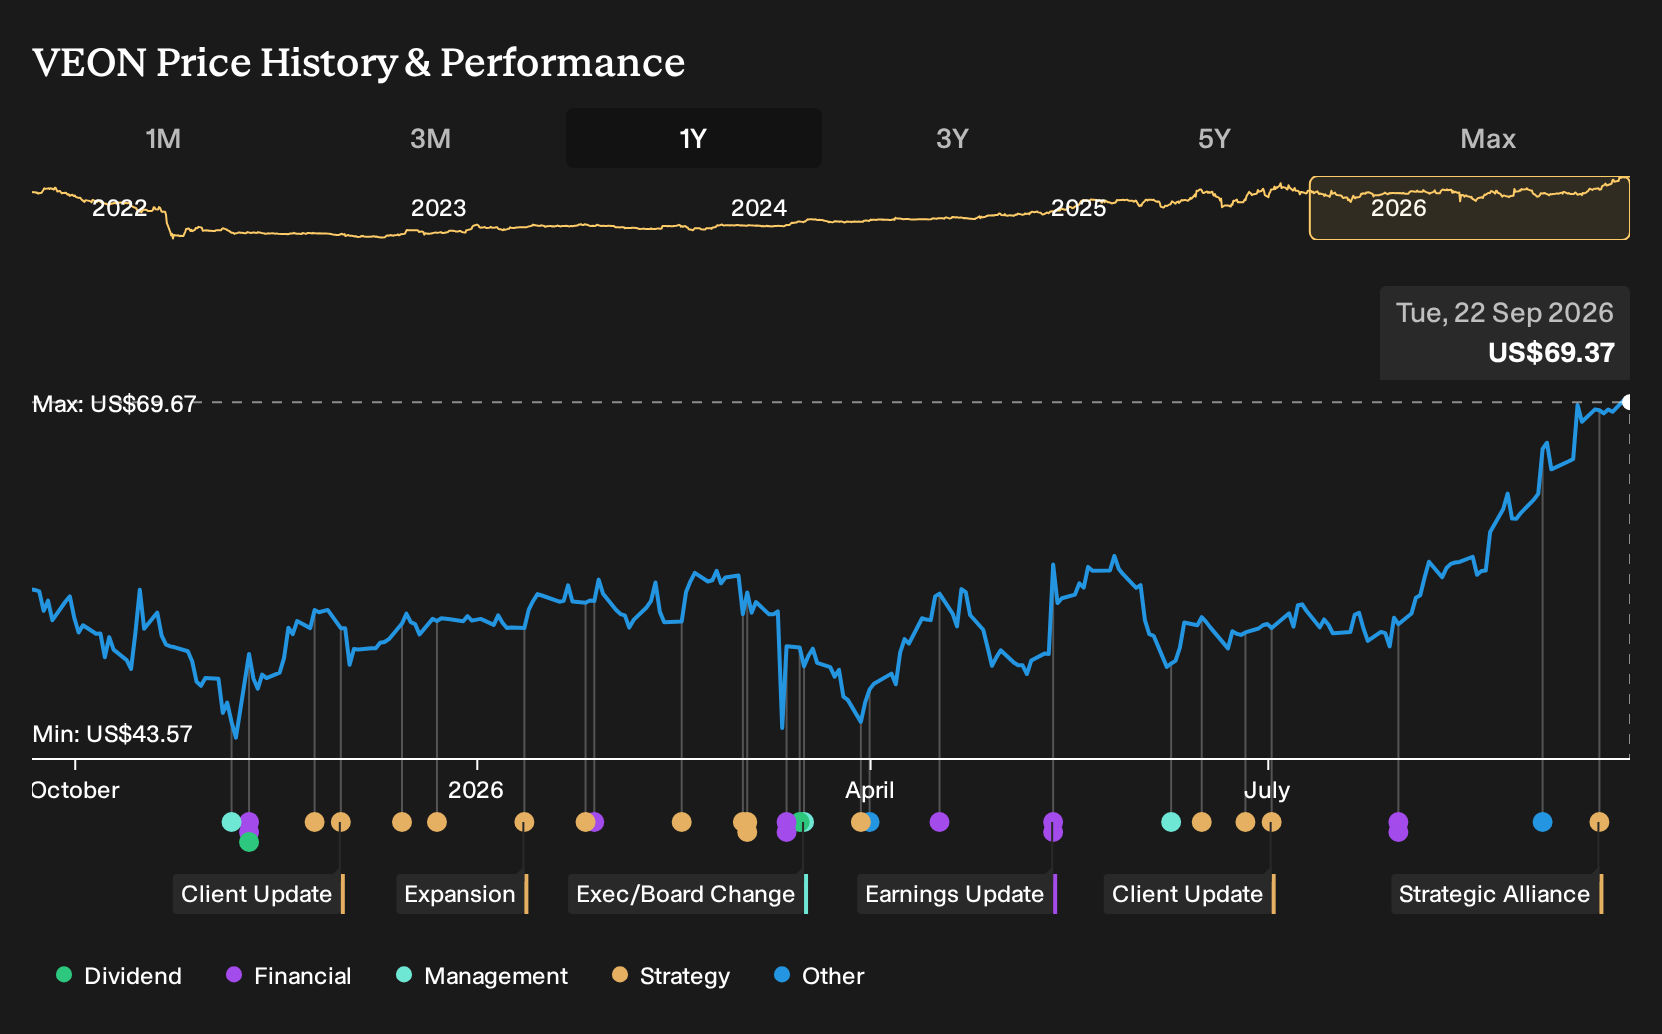
Exploring Other Perspectives
Some of the most optimistic analysts frame this Kazakhstan move as potential proof that VEON’s fintech push can support much higher earnings than consensus expects. Before this news, the bullish camp was already pencilling in about US$5.1b of revenue and US$843.2m of earnings by 2028. You can compare that to your own view by exploring several alternative forecasts and deciding which story feels more convincing.
Explore 4 other VEON fair value estimates, including one that suggests as much as 754% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your VEON research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for VEON. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate VEON's overall financial health at a glance.
Looking For More Investment Ideas Beyond VEON?
If the VEON story has you thinking about where else resilient balance sheets and repeatable cash flows might be hiding, the Simply Wall St Screener can help you cast a wider net without getting lost in thousands of tickers.
- For investors who want quality at a sensible entry point, start with a basket of companies highlighted in our 29 high quality undervalued stocks that combine stronger fundamentals with what our models flag as discounted pricing.
- If capital preservation and steadier risk profiles matter most to you, narrow the field to a curated group of 30 resilient stocks with low risk scores that score well on financial strength and volatility checks.
- When you are hunting for businesses that can better weather funding cycles and credit shocks, focus on the list of solid balance sheet and fundamentals (23 results) to see which stocks pair conservative leverage with healthier core metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com