
Exor (ENXTAM:EXO) Faces A Big Fair Value Gap On H1 2026 Loss
Exor (ENXTAM:EXO) has drawn attention after reporting a half-year 2026 net loss of €1,122 million, with basic and diluted loss per share from continuing operations at €5.54, compared with €3 a year earlier.
Despite the deeper half year loss, Exor’s recent share price has been relatively steady, with a 90 day share price return of 9.59%, but a year to date share price return that is down 2.06%, while the 1 year total shareholder return is down 14.62%, hinting at fading longer term momentum.
Scan beyond Exor’s setback and review a curated 173 high quality undervalued stocks that currently combine weaker sentiment with solid fundamentals.
Short term traders see a 90 day gain, while long term holders see a 1 year decline and a deeper loss. For Exor, does that justify buying now, or waiting for a cheaper entry before committing fresh capital?
Preferred Price-to-Book of 0.4x for Exor: Is it justified?
On simple metrics, Exor looks inexpensive. The stock last closed at €71.45, while it trades on a P/B ratio of 0.4x that sits well below both its direct peers and the broader European diversified financials group.
P/B compares the market price of each share with the accounting value of net assets backing that share. For an investment holding group like Exor, where much of the value is tied to stakes in other businesses and financial assets, this measure often gives a quick sense of how the market is pricing those underlying holdings relative to book value.
The current 0.4x P/B suggests investors are paying well under the stated equity base for Exor, while the peer group sits at 4.3x and the wider European diversified financial industry averages 0.9x. That is a steep discount in both absolute and relative terms, which points to the market assigning a heavy penalty to factors such as current losses, funding mix, or risk profile rather than paying up for Exor’s portfolio.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-book of 0.4x (UNDERVALUED)
Still, Exor’s half year net loss of €1,122 million and a 1 year total shareholder return that fell 14.62% could keep sentiment fragile and maintain pressure on the discount.
Find out about the key risks to this Exor narrative.
Another view on Exor’s value
The earlier P/B discussion paints Exor as inexpensive versus both peers and the wider European diversified financial group. A very different picture appears when looking at our DCF model, which places the future cash flow value at €833.71 per share compared with the current €71.45, implying a very large gap.
That kind of difference suggests either the market is heavily discounting Exor’s forecasts, or the model is assigning optimistic weight to long term assumptions. For an investor weighing those signals, which side of that gulf feels more realistic?
Look into how the SWS DCF model arrives at its fair value.
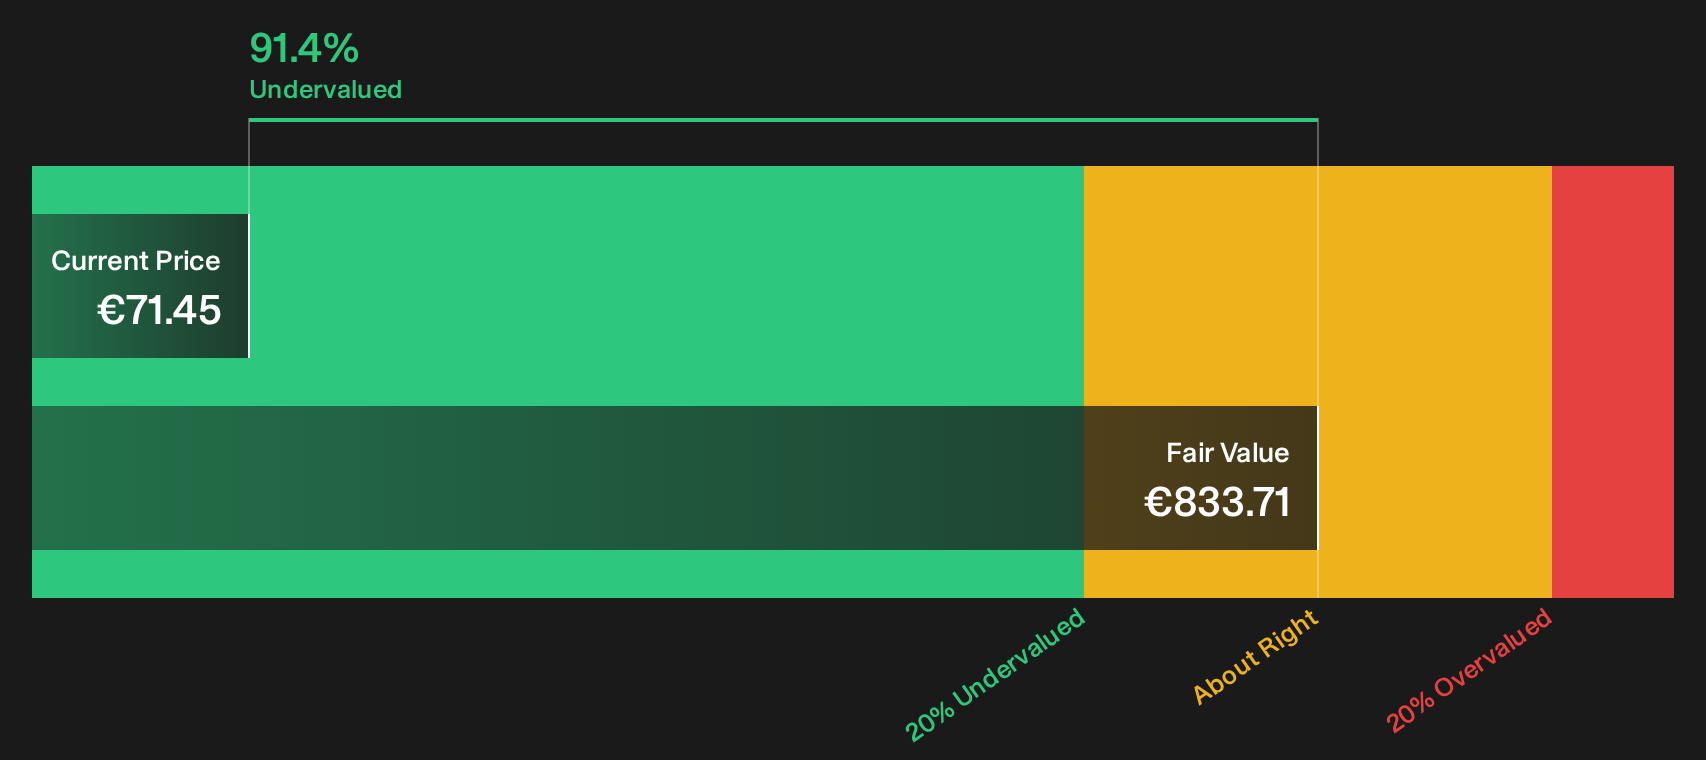
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Exor for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 173 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Exor’s losses and discounted valuation can feel messy, so move quickly, review the key data points, and pressure test both sides of the story by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Exor?
If Exor’s valuation gap has you thinking harder about where to put your next euro, consider broadening your watchlist with a few targeted idea sets.
- Target stability and income by reviewing a curated pool of companies offering resilient yield profiles through the 161 dividend fortresses.
- Hunt for quality at a discount by assessing opportunities where fundamentals and pricing line up in the 173 high quality undervalued stocks.
- Focus on financial strength by filtering for businesses with robust balance sheets and cleaner fundamentals using the list of solid balance sheet and fundamentals (198 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com