
How to Play Google Stock as Trump TV Launches on YouTube
Alphabet (GOOG) (GOOGL) is steadily expanding YouTube’s role in the digital-video ecosystem, taking the platform well beyond its traditional creator-driven roots. Live events, news, and connected TV viewing are becoming increasingly important to the business, with the launch of “Trump TV” offering a timely example of that evolution.
The White House launched the 24/7 stream after banning major news organizations from accessing White House press events. It is a White House-produced YouTube stream featuring presidential speeches, administration announcements, archived footage, and selected highlights. In effect, the initiative appears to be a new attempt to utilize YouTube as a direct-to-viewer outlet for live, politically significant programming.
YouTube’s latest results underscore its growing momentum across several areas of the business. In Q2 FY2026, YouTube’s advertising revenue rose nearly 13% year-over-year (YoY), while Alphabet reported that more than 1.7 billion unique viewers watched World Cup-related content.
Management is also investing in connected TV, Shorts, and Demand Gen, alongside AI-powered features such as Ask YouTube, which had more than 140 million watch-page users in June. Taken together, these developments point to a broader shift in how YouTube is being used and monetized.
With that in mind, let’s see how these developments could affect GOOGL stock.
About Alphabet Stock
The Mountain View, California-based Alphabet is the parent company of Google and operates worldwide across technology, advertising, cloud computing, and digital services.
Its Google Services segment spans some of the company’s most widely used products, including Search, YouTube, Android, Chrome, Gmail, Maps, Google Play, and devices, alongside advertising and subscription offerings such as YouTube Premium and Google One for consumers and businesses worldwide.
Google Cloud is another major pillar of Alphabet’s business. It provides customers with artificial intelligence (AI), cloud infrastructure, cybersecurity, data analytics, and collaboration solutions through offerings including Gemini, Vertex AI, and Google Workspace. Alphabet also operates its Other Bets segment, which invests in newer businesses, including transportation and internet services.
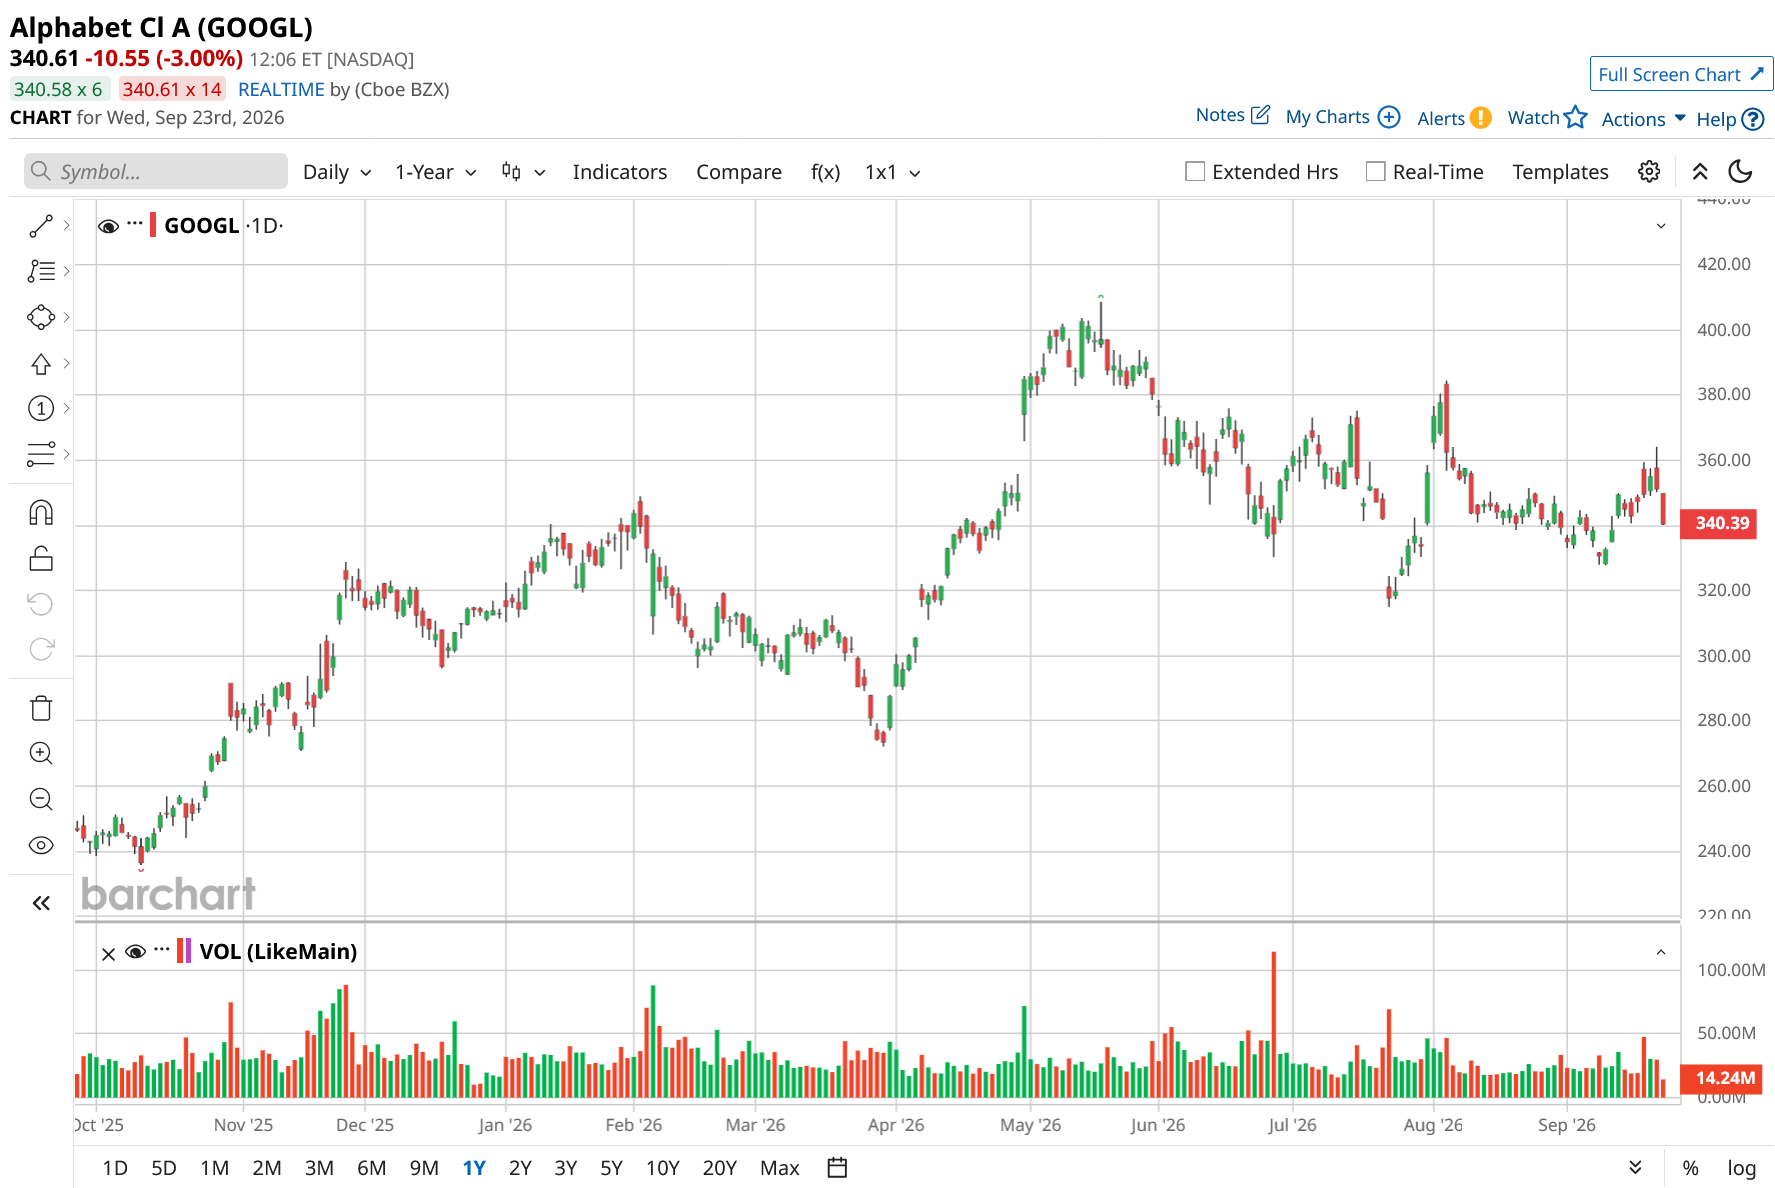
With a market cap of roughly $4.3 trillion, Alphabet’s share performance reflects the market’s continued confidence in the company’s ability to sustain growth across its major businesses. GOOGL stock has climbed 36% over the past 52 weeks, advanced 9% since the start of the year, and gained 13% over the last six months.
However, the shares are not trading at bargain-basement multiples. GOOGL stock is currently sitting at 17.21 times forward adjusted earnings and 8.71 times sales. Both measures are above their respective industry averages, suggesting investors are paying a premium for Alphabet.
The company also pays an annual dividend of $0.88 per share, giving the stock a 0.25% dividend yield. Its latest dividend payment of $0.22 per share was paid on Monday, Sept. 14, to shareholders of record as of Monday, Sept. 7.
Alphabet Surpasses Q2 Earnings
Alphabet delivered a strong Q2 FY2026 on July 22, with revenue increasing 24.2% YoY to $119.8 billion, marking the company’s 12th consecutive quarter of double-digit growth. The result also exceeded the Street’s $117.2 billion forecast. Earnings were similarly strong, with EPS rising 294.4% YoY to $9.11, significantly above analysts’ $2.90 estimate.
Operating income increased 30.4% YoY to $40.8 billion, while the operating margin expanded to 34% from 32%. The margin expansion is notable given Alphabet’s significantly higher spending on AI infrastructure and points to continued operating leverage. Net income also soared 297.6% from the year-ago period to $112.1 billion.
Google Services remained the largest contributor, with revenue up 14.5% YoY to $94.5 billion. Search & other revenue increased 16.8% to $63.3 billion, supported by higher query activity and growing adoption of AI features. YouTube ads rose 12.9% to $11.1 billion, while subscriptions, platforms, and devices increased 15.2%. The key soft spot was Google Network, where revenue marginally fell from the prior-year quarter to $7.3 billion.
The standout growth driver was Google Cloud. Revenue climbed 81.8% YoY to $24.8 billion, led by enterprise AI solutions, AI infrastructure, and core GCP services. Cloud operating income more than tripled to $8.8 billion, with the business generating a 35.6% operating margin. The backlog reached $514 billion, underscoring the strength of demand.
The principal trade-off is the scale of Alphabet’s investment cycle. Capital expenditures reached $44.9 billion in Q2, contributing to negative free cash flow of $5.9 billion. Alphabet has subsequently raised its full-year capex outlook to $195 billion to $205 billion, up from the $180 billion to $190 billion forecast provided last quarter, citing demand outpacing available capacity, and expects capex to increase significantly in 2027.
On that note, Wall Street expects Q3 FY2026 EPS to increase 2.1% YoY to $2.93. For full-year FY2026, they project the bottom line to grow 89.7% YoY to $20.51, while FY2027 could see the EPS plunge 28.3% YoY to $14.71.
What Do Analysts Expect for GOOGL Stock?
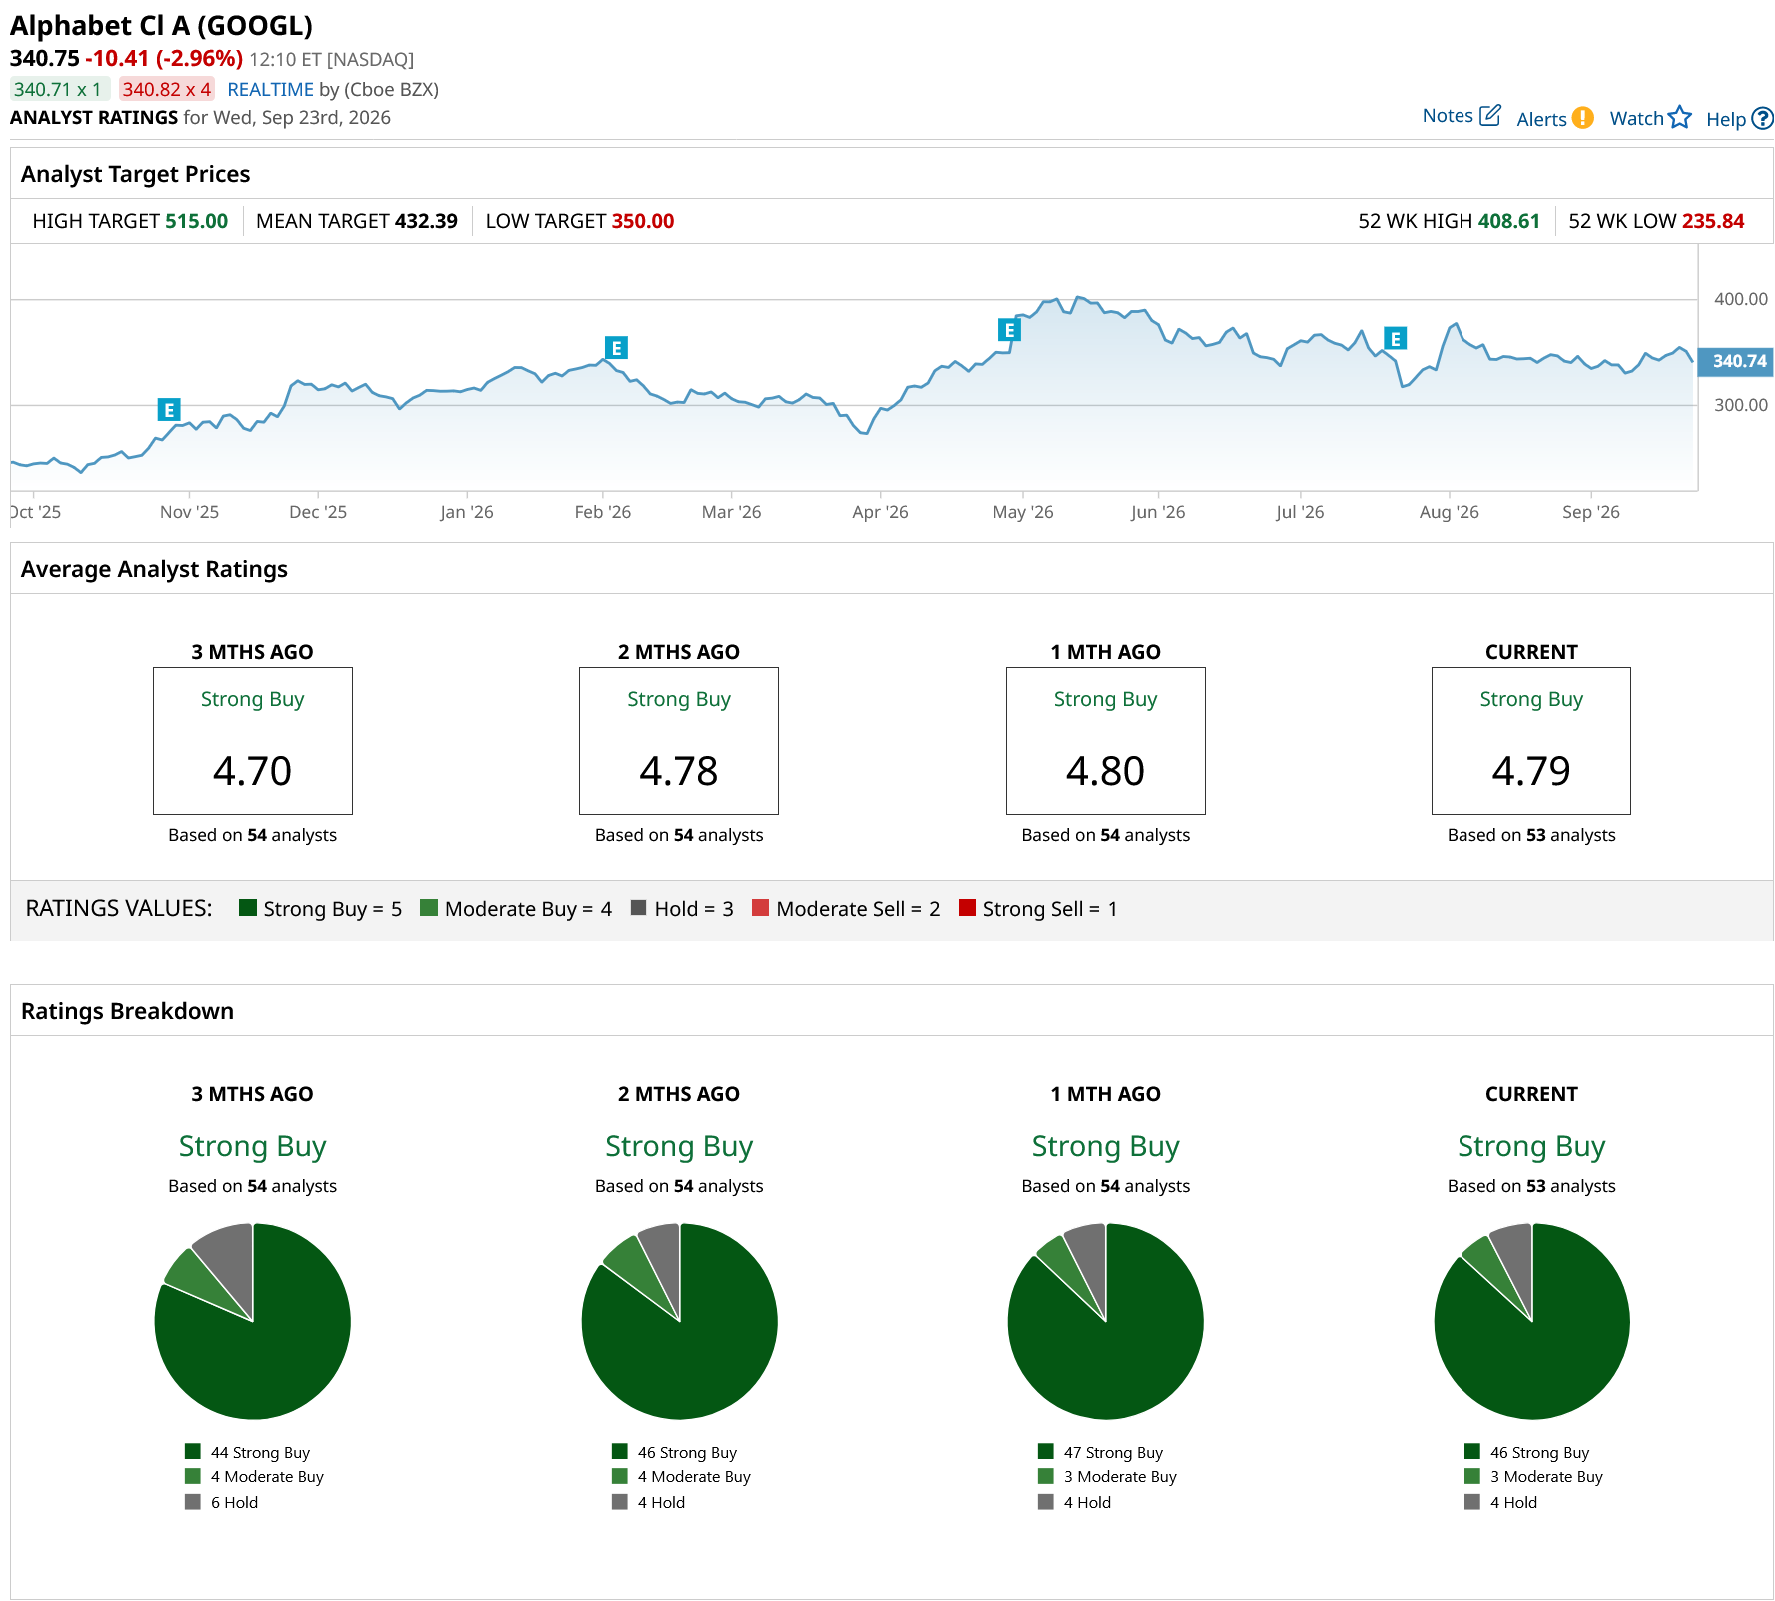
Given the strategic business moves backed with solid financial numbers, Wall Street’s current view of Alphabet remains strongly positive, with the stock carrying a consensus “Strong Buy” rating. Of the 53 analysts covering GOOGL stock, 46 rate the stock “Strong Buy,” three recommend “Moderate Buy,” and four suggest “Hold.”
To that end, GOOGL’s average price target of $432.39 represents a potential upside of 27%, while the Street-high target of $515 suggests a gain of 51% from current levels.
On the date of publication, Aanchal Sugandh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.