
Is Applied Materials (AMAT) A Bargain Following Analyst Upgrades And Its India Expansion Plan?
Recent optimism around Applied Materials (AMAT) is tied to a cluster of catalysts. Analyst upgrades, higher earnings estimates and stronger wafer equipment spending forecasts are converging with the company’s new US$5b India expansion plan.
Applied Materials’ share price has surged 75.72% year to date and the total shareholder return over the past 12 months is 136.51%. The recent 12.18% 7 day share price gain suggests momentum is building again despite a 19.78% decline over 90 days.
Scan how Applied Materials fits into the broader AI and chip equipment story by comparing it with our hand picked 86 AI infrastructure stocks for this same buildout theme.
Bulls point to Applied Materials’ AI exposure, India buildout and upbeat earnings estimates. Bears focus on the recent 3 month pullback and chip capex risk. Which side does the current valuation actually support?
Most Popular Narrative: 25% Undervalued
Applied Materials last closed at $472.46, while the most followed narrative places fair value near $627.66. This implies a sizeable valuation gap that hinges on how durable the current AI equipment cycle really is.
The ongoing explosion in data creation and rapid adoption of digital transformation (IoT, automotive, industrial automation) continue to accelerate wafer fab buildouts globally, with over 100 new fabs or expansions tracked this year, and Governments incentivizing regional manufacturing. Applied's broad portfolio and investments in local manufacturing infrastructure (e.g., new Arizona and EPIC centers) position it to capture a greater share of this growing and more geographically diverse capital expenditure, supporting both revenue growth and margin resilience.
See why 306 investors see Applied Materials as 25% undervalued.
Result: Fair Value of $627.66 (UNDERVALUED)
Still, the narrative can crack if export restrictions in China tighten further, or if a few key customers sharply rein in wafer equipment budgets.
Find out about the key risks to this Applied Materials narrative.
Another View: Applied Materials Through A Cash Flow Lens
The popular Applied Materials narrative leans on analyst targets that suggest upside to $627.66. A different lens tells a very different story. The SWS DCF model estimates the value of future cash flows closer to $277.69, which would frame today’s $472.46 share price as rich rather than cheap. Which version of “fair” feels more realistic to you?
For readers who want to see how this cash flow based result is built step by step, walk through the SWS DCF model assumptions and output here, then judge how comfortable you are with each input before leaning on either valuation view. Look into how the SWS DCF model arrives at its fair value.
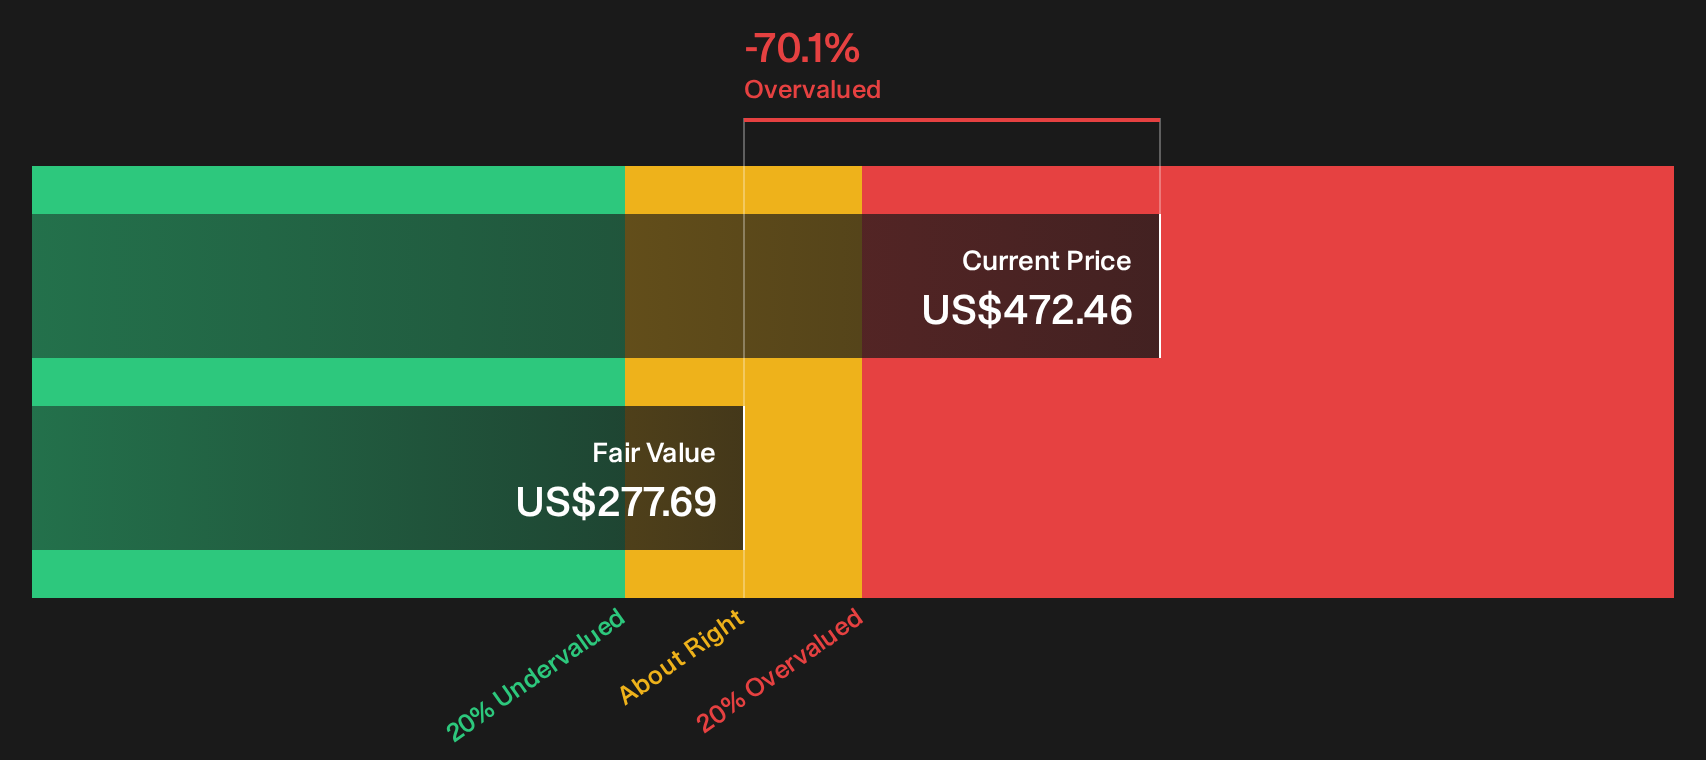
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Applied Materials for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Applied Materials are clear, so move quickly. Review the full data set yourself and weigh both the upside and the weak spots in context with the 4 key rewards and 2 important warning signs.
Looking for more Applied Materials sized ideas?
If you stop at Applied Materials, you risk missing other setups that fit your style. Put a few minutes into fresh ideas so your watchlist keeps working for you.
- Target stronger pricing power and quality by scanning a 29 high quality undervalued stocks that filters for fundamentals rather than headlines.
- Prioritise resilience by searching a 30 resilient stocks with low risk scores built around balance sheet strength and lower volatility profiles.
- Hunt for early stage opportunities by reviewing a 9 elite penny stocks with strong financials where financial health does the heavy lifting.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com