
AT&T (T) Stock Trades At A Discount To Its Earnings
AT&T has delivered a strong multi year share price gain, and with the stock last closing at US$25.10 the live question is whether that move is still matched by the earnings behind it. Recent news on wireless growth, new services and customer incentives adds more moving parts to the story, so the link between the current price and the profit stream deserves a closer look.
- Over the past 3 years, AT&T has returned 95.7%, which puts real pressure on the current earnings base to carry that kind of value today.
- Fresh initiatives like Cricket 5G Home Internet and bundled virtual healthcare access can influence how investors think about future revenue mix, margins and the timing of cash flows that support today’s valuation.
- Your read on AT&T is one view; the desks covering it have another. See what analysts think AT&T's shares could be worth.
The stock's next move may depend on whether AT&T's current earnings are enough to justify the price investors are paying today.
If you are weighing AT&T's earnings against its recent share price run, it can help to compare that story with other companies screened for 29 high quality undervalued stocks
Is AT&T Still Cheap on Earnings?
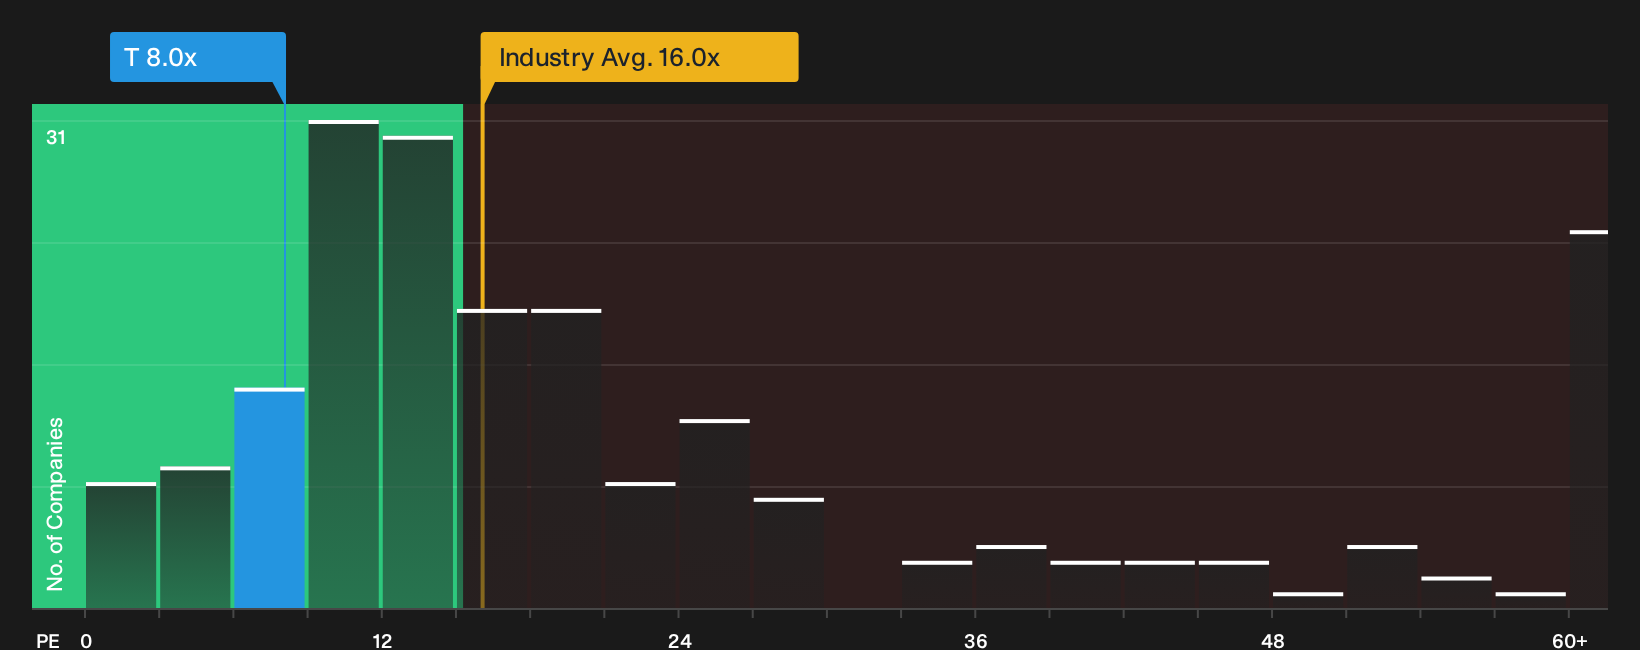
The P/E ratio is a useful lens for AT&T because earnings still anchor how investors judge a mature telecom group. AT&T trades on a P/E of 8.0x, which is below both the Telecom industry average of 16.0x and the peer group average of 10.1x. On this framework, the stock changes hands at a lower price for each dollar of profit than many rivals.
The fair P/E that a valuation model suggests for AT&T is higher than where the shares trade now, which points to the stock being undervalued on this metric. Because the recent upgrades around potential wireless service revenue growth have already put fresh attention on AT&T, the current discount implies the market is still applying a cautious lens to those earnings. For investors, the gap between today’s multiple and the modelled fair level is the key figure to weigh against AT&T’s balance sheet, capital spending needs and competitive position. Explore the numbers behind AT&T's P/E valuation.
The AT&T Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for AT&T pick up where the P/E debate leaves off by explaining which potential paths for AT&T's future earnings, margins and cash generation would need to occur for the current share price to appear either stretched or conservative. Each scenario links its figures to a clear view of how growth, profitability and key risks might evolve, which you can revisit as new information on the business arrives on the Community page.
Investor opinion on AT&T splits between those who see fiber and satellite partnerships as underappreciated and those who worry that heavy spending and new rivals cap the upside.
Bull case: 14% undervalued
"Retiring legacy copper and wireline infrastructure is driving structural cost reductions, enabling improved operating leverage and higher free cash flow..."
Discover why this Narrative puts AT&T at 14% undervalued.
Bear case: 18% overvalued
"AT&T's continued heavy investment in 5G and fiber infrastructure, amounting to $22 billion, coupled with reliance on potential tax incentives..."
Explore why this Narrative puts AT&T at 18% overvalued.
One more angle on AT&T that could change the story
Price tags and profit multiples only go so far if the people steering AT&T pull in rewards that are out of sync with long term shareholder outcomes. It is therefore worth checking who is in charge and how they are incentivised. See who runs AT&T and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com