
How Is Stanley Black & Decker's Stock Performance Compared to Other Industrial Stocks?
New Britain, Connecticut-based Stanley Black & Decker, Inc. (SWK) is a diversified global provider of hand tools, power tools and related accessories, mechanical access and electronic security solutions, healthcare solutions, engineered fastening systems, and more. Valued at $13.9 billion by market cap, the company offers onshore and offshore pipeline construction and inspection services.
Companies worth $10 billion or more are generally described as “large-cap stocks,” and SWK perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the tools & accessories industry. SWK's strengths include its diversified portfolio, scale, and brand equity, enabling the company to leverage resources and drive growth. Its robust balance sheet, technological capabilities, and innovation ecosystem also position it for success, with a strong strategic fit for trends like cordless power tools, driving premium pricing and customer loyalty.
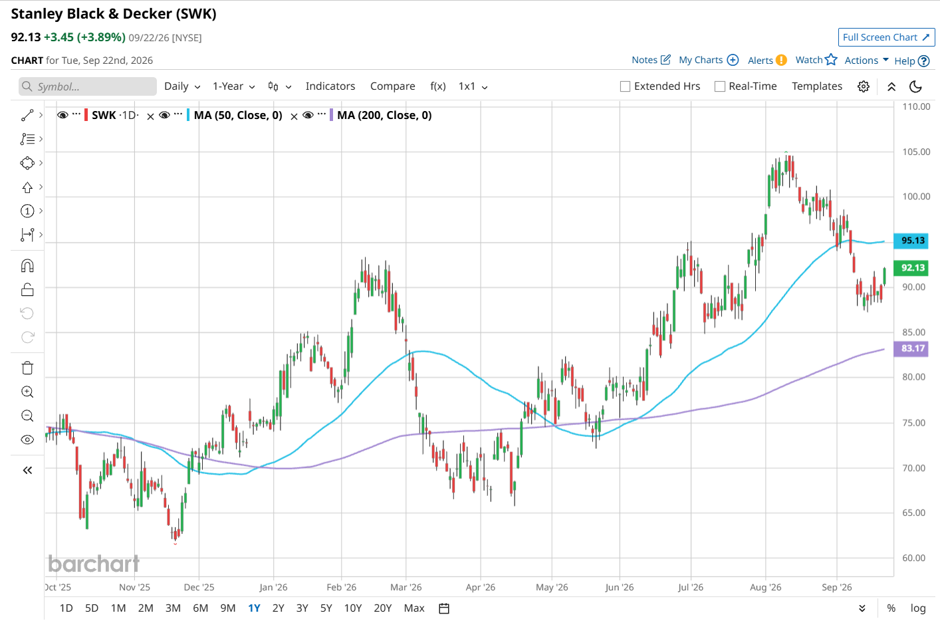
Despite its notable strength, SWK slipped 12% from its 52-week high of $104.68, achieved on Aug. 11. Over the past three months, SWK stock has gained 6.7%, outperforming the State Street Industrial Select Sector SPDR ETF’s (XLI) 6.3% losses during the same time frame.
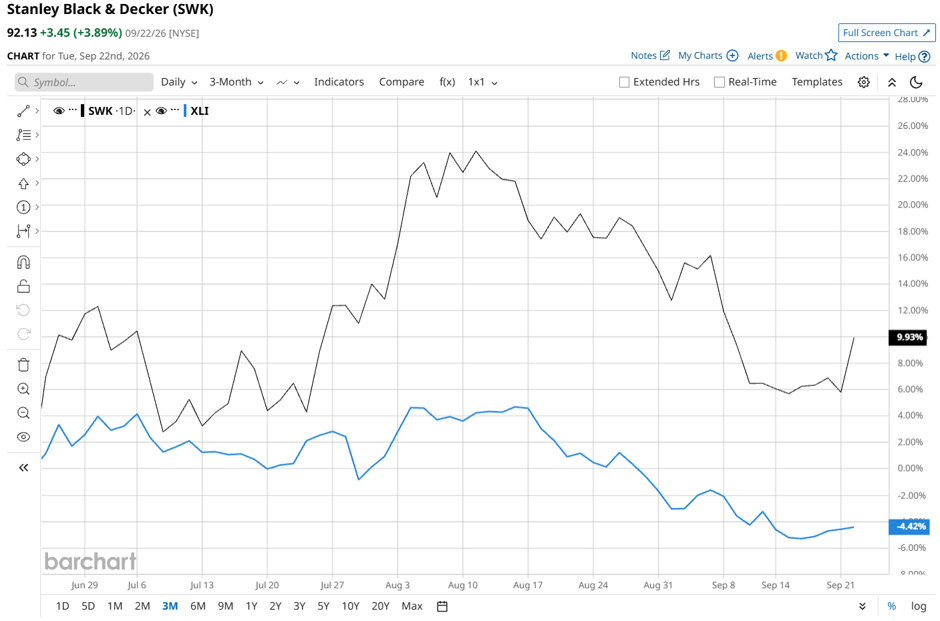
In the longer term, shares of SWK rose 24% on a YTD basis and climbed 22.8% over the past 52 weeks, outperforming XLI’s YTD gains of 9.8% and 11.3% returns over the last year.
To confirm the bullish trend, SWK has been trading above its 200-day moving average since late April, with minor fluctuations. However, the stock has been trading below its 50-day moving average since early September.
SWK's outperformance was driven by significant margin expansion, with Tools & Outdoor margin up 380 bps YoY on productivity initiatives, favorable product mix and about 250 bps benefit from tariff refunds. Organic growth was supported by 8% growth in power tools, fueled by strong demand, new product launches and improved placement with U.S. retail and commercial partners, with all three priority brands, DEWALT, STANLEY and CRAFTSMAN, posting growth. Engineered Fastening also delivered 3% organic growth led by auto and industrial. CEO Christopher Nelson and CFO Patrick Hallinan credited disciplined execution and said tariff refunds are being pulled forward to accelerate investment in innovation, marketing and sales resources, while productivity should offset material inflation, though further price increases may be needed going forward.
SWK’s rival, Snap-on Incorporated (SNA) has lagged behind the stock, with 7.9% gains on a YTD basis and a 10.2% uptick over the past 52 weeks.
Wall Street analysts are reasonably bullish on SWK’s prospects. The stock has a consensus “Moderate Buy” rating from the 16 analysts covering it, and the mean price target of $99.67 suggests a potential upside of 8.2% from current price levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.