
3 U.S. AI Hardware Stocks With Direct Data Center Exposure
AI hardware has moved from a niche story to front-page policy risk, with Washington and Beijing arguing over chips while data centers keep ordering more compute. That mix of political friction and infrastructure build-out creates both air pockets and potential openings for investors who follow where GPUs, HBM and power systems really matter. This article unpacks the news and discusses three stocks directly exposed to these AI headlines.
The stocks covered below are just a first pass. The full screen pulled out 34 more U.S. and Taiwan listed AI hardware suppliers with equally compelling stories that are not broken out in this article.
To go straight to the source and identify your own highest conviction AI data center hardware ideas, head into the U.S.-Listed AI Hardware Suppliers to Data Centers screener.
ON Semiconductor (ON)
ON Semiconductor plugs directly into the AI hardware story, supplying the power and sensing chips that keep data centers fed with efficient electricity, rather than GPUs alone shaping the narrative.
ON Semiconductor runs three major lines linked to this AI build out. Power Solutions Group generates about US$3.0b, Analog & Mixed Signal brings in roughly US$2.2b and Intelligent Sensing adds around US$900 million. That mix supports a business valued near US$27.9b by the market.
The company’s role in AI data centers hinges on how far its power technologies can move up the value chain.
"The company's strategic investments in silicon carbide (SiC), wide bandgap technologies, and advanced power management solutions for both automotive and AI data centers position it at the forefront of key structural growth markets; as these high-value products ramp, they are expected to enhance margins and drive long-term earnings growth."
What really matters now is how one pressure point in its capital and product mix shapes the balance between growth and profitability.
That trade off is exactly what the full narrative for ON Semiconductor unpacks, separating headline SiC enthusiasm from where ON Semiconductor’s earnings power could really be accelerating or stalling next.

Jabil (JBL)
Jabil is one of the quiet powerhouses behind AI hardware, building cloud data center servers and related electronics for the companies rolling out GPU heavy racks, while also running a broad contract manufacturing operation across healthcare, automotive and connected devices.
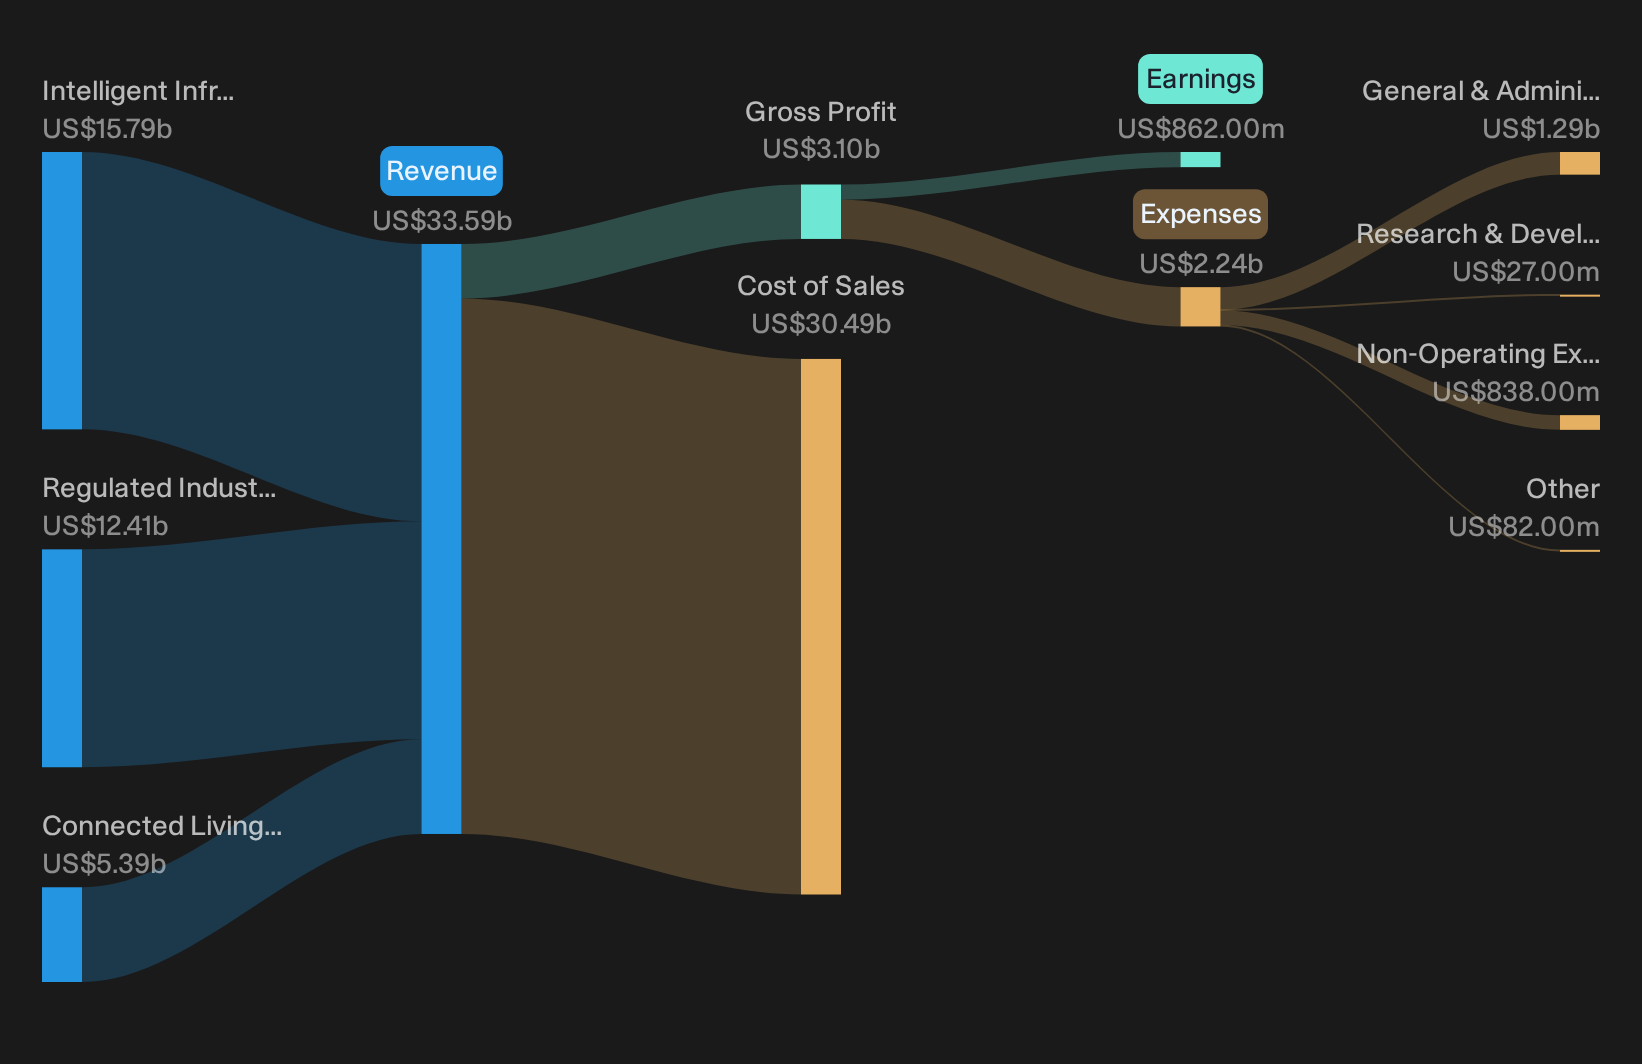
Regulated Industries contributes about US$12.4b of revenue, Intelligent Infrastructure around US$15.8b, and Connected Living and Digital Commerce roughly US$5.4b, underpinning a business valued at about US$31.8b in the market.
Jabil matters for this screener because it sits where AI data center ideas turn into shipped hardware, from server platforms to optical and power rich subsystems, and its scale in design plus manufacturing gives it leverage when customers refresh whole fleets of equipment.
"Jabil's expansion in India, particularly in Gujarat, to support photonics capabilities indicates growth potential in a promising market, likely enhancing future revenues from domestic demand and infrastructure projects."
What really shapes the AI upside is how far that fast rising AI hardware pipeline can support margins if one hidden cost pressure shifts direction.
That inflection point is exactly what the full narrative for Jabil maps out, showing where Jabil’s AI momentum could be accelerating, masking risk, or quietly decoupling from headline demand.
Fabrinet (FN)
Fabrinet plugs directly into the AI data-center hardware theme, handling the optical and electro-mechanical manufacturing that lets GPUs talk to each other at high speed across modern server halls.
Fabrinet, valued at about US$14.4b, earns roughly US$4.6b from optical networking equipment, tightly tying its manufacturing work to data-heavy infrastructure that feeds AI demand.
Investors looking for a pure play on AI data-center plumbing find Fabrinet where optical packaging, high-speed interconnects and hyperscaler programs intersect for this screener.
"Surging AI related data center optics and DCI demand, with data center revenue at 51% of total and Q4 FY26 DCI products at more than a 1b annualized run rate, points to a multi year build out that could keep Fabrinet’s utilization and data center revenue elevated."
What could really move the needle now is how one underappreciated shift in its AI customer mix reshapes both pricing power and earnings quality.
That shift in buyer mix is exactly what the full narrative for Fabrinet unpacks, highlighting where Fabrinet’s AI optics momentum could be accelerating, where it could be masking risk, or where it could be quietly decoupling from headline demand.

Seeking Alternatives Before The Crowd?
Fresh breakouts and quiet momentum stories rarely stay under the radar for long. Before today’s data gets stale and prices get away, investors may want to review the latest ideas while they are still timely.
- Identify resilient balance sheets and steady cash engines before they are fully reflected in prices by scanning the curated list of solid balance sheet and fundamentals (23 results).
- Explore companies tied to automation demand while valuations still look reasonable by focusing on the carefully filtered 95 robotics and automation stocks.
- Review potential opportunities related to critical metals by examining the tightly curated 35 best rare earth metal stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com