
Top 3 Japanese AI Stocks Trading At Least 28% Below Fair Value
Concerns around market confidence in AI company valuations have resurfaced after the OECD flagged them alongside higher bond yields and energy costs. That kind of doubt can create pricing gaps in Japanese artificial intelligence stocks that are actually tied to real products and infrastructure. This article highlights three companies from an undervalued AI screener that could help you focus on fundamentals rather than hype.
The three stocks below are only a sample from the undervalued AI screen. This screen also surfaced 12 more Japanese companies with equally compelling stories around chips, software and infrastructure that are not covered here.
If you want to go beyond this short list and identify your own highest conviction angles on the ChatGPT and AI buildout, head straight to the Undervalued Artificial Intelligence/ AI Stocks screener to filter and analyze the full universe of candidates.
Cresco (TSE:4674)
Cresco is a Tokyo based IT services group that builds and maintains enterprise, financial and embedded systems while also running a Digital Solution business focused on AI projects, RPA and data analytics for corporate clients. The company has a market value of about ¥73.6b.
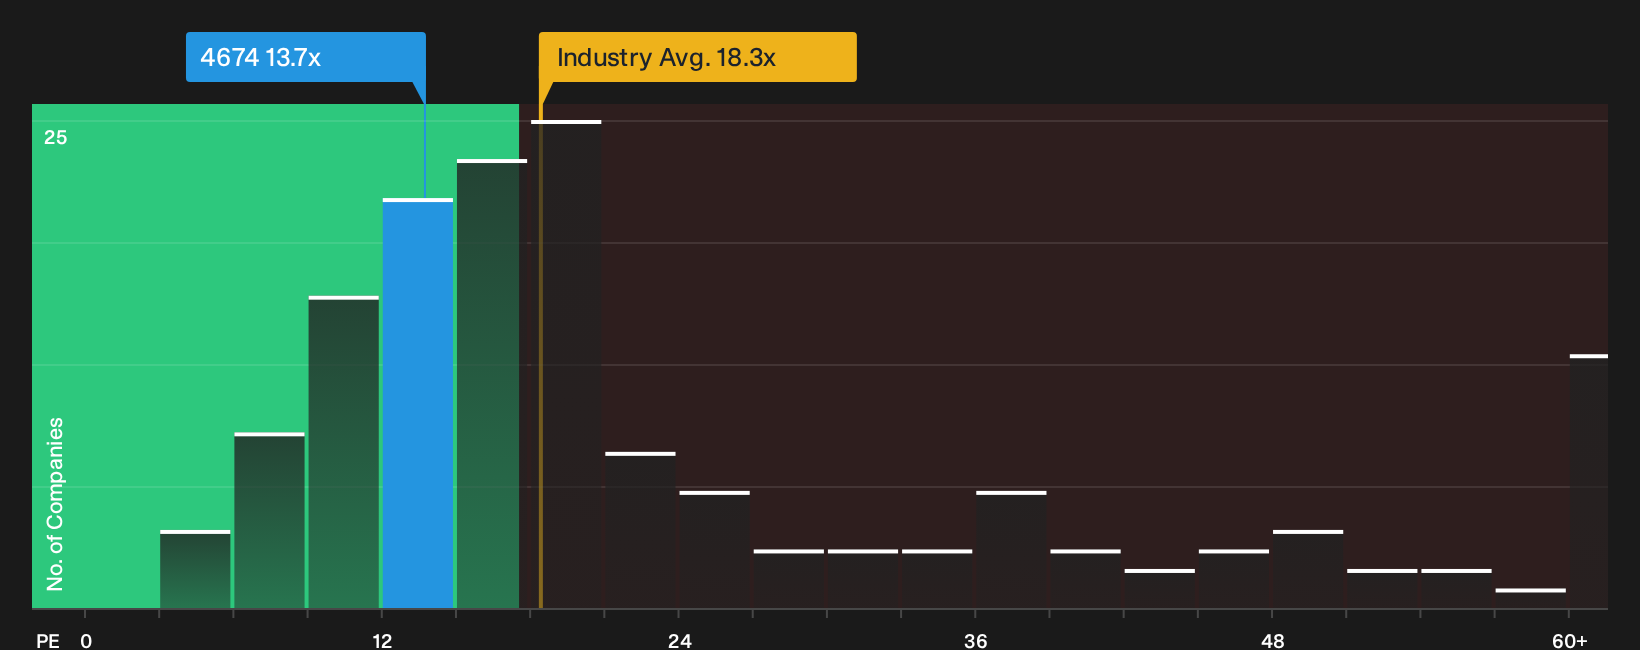
Cresco is directly exposed to the AI theme through its Digital Solution Business, where it develops and deploys AI systems, cloud based solutions and automation for Japanese enterprises that want to put tools like ChatGPT style models to work inside real workflows. Reported earnings growth of 22.4% year over year and a P/E of 13.7x compared with the 18.3x industry average provide AI focused investors with a combination of recent profit momentum and a lower valuation multiple relative to peers, although future returns depend on how demand evolves for those higher margin digital projects.
Those digital projects are only part of Cresco’s story, so it is worth scanning the 2 key rewards and 1 important warning sign before deciding how durable that momentum really is.
Systena (TSE:2317)
Systena is a Tokyo based IT services group that helps enterprises plan, build, test, and run software, while its Digital Integration and IT & DX Service units focus on AI system development, RPA, and AI/IoT cloud platforms. The business has a market value of about ¥157.3b.
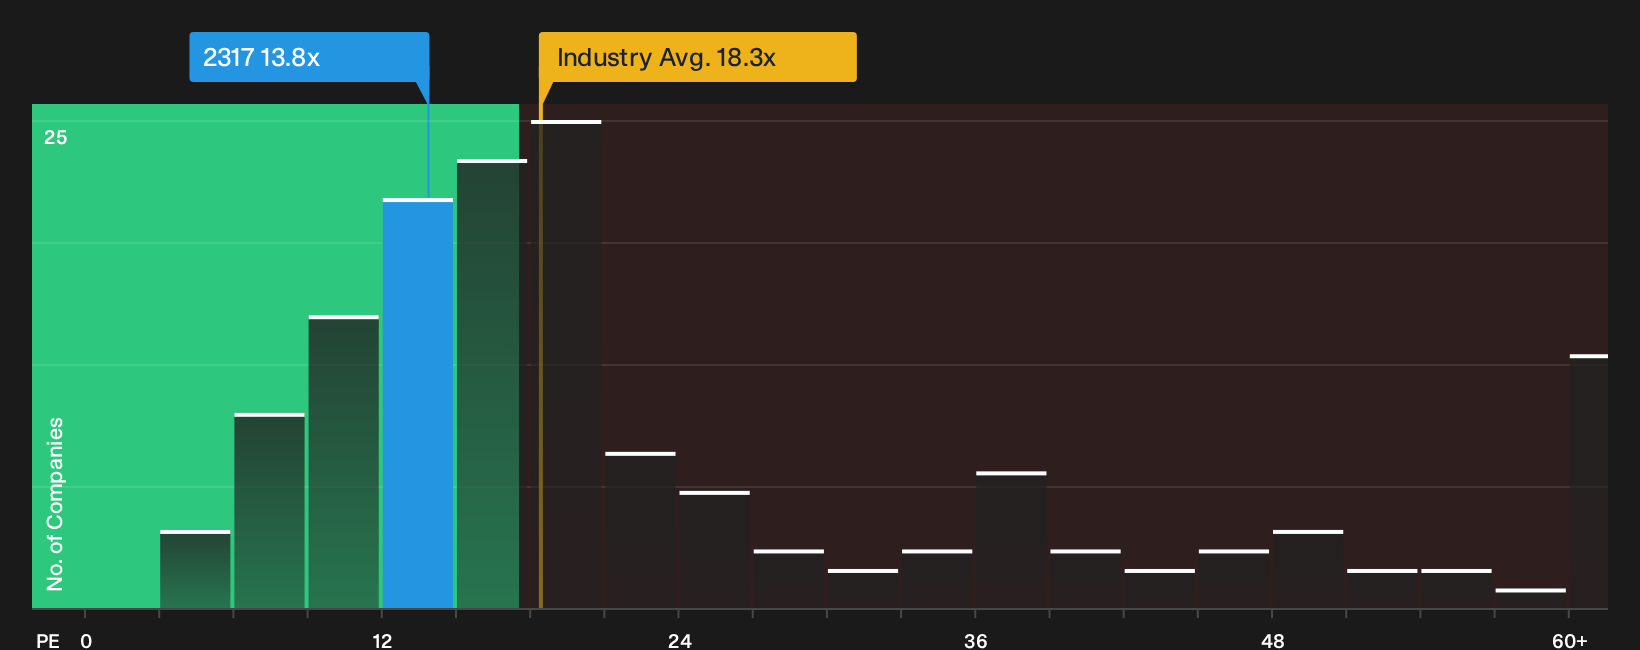
Systena gives investors exposure to practical AI deployment through its AI/IoT platforms and DX services that help clients automate workflows and analyze data, while trading at what appears to be a discounted valuation with growing earnings and a 4.09% dividend yield, depending on how one key uncertainty around future enterprise AI project budgets plays out.
That uncertainty is exactly why the analyst forecasts for Systena can help you see where Systena’s valuation and future project momentum might be decoupling.
WingArc1st (TSE:4432)
WingArc1st builds software that turns business documents and data into usable information, with its invoiceAgent AI OCR product directly tied to the AI theme by extracting data from invoices and forms. The Data Empowerment Business generated about ¥31.4b in sales, all in Japan, and the stock carries a market value of roughly ¥115.4b.
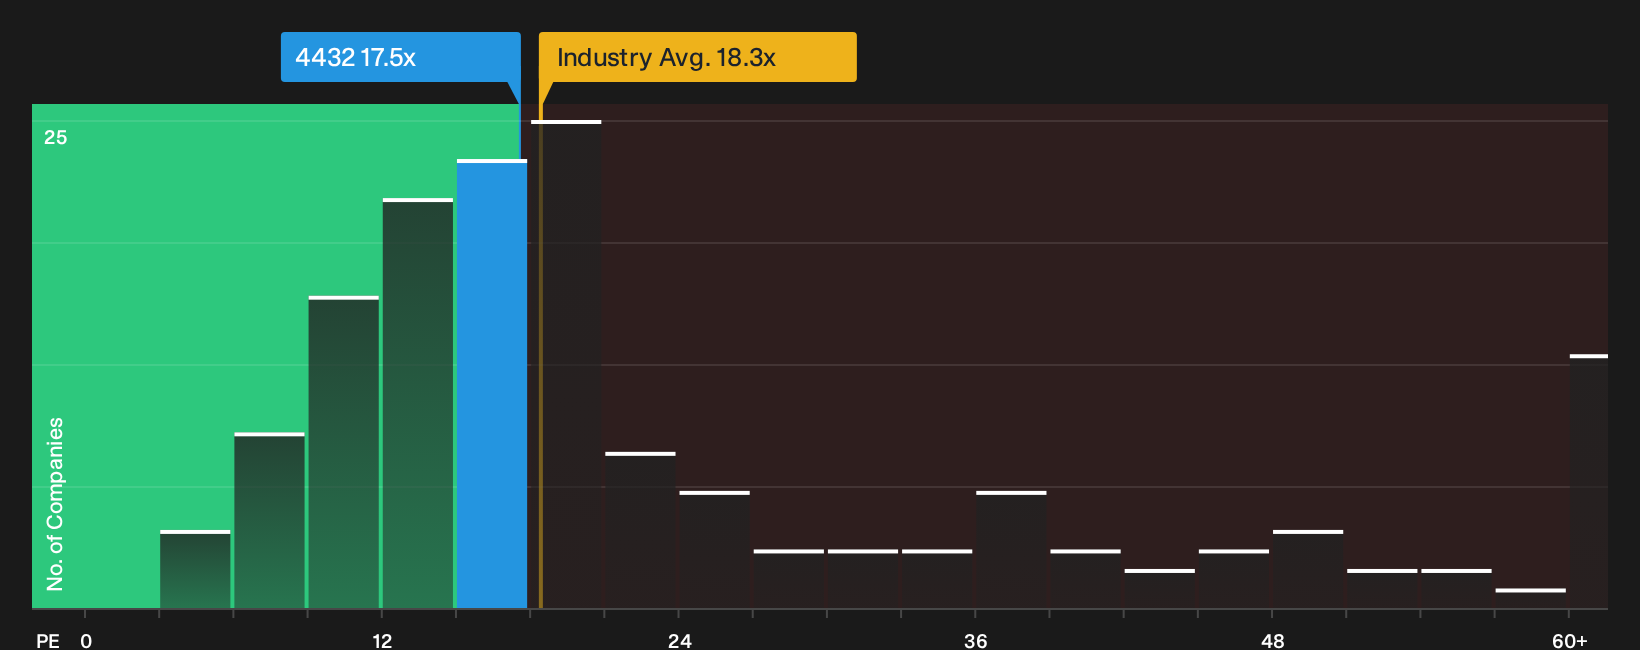
WingArc1st plugs into the AI story through invoiceAgent AI OCR and its links to SVF and Dr.Sum, which help customers automate document workflows and feed analytics. A discounted P/E against peers gives AI focused investors a reason to watch how one shift in enterprise demand for automated document processing filters through to margins and growth.
That valuation gap only starts the story, so run through the analysis report for WingArc1st to see whether WingArc1st’s pricing is masking a bigger AI monetisation shift.
Seeking Alternatives Before The Crowd?
Fresh opportunities do not wait. Breakout stories gain momentum, quiet winners stop flying under the radar, and stretched valuations risk dropping back. Scan these ideas while it matters and get in early.
- Spot resilient businesses aiming to protect capital while still pursuing upside by reviewing the 21 resilient stocks with low risk scores before the market fully prices in their strength.
- Identify potential cash generating AI leaders early by running through the curated 38 profitable AI stocks that aren't just burning cash while many investors are still focused on story stocks.
- Monitor income opportunities that might help cushion volatility and capture re-rating momentum with the hand picked 14 dividend fortresses before yields compress.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com