
Magnolia Oil And Gas (MGY) Stock May Be Below Fair Value On Earnings
Magnolia Oil & Gas has given long term holders a solid ride, with the stock returning 49.3% over the past 5 years, yet the recent pullback raises a sharper question about what you are paying for its earnings today. With the share price now around US$24.02 after some short term weakness, the key issue is how that tag lines up with the profits the business is generating.
- A 49.3% gain over 5 years puts real money on the line for holders. Any reassessment of the earnings power behind Magnolia Oil & Gas therefore matters directly to your potential upside and downside.
- The business model is tightly linked to how efficiently it can convert its oil and gas assets into steady profits. This can influence what multiple investors are willing to pay for each dollar of earnings.
- There is a second opinion on Magnolia Oil & Gas worth weighing. See what analysts think Magnolia Oil & Gas's shares could be worth.
For investors, the debate is whether Magnolia Oil & Gas' current share price is properly supported by the earnings it is producing today.
If you are weighing whether Magnolia Oil & Gas' current P/E feels fair after that 5 year return, you can stress test your thinking against a wider set of 29 high quality undervalued stocks
Is Magnolia Oil & Gas Still Cheap on Earnings?
The P/E ratio works well for Magnolia Oil & Gas because earnings are a clear output of how effectively its reserves and wells are run. On this yardstick, the stock trades at about 13.6x earnings, which is above the oil and gas industry average of roughly 12.7x and also higher than the peer group nearer 10.4x.
The tailored fair P/E that reflects Magnolia Oil & Gas' own mix of growth prospects, profitability, size and risk sits above where the shares change hands today. That puts the current 13.6x multiple at a discount to what this framework suggests could be justified, even though it already carries a premium to the broader sector and direct competitors. For a holder, the key question is whether the earnings profile you see as realistic lines up with that gap between market pricing and the fair P/E signal. Explore the numbers behind Magnolia Oil & Gas's P/E valuation.
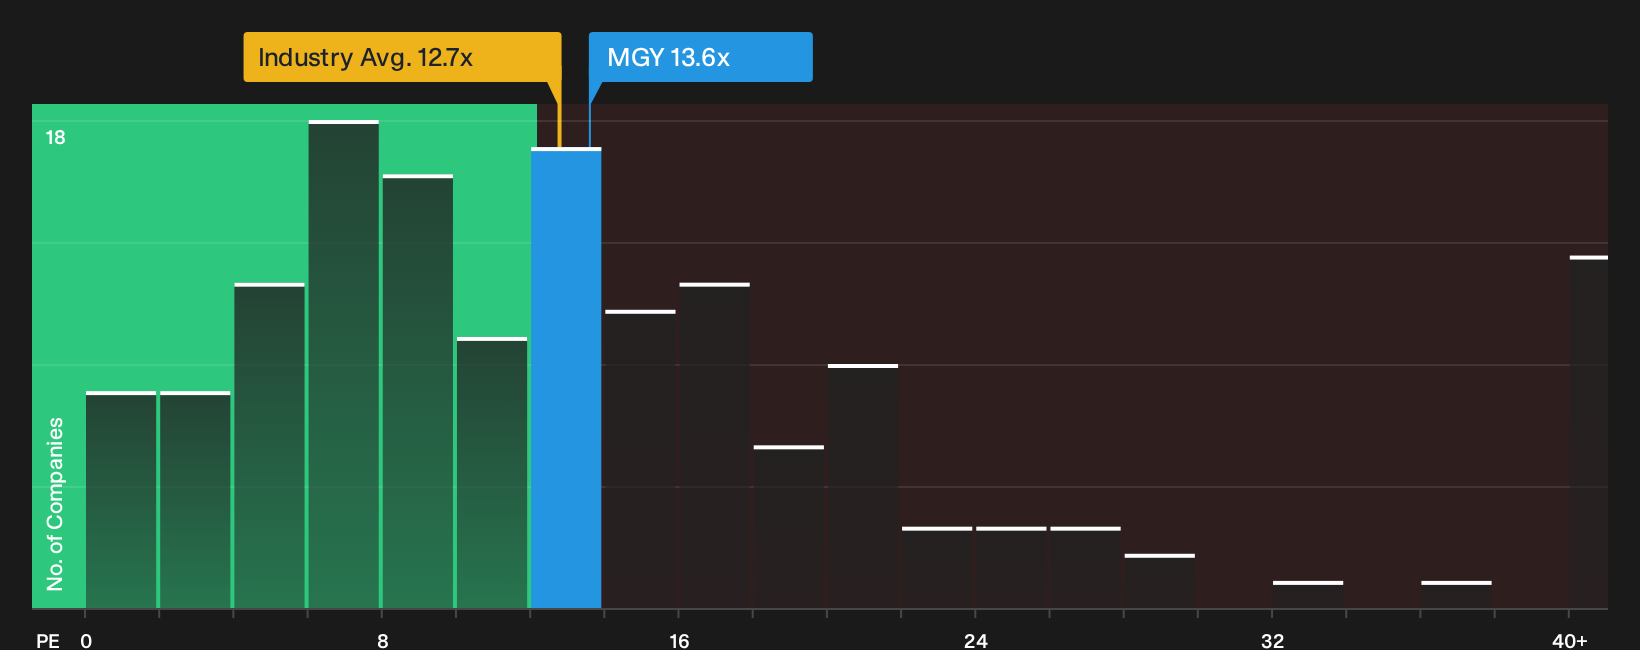
The Magnolia Oil & Gas Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Magnolia Oil & Gas pick up where the P/E puzzle leaves you. They turn that single valuation snapshot into a set of clear assumptions about future growth, margins and earnings that would need to hold for the stock to be worth meaningfully more or less than today's price. These Narratives sit on the Community page so you can see the future story that underpins the ratio and judge over time whether reality is tracking it.
One of the top community narratives on Magnolia Oil & Gas: 37% undervalued
"The current valuation implies Magnolia Oil & Gas shares do not fully reflect the larger oil-weighted production base and higher proved developed reserves…"
Discover why this Narrative puts Magnolia Oil & Gas at 37% undervalued.
One more Magnolia Oil & Gas check before you stop at the P/E
Price ratios tell you what Magnolia Oil & Gas costs today, but analyst projections show where professionals think the earnings story could be a few years from here. Explore where analysts expect Magnolia Oil & Gas to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com