
Novo Nordisk (NVO) Stock Still Looks Cheap On Earnings Today
Novo Nordisk has seen its share price retreat sharply in recent years, which puts fresh focus on whether today's valuation is still supported by its earnings power. With the stock pulling back even as the business pursues new therapies, the question now is how well the current price lines up with the profits investors are effectively paying for.
- The share price has fallen 54.4% over the past 3 years, which puts previous optimism about Novo Nordisk under the microscope and raises the stakes for any earnings based assessment.
- A positive opinion from the European regulator on once weekly Sogroya for children with idiopathic short stature may support expectations for longer term revenue and profit streams in Novo's treatment portfolio.
- The analysts covering Novo Nordisk have run their own numbers. See what analysts think Novo Nordisk's shares could be worth.
For investors, the debate is whether Novo Nordisk's recent share price level is properly aligned with what its current and expected earnings can justify.
If you are questioning whether Novo Nordisk still earns its current P/E, a focused screen of 29 high quality undervalued stocks can provide a clearer starting list for further research.
Is Novo Nordisk Still Cheap on Earnings?
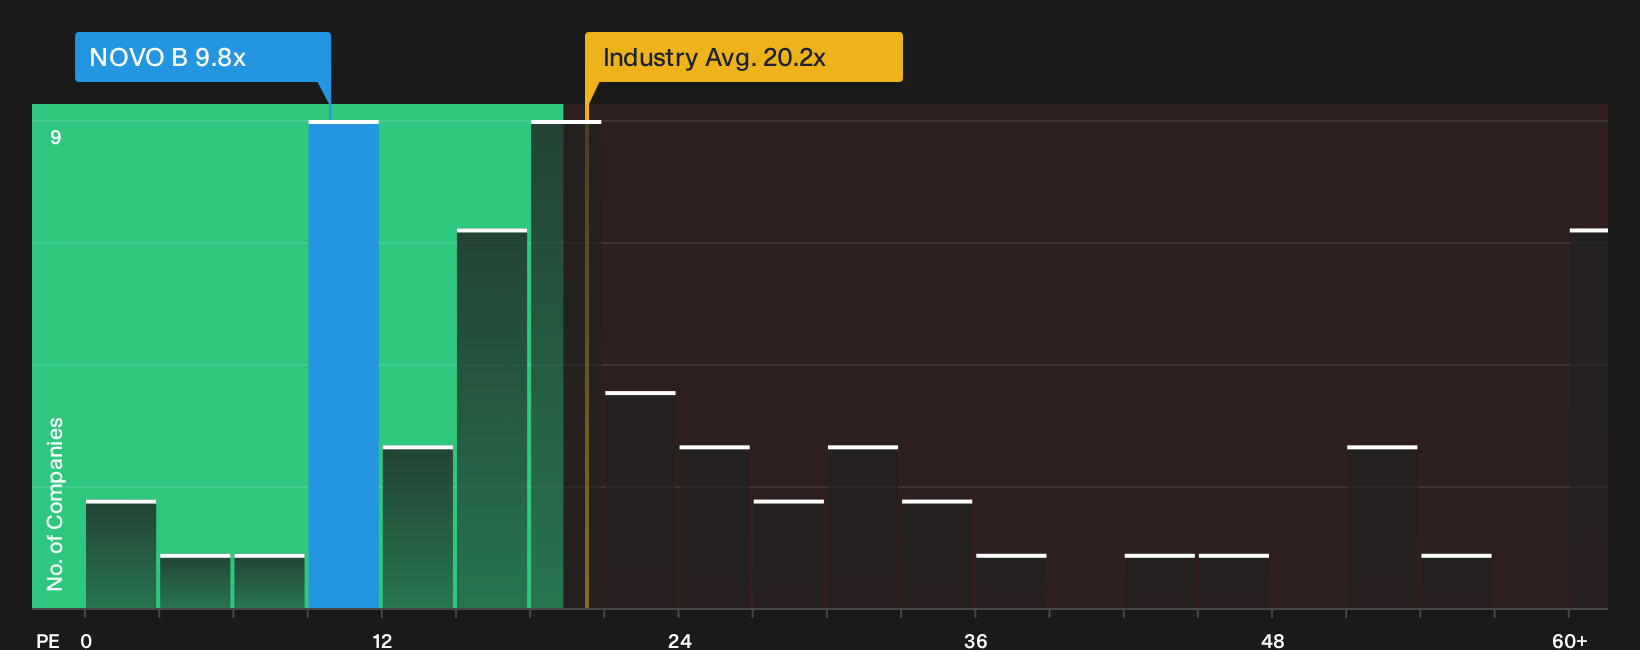
P/E works well for Novo Nordisk because earnings remain the main driver most investors watch for this stock. On that yardstick, Novo Nordisk trades on roughly 9.8x earnings, which is well below the Pharmaceuticals sector average of about 16.4x and also sits far under a peer group nearer 49.6x. For a business of this size, that gap signals that the market is applying a much lower earnings tag than it does to many competitors.
Because the fair multiple implied by the model is higher than the current 9.8x, Novo Nordisk screens as undervalued on this earnings lens. The fair yardstick here already bakes in factors like profitability profile, industry backdrop and risk, so the discount is not just a simple sector comparison. Despite the recent positive opinion for once weekly Sogroya in European children helping the broader story, the current P/E still leaves Novo Nordisk trading at a marked earnings discount that invites closer scrutiny from investors. Explore the numbers behind Novo Nordisk's P/E valuation.
The Novo Nordisk Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Novo Nordisk leaves off by spelling out what kind of future growth, profitability and earnings path would need to hold for the stock to be worth materially more or materially less than it is today, and they live on Simply Wall St's Community page. Each one presents Novo Nordisk's implied fair value as a specific thesis about the business that you can revisit over time and see how it holds up against new information.
One of the top community narratives on Novo Nordisk: 59% undervalued
"Management has narrowed 2025 guidance to 8–11% sales growth and 4–7% operating profit growth, explicitly citing intensifying competition and pricing pressure…"
Discover why this Narrative puts Novo Nordisk at 59% undervalued.
One more Novo Nordisk check that belongs beside the P/E work
Price and profits only tell part of the story, because the people setting Novo Nordisk's priorities and how they are rewarded can pull the business in very different directions. See who runs Novo Nordisk and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com