
Does Cardinal Health (CAH) Have Enough Earnings To Support Its Price?
Cardinal Health has had a powerful run over the past few years, which puts a spotlight on whether the current US$222.04 share price lines up with what its earnings can support. For anyone considering the stock today, the central issue is how that recent performance squares with the profits the business generates.
- Over the past 5 years the stock has returned about 383.8%, which makes the link between Cardinal Health’s earnings power and today’s valuation especially important for new buyers.
- The business relies on large scale distribution and tight cost control, so even small shifts in margins or working capital can influence how much of its accounting profit turns into cash that can support the current share price.
- There is a second opinion on Cardinal Health worth weighing. See what analysts think Cardinal Health's shares could be worth.
The stock's next move may depend on whether Cardinal Health's current earnings justify the price investors are being asked to pay today.
If you want a broader perspective on whether Cardinal Health's earnings justify its current valuation, compare its profile against companies in the solid balance sheet and fundamentals stocks screener (23 results).
Does Cardinal Health Look Fairly Valued on Earnings?
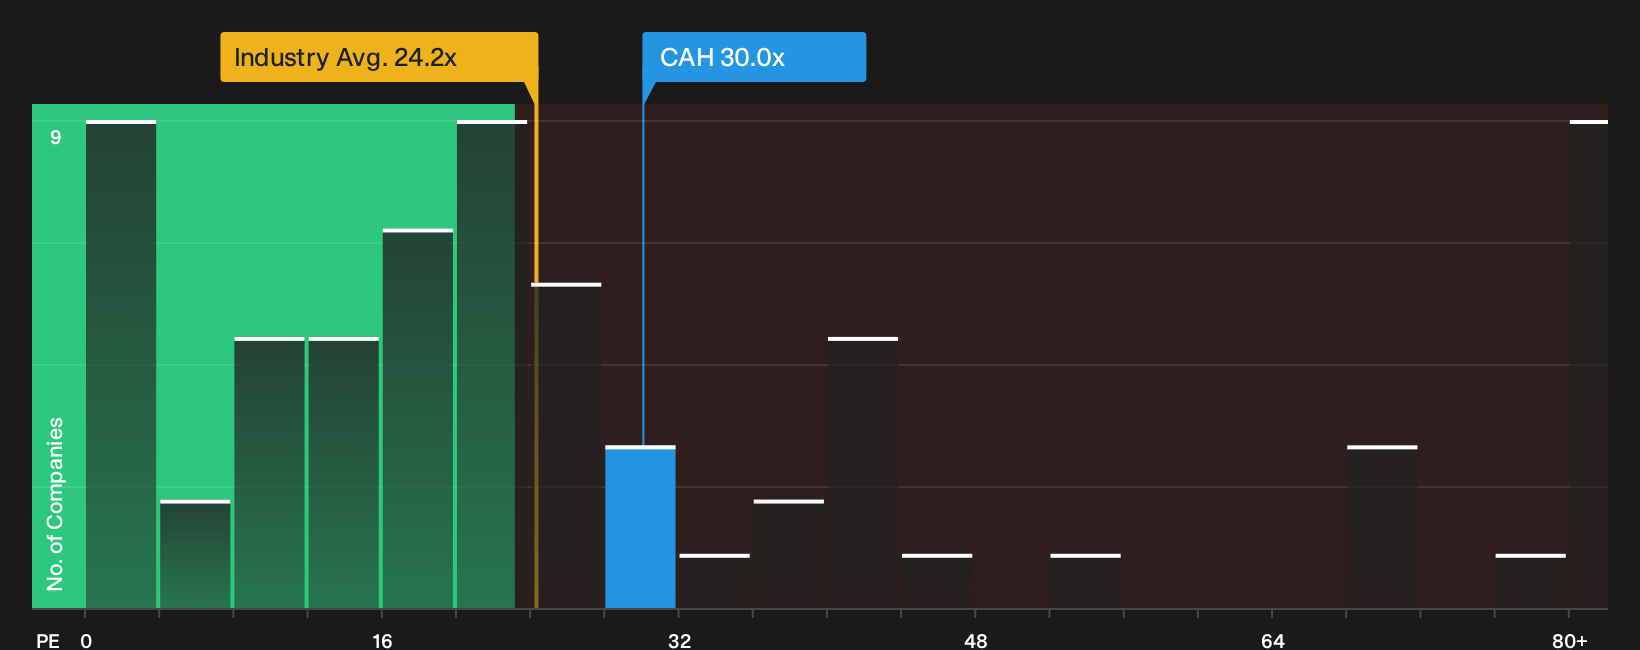
The P/E ratio suits Cardinal Health because earnings are a central driver for how investors view a large distributor with tight margins. On this measure, the stock trades on roughly 30.0x earnings. That compares with about 26.1x for its peer group and around 24.2x for the broader Healthcare sector, so you are paying a higher price per dollar of profit than many comparable businesses.
Against a tailored fair P/E that reflects Cardinal Health’s own mix of growth prospects, profitability profile, size and risk, the current multiple sits close to what that framework would suggest. For an investor, the key question is whether the quality and durability of those earnings justify paying near that implied level, or whether other factors such as cash generation, competitive position and balance sheet strength change the picture. Explore the numbers behind Cardinal Health's P/E valuation.
The Cardinal Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Cardinal Health pick up where this valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than its current price, and they sit on the company’s Community page. Rather than relying on a single P/E or model output, each narrative lays out the earnings assumptions behind its view of fair worth so you can line them up against actual results over time.
One of the top community narratives on Cardinal Health: 18% undervalued
"The current earnings power and cash generation implied by guidance and recent results suggest the share price does not fully reflect this mix shift toward specialty, services, and a repaired medical segment..."
Discover why this Narrative puts Cardinal Health at 18% undervalued.
For Cardinal Health, one unresolved issue still matters
Valuation only tells part of the story for Cardinal Health, because our broader checks have flagged specific areas of concern that could influence how investors view the risk side of the equation. Take a closer look at 3 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com