
PagSeguro (PAGS) Stock May Be A Bargain On Earnings Power
PagSeguro Digital has given investors a rough ride over the past few years, which puts a spotlight on what they are currently paying for its earnings. With the share price around US$9.40, the key issue is whether that level makes sense given how the business converts its payment volumes into profits today.
- The stock has fallen 80.3% over the past 5 years. This makes the current valuation hinge even more on how dependable its earnings power really is.
- As a payments and financial technology platform, PagSeguro’s ability to scale transaction volumes while managing credit risk and operating costs can shape how much of its revenue ultimately shows up as sustainable earnings.
- There is a second opinion on PagSeguro Digital worth weighing. See what analysts think PagSeguro Digital's shares could be worth.
The issue now is whether PagSeguro Digital’s current share price is properly aligned with what its earnings suggest the business is worth.
If you want a broader view of earnings-driven opportunities such as PagSeguro Digital before going further, use a focused screen built around 29 high quality undervalued stocks.
Does PagSeguro Digital Look Undervalued on Earnings?
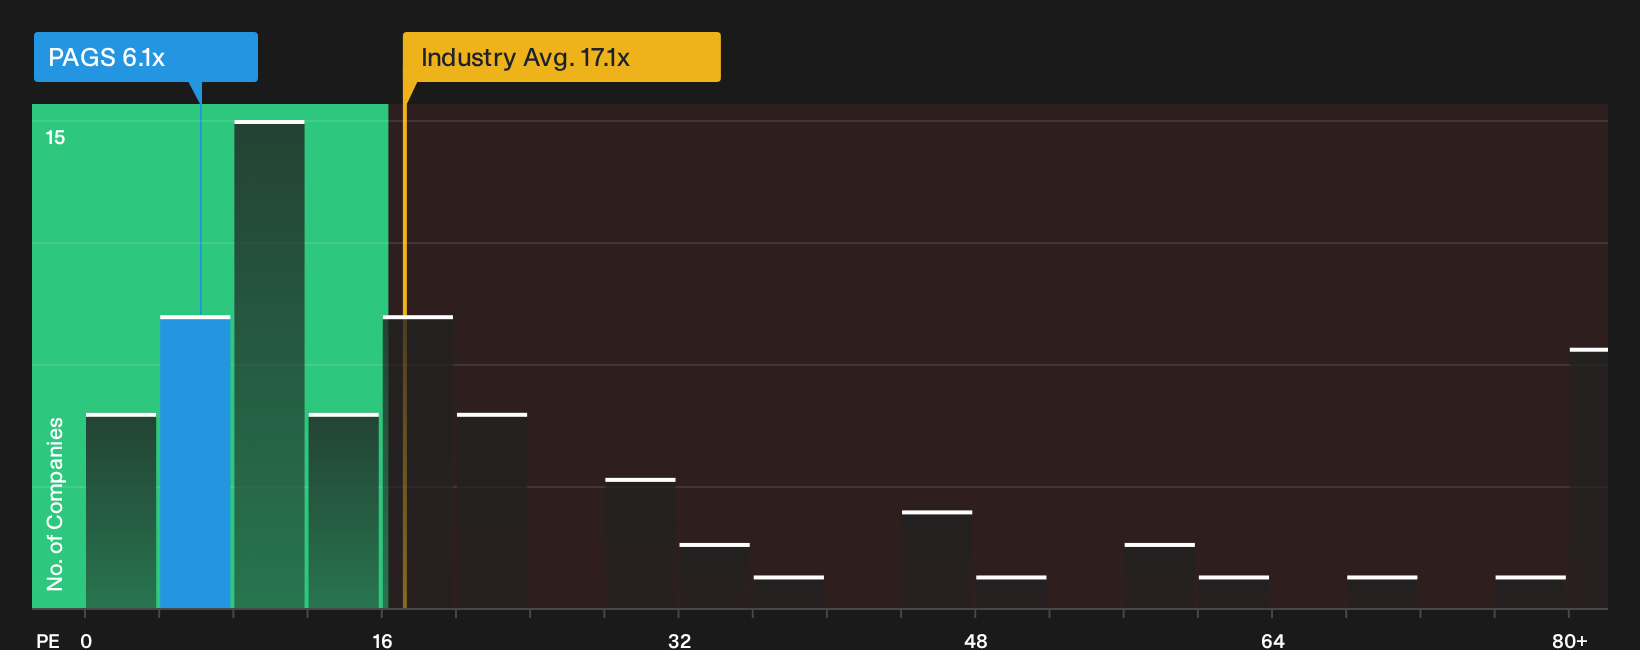
P/E works well for PagSeguro Digital because the business already generates earnings that give a clear anchor for what investors are paying. At the current valuation, the stock trades on a P/E of 6.1x, which is well below the diversified financial industry average of 17.1x and also below the broader peer group on about 19.3x. That is a big gap for a company that is already profitable, rather than one still trying to prove its business model.
The fair P/E level implied by PagSeguro Digital’s own fundamentals is higher than where the shares trade today. This points to the stock changing hands at a discounted earnings multiple rather than a premium one. For anyone weighing the risks in PagSeguro Digital against this lower starting P/E, the key question is whether current earnings are sturdy enough that a compressed multiple is offering value or simply reflecting caution. Explore the numbers behind PagSeguro Digital's P/E valuation.
The PagSeguro Digital Narrative: What Would Justify Today's Price?
PagSeguro Digital’s Simply Wall St Narratives pick up where the P/E puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than today’s quote. Instead of a single output from a ratio or model, these scenarios map the future that number relies on so you can watch how the actual business lines up over time, and they sit on the company’s Community page.
PagSeguro Digital splits opinion between investors who see a discounted bank in the making and those who focus on pressure from competition and regulation.
Bull case: 51% undervalued
"The single biggest lever is the credit portfolio, which sits at roughly R$5 billion today and management targets R$25 billion by 2029…"
Discover why this Narrative puts PagSeguro Digital at 51% undervalued.
Bear case: 11% overvalued
"Intensifying digital competition from global fintechs and big tech platforms such as Apple, Google, and MercadoLibre is expected to erode PagSeguro's ability to acquire and retain customers…"
Explore why this Narrative puts PagSeguro Digital at 11% overvalued.
One more angle on PagSeguro Digital that could change how you see it
Everything so far has focused on what PagSeguro Digital looks like today, but professional analysts have already mapped out where they expect the earnings story to be a few years from now. This gives you a different reference point for judging the current multiple. Explore where analysts expect PagSeguro Digital to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com