
Undiscovered Gems In Global Markets Featuring Three Promising Stocks
As global markets navigate a landscape marked by mixed performances in major indices and fluctuating oil prices due to geopolitical tensions, small-cap stocks continue to face unique challenges and opportunities. In this environment, identifying undiscovered gems requires a keen eye for companies with robust fundamentals and the potential to thrive amidst economic shifts.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| C-Rad | NA | 13.57% | 13.83% | ★★★★★★ |
| GROUPE SFPI | 18.02% | 4.25% | -29.76% | ★★★★★★ |
| Fourth Milling | NA | 12.93% | 16.76% | ★★★★★☆ |
| Alexandria Group Oyj | 5.79% | 6.84% | 8.17% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Aqualis | 33.30% | 22.28% | -18.13% | ★★★☆☆☆ |
Underneath we present a selection of stocks filtered out by our screen.
CW Enerji Mühendislik Ticaret ve Sanayi Anonim Sirketi (IBSE:CWENE)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: CW Enerji Mühendislik Ticaret ve Sanayi Anonim Sirketi is engaged in the photovoltaic power generation sector in Turkey, with a market capitalization of TRY26.53 billion.
Operations: CW Enerji generates revenue primarily from its Cw Energy segment, contributing TRY18.44 billion, and CW Solar Cell segment, adding TRY4.25 billion. The company's net profit margin is influenced by various adjustments and corrections, including a significant elimination correction of -TRY7.22 billion.
CW Enerji, a notable player in the electrical industry, has shown impressive earnings growth of 340.1% over the past year, outpacing industry norms. Despite trading at a substantial 88.1% below estimated fair value, its interest coverage is concerning with EBIT only covering interest payments 1.6 times. The company's debt to equity ratio increased from 32.5% to 36.5% over five years but remains satisfactory at a net debt to equity ratio of 33.8%. Recent earnings reports highlight robust performance with Q2 sales reaching TRY 4,495 million and net income climbing to TRY 500 million from TRY 284 million last year.

San Miguel Food and Beverage (PSE:FB)
Simply Wall St Value Rating: ★★★★★★
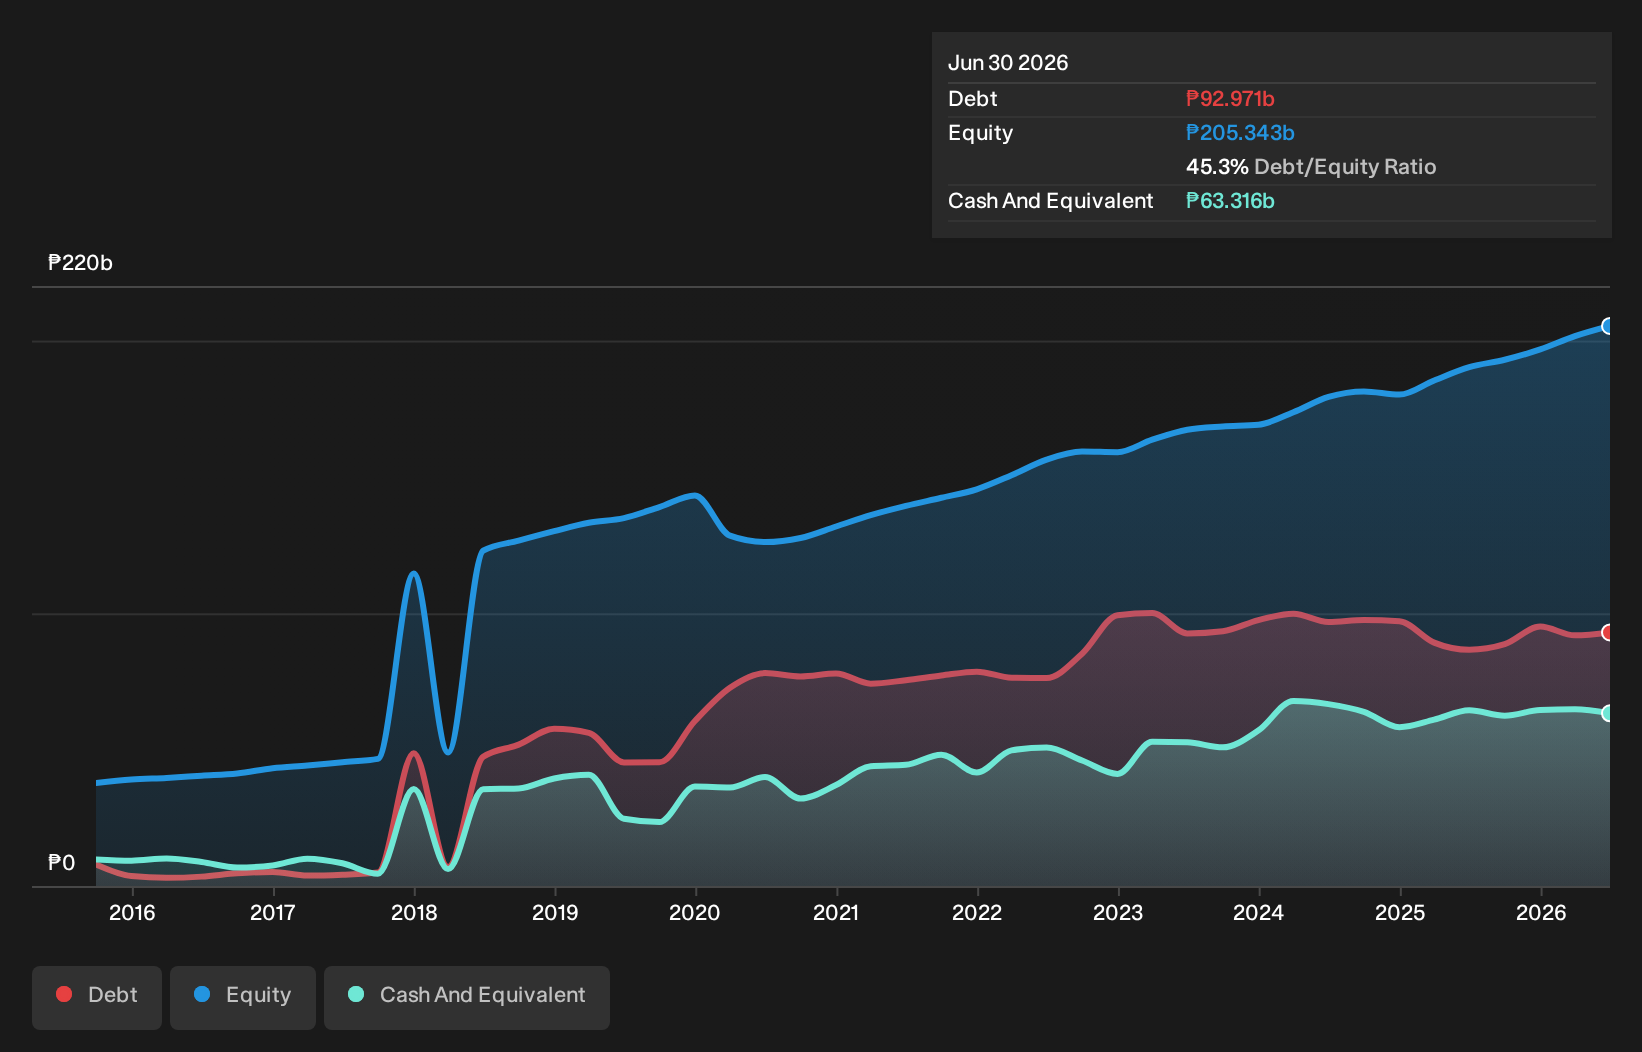
Overview: San Miguel Food and Beverage, Inc. is a Philippine company involved in the manufacturing and marketing of processed meat products, with a market capitalization of approximately ₱254.10 billion.
Operations: San Miguel Food and Beverage generates revenue primarily from its food segment, contributing ₱201.17 billion, followed by beer and non-alcoholic beverages at ₱153.95 billion, and spirits at ₱67.00 billion.
San Miguel Food and Beverage, a company with a market presence in the food and beverage sector, reported net income of PHP 6.77 billion for Q2 2026, slightly down from PHP 7.44 billion the previous year. The company seems to have faced challenges as sales for the first half of 2026 were PHP 155.92 billion compared to PHP 201.2 billion a year ago, yet it still managed to declare both regular and special dividends totaling PHP 1.27 per share in August. With an EBIT coverage ratio of over 121 times its interest payments, San Miguel's financial health appears robust despite recent earnings pressures.
KeePer Technical Laboratory (TSE:6036)
Simply Wall St Value Rating: ★★★★★★
Overview: KeePer Technical Laboratory Co., Ltd. is a Japanese company that specializes in the development, manufacturing, and sale of car coatings, car washing chemicals and equipment with a market capitalization of ¥97.43 billion.
Operations: KeePer Technical Laboratory generates revenue primarily through the sale of car coatings and car washing chemicals and equipment in Japan. The company's market capitalization stands at ¥97.43 billion.
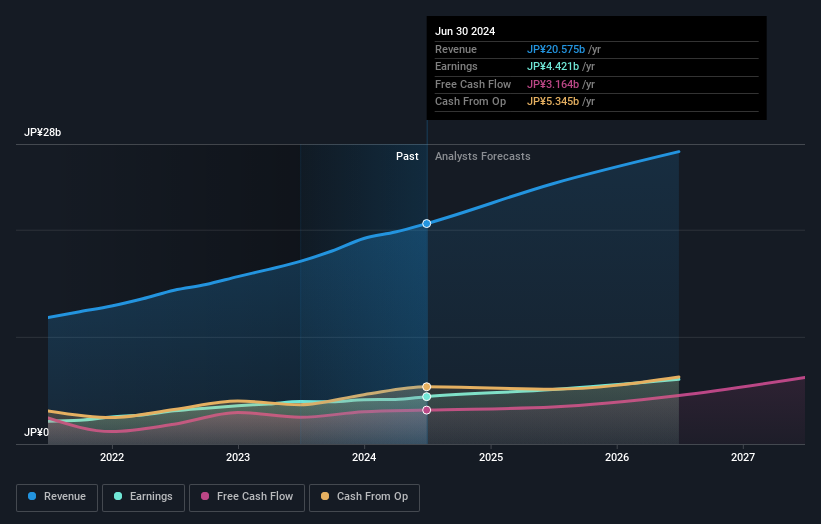
KeePer Technical Laboratory, a small cap player in the chemicals industry, has shown substantial growth with earnings up by 101% over the past year, outpacing the industry's 24.9%. The company is trading at a significant discount of 70.6% below its estimated fair value and has reduced its debt to equity ratio from 11.9% to 3.8% over five years, indicating improved financial health. Recent announcements include a dividend increase to JPY 100 per share for fiscal year ending June 2027 and projected revenue growth of JPY 29 billion, reflecting robust operational performance and strategic financial management under new leadership.
Key Takeaways
- Investigate our full lineup of 167 Global Undiscovered Gems With Strong Fundamentals right here.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com