
Amgen (AMGN) Following Its Sjögren's Trial Win Through A Valuation Lens
Amgen (AMGN) has become a focal point for autoimmune investors after releasing Phase 3 data showing its experimental drug dazodalibep met the primary endpoint in moderate-to-severe systemic Sjögren's disease, a condition for which no approved treatments currently exist.
That autoimmune readout landed on a stock that has already seen strong interest this year, with a year to date share price return of 25.21% and a 1 year total shareholder return of 47.00%. This points to firm positive momentum rather than a short term pop.
Scan how Amgen's autoimmune breakthrough compares to other potential movers in the sector with a curated set of 37 healthcare AI stocks before the next wave of clinical catalysts hits.
Amgen now trades above the average analyst target while screens still flag a sizeable intrinsic discount. After this autoimmune surge, is the caution embedded in that gap sensible or overly harsh on the pipeline?
Most Popular Narrative: 14% Overvalued
Amgen closed at $410.24 while the most followed narrative on Simply Wall St anchors fair value at $359.98. This implies investors are paying a premium that the author argues is not backed by the fundamentals.
The "Amgen 2027 Bull Case" relies on a classic top-line fallacy: assuming that macro obesity market growth and FDA's CNPV (Commissioner’s National Priority Voucher) tailwinds will automatically trigger a re-rating.
Here is the cold, data-driven reality:
See why 6 investors see Amgen as 14% overvalued.
Result: Fair Value of $359.98 (OVERVALUED)
Still, Amgen bears face real risk if autoimmune assets like dazodalibep gain traction or if obesity pipeline execution exceeds current cautious expectations.
Find out about the key risks to this Amgen narrative.
Another View: Amgen Through A Cash Flow Lens
The crowd narrative says Amgen is 14% overvalued at $410.24 versus a $359.98 fair value. Our SWS DCF model points in the opposite direction. It estimates future cash flow value at $669.25, which is 38.7% above the current price and frames AMGN as undervalued.
Two valuation tools telling different stories forces a harder question. Is the community leaning too much on near term obesity and autoimmune worries, or is the cash flow model giving too much credit to a complex pipeline and debt heavy balance sheet?
Look into how the SWS DCF model arrives at its fair value.
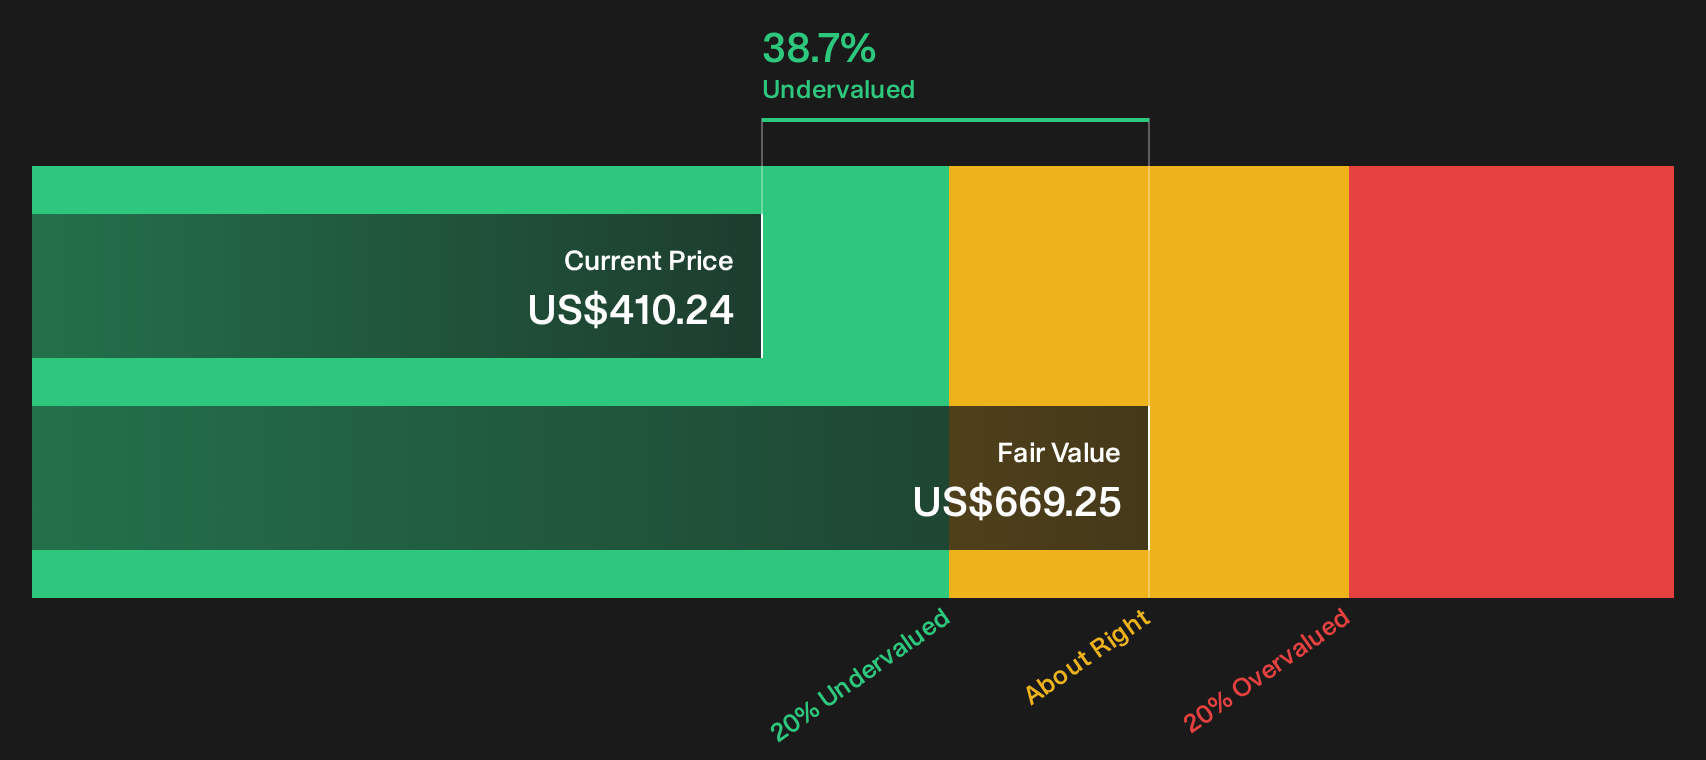
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Amgen for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Amgen is clearly divided. This is exactly why now may be a good time to move quickly, review the numbers yourself, and weigh both sides of the autoimmune and obesity story using the 4 key rewards and 1 important warning sign.
Looking for more Amgen-sized opportunities?
If Amgen has sharpened your focus, do not stop there. Use the Simply Wall St Screener to surface fresh ideas before the next wave of catalysts arrives.
- Target resilience first and filter for sturdier balance sheets using the list of solid balance sheet and fundamentals (23 results) that many investors overlook until stress hits.
- Hunt for value where others hesitate and scan the 29 high quality undervalued stocks that may combine quality fundamentals with pricing that still leaves room for upside.
- Spot stability with a twist and review the 7 dividend fortresses that could complement growth names like Amgen in a more balanced portfolio mix.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com