
Welltower (WELL) Expands Its Growth Story As Fair Value Sits Higher
Welltower (WELL) drew fresh attention after recent trading left the share price at US$230.39. This has focused investors on how its senior housing and outpatient medical portfolio aligns with longer term income and growth objectives.
Recent trading has cooled slightly, with the share price down 3.69% over the past month. Even so, Welltower still carries strong momentum after a 23.24% year to date share price return and a 3 year total shareholder return above 200%, which signals that investors have been steadily reassessing both its growth potential and risk profile.
Extend your search beyond Welltower and compare this run to a hand picked 30 resilient stocks with low risk scores that also focuses on resilience and capital preservation.
After a run like this followed by a modest pullback, the real call with Welltower is simple. Is today’s level acceptable, or does it make more sense to wait and hope for a cheaper entry based on valuation?
Most Popular Narrative: 12% Undervalued
On the most followed view, Welltower’s fair value sits at $262.23 per share, above the recent $230.39 close. This puts the focus squarely on what would need to go right operationally to justify that gap.
Welltower has launched a private fund management business and advanced its Welltower Business System, which is expected to enhance operational efficiencies and drive future revenue growth. Significant acquisition activity, including the Amica Senior Living acquisition, is anticipated to provide value through acquisition at a discount and drive revenue growth.
See why 29 investors see Welltower as 12% undervalued.
Result: Fair Value of $262.23 (UNDERVALUED)
Still, the bullish case for Welltower could be disrupted if higher inflation or interest costs put pressure on occupancy and reduce the net margins analysts are assuming.
Find out about the key risks to this Welltower narrative.
Another View On Welltower’s Valuation
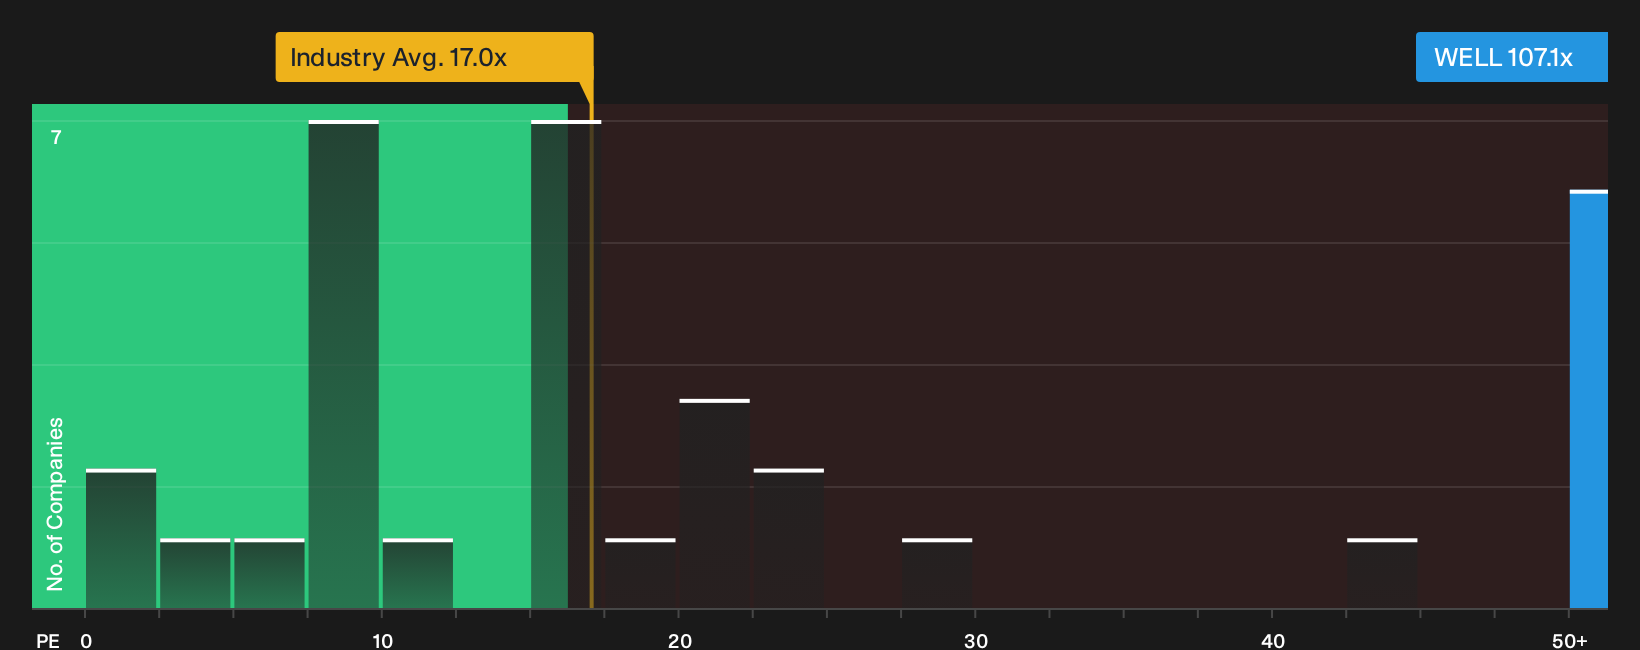
That 12% “undervalued” narrative leans heavily on future earnings forecasts. A simpler lens looks at what investors already pay for Welltower today. The current P/E of 107.1x is higher than peers at 85.9x and far above the sector’s 17.2x fair ratio, which points to meaningful valuation risk if expectations cool.
For a closer look at how these earnings multiples line up with fundamentals, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Welltower’s valuation and expectations make this a good moment to move quickly, review the underlying data, and decide where you stand. To weigh both sides of the argument in one place, start with the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Welltower?
If you like the Welltower story but want a broader watchlist, use the Simply Wall St Screener to surface fresh opportunities before they move without you.
- Target steadier compounding by scanning for companies with resilient finances using the list of solid balance sheet and fundamentals (23 results).
- Hunt for better entry points by checking a curated 29 high quality undervalued stocks that combines quality fundamentals with pricing that still looks reasonable.
- Strengthen your income stream by reviewing a focused 7 dividend fortresses that offers higher yields with supporting balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com