
Commerzbank (XTRA:CBK) Following UniCredit Interest With A Fully Valued Narrative
UniCredit CEO Andrea Orcel signaled continued engagement with Commerzbank (XTRA:CBK) shareholders, putting fresh attention on the German lender and its potential direction as talks with investors continue.
Commerzbank’s recent 1-day share price return declined 0.79% and the 7-day share price return fell 2.24%. However, the 30-day and 90-day share price returns of 6.43% and 11.08% point to momentum that aligns with increased investor focus following conference appearances in New York and Munich and the ongoing UniCredit engagement. The 1-year total shareholder return of 37.58% and very large 3-year and 5-year total shareholder returns around 4x and 7x signal that longer term holders have already seen substantial value creation.
Spot under-the-radar banking peers showing similar catalysts by scanning our hand-picked list of solid balance sheet and fundamentals (198 results).Bulls argue Commerzbank’s strong multi year shareholder gains and current UniCredit interest reflect a franchise still trading below its worth. Bears see recent price strength as enough. Which side do the valuation markers support next?
Most Popular Narrative: 2% Overvalued
Commerzbank’s most widely followed narrative points to a fair value of €40.68, slightly below the last close at €41.52. This puts current pricing just above that fair value anchor while UniCredit’s interest keeps expectations elevated.
Accelerating digital capabilities such as enhancements to Commerzbank's trading platform, the rollout of AI-driven solutions, and robust fintech adoption are positioning the bank to lower operating costs, expand fee-based revenues, and attract younger, digital-first customers. These developments support margin and revenue growth over the coming years.
See why 36 investors see Commerzbank as 2% overvalued.
Result: Fair Value of €40.68 (OVERVALUED)
Still, the Commerzbank narrative can unravel quickly if digital projects stall or if tougher regulation eats into profitability faster than analysts currently assume in their models.
Find out about the key risks to this Commerzbank narrative.
Another View on Commerzbank’s Value
Analysts see Commerzbank as about 2% overvalued at €41.52 versus a €40.68 fair value, yet the SWS DCF model points to a very different picture. On that framework, the shares trade at roughly a 52% discount to an estimated future cash flow value of €86.31, which suggests a much more optimistic outcome.
Both yardsticks use reasonable assumptions, but they highlight very different ideas about how much of Commerzbank’s future cash generation is already reflected in today’s price. Which set of expectations do you think is closer to how this story actually plays out?
Look into how the SWS DCF model arrives at its fair value.
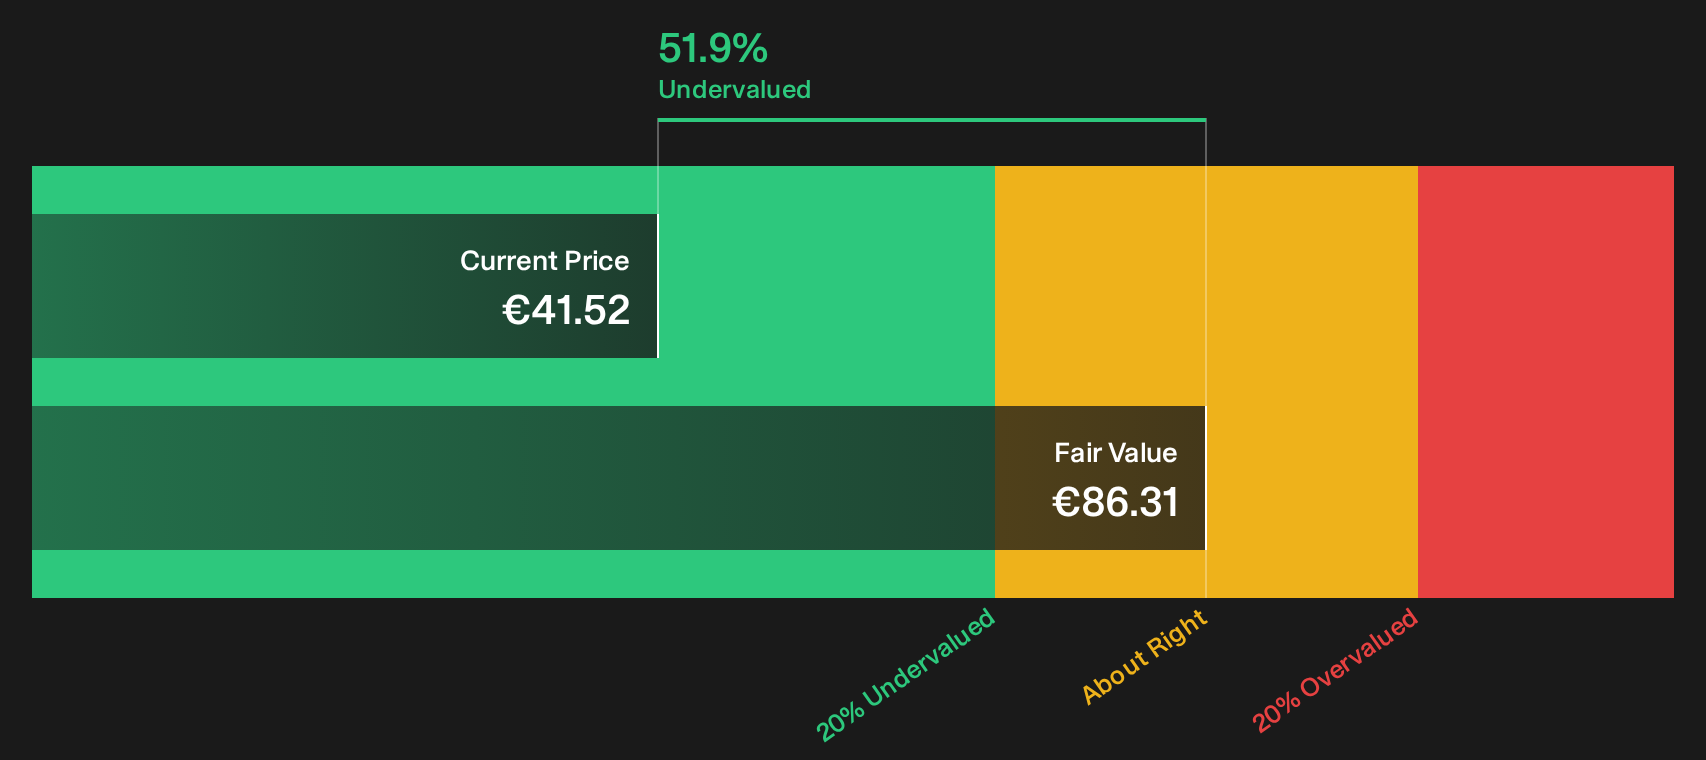
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Commerzbank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 171 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Commerzbank’s price and fair value often spark strong opinions. Move quickly, test the numbers yourself, weigh both the risks and the upside, then ground your stance in the 3 key rewards and 2 important warning signs.
Looking for more Commerzbank sized investment ideas?
Do not stop your research at Commerzbank alone. Looking more broadly across banks and other sectors can help sharpen your portfolio and keep your ideas pipeline fresh.
Use the Simply Wall Street Screener to uncover three different angles that could complement or contrast your view here.
- Target strong cash generators by reviewing a 171 high quality undervalued stocks list built around quality, value and balance sheet support.
- Prioritise resilience and aim to sleep better at night by scanning a 229 resilient stocks with low risk scores that filters for robust financial health and lower risk profiles.
- Look for potential future leaders early through a 619 high quality undiscovered gems focused on underfollowed businesses with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com