
PayPal (PYPL) Stock May Be Undervalued After Stablecoin Platform Launch
PayPal Holdings has seen its share price struggle in recent years, and the question now is whether what you pay today lines up with the earnings the business is producing. With fresh product moves in stablecoins and a major internal overhaul underway, the stock invites a closer look at how its current price relates to the profits behind it.
- Over the past 5 years, PayPal Holdings’ share price has fallen 79.6%, which puts the current earnings profile under closer scrutiny for anyone still trying to frame what the business is worth.
- The launch of the PYUSDX platform and the shift toward more consumer-focused services can influence how investors think about future profit streams, from potential fee income on stablecoin activity to the impact of cost savings and buybacks on earnings per share.
- The analysts covering PayPal Holdings have run their own numbers. See what analysts think PayPal Holdings's shares could be worth.
The stock's next move may depend on whether PayPal Holdings' current earnings are strong enough to justify the price set by the market today.
If you want to weigh the earnings outlook for PayPal Holdings alongside other opportunities, run the same test across 29 high quality undervalued stocks.
Is PayPal Holdings Still Cheap on Earnings?
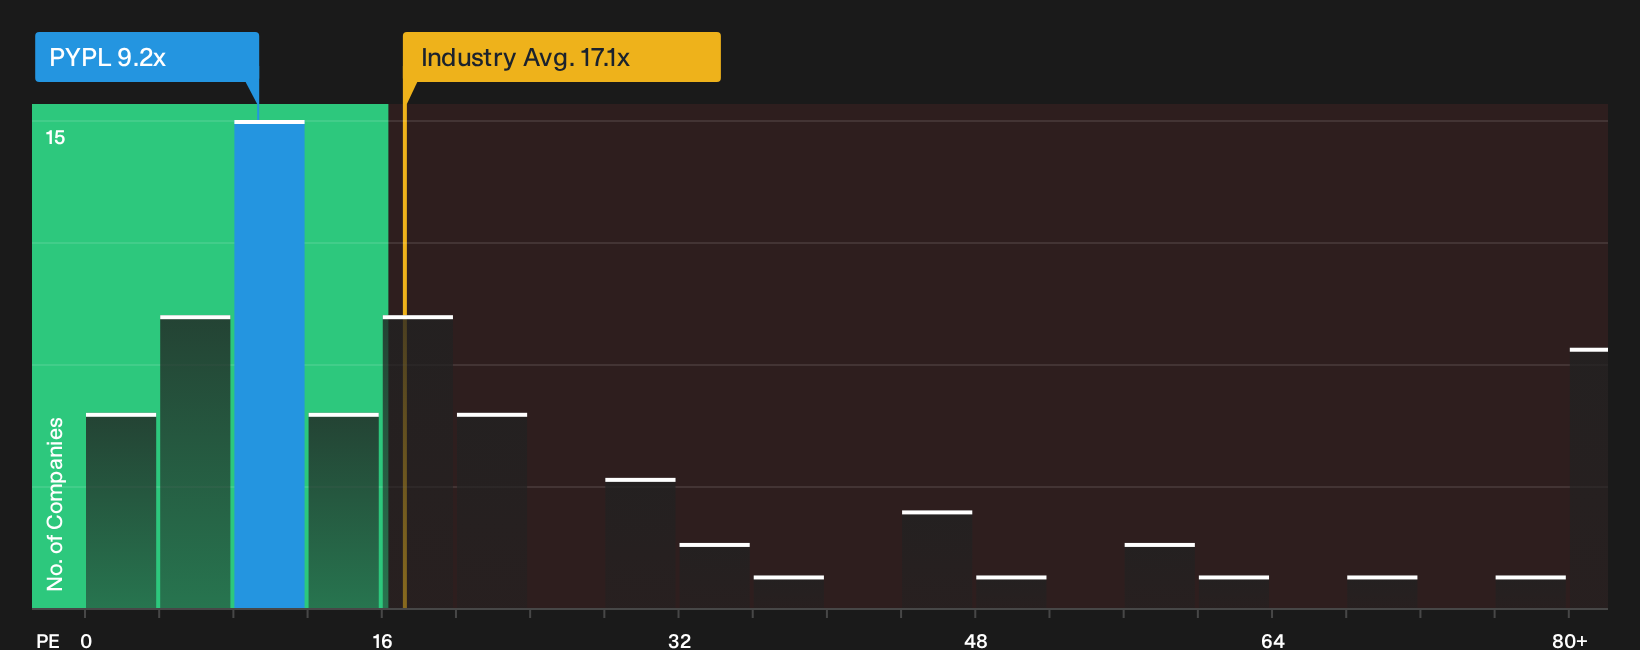
The P/E ratio fits PayPal Holdings because earnings are a key focus for investors watching the turnaround story. On current numbers, the stock trades on a P/E of 9.2x, which is well below the diversified financials industry average of 17.1x and far under the peer group around 52.0x. That gap indicates the market is pricing PayPal as materially cheaper on today’s earnings than both its sector and closer comparables.
Because the preferred model points to a higher P/E as fair given PayPal Holdings’ profile, the current 9.2x level sits below what the company specific fundamentals might suggest. Despite the launch of the PYUSDX stablecoin platform and the push into more consumer facing products, the stock still trades at a discount on this earnings multiple relative to peers. To decide whether that discount is an opportunity or a warning, you need to weigh the durability of those earnings and the execution risks around the reorganisation and cost cuts. Explore the numbers behind PayPal Holdings's P/E valuation.
The PayPal Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for PayPal Holdings link the P/E puzzle you have just seen to specific assumptions about future growth, margins and earnings. They sit on the Community page so you can see which story the market seems to be leaning toward at any given time.
Each scenario ties a fair value estimate to a clear set of potential catalysts and downside risks. This lets you track over time whether PayPal Holdings' actual progress lines up with that version of events or starts to drift toward a different path.
Community views on PayPal Holdings split sharply between an asset light cash generator and a business facing heavy long term competitive and regulatory pressure.
Bull case: 36% undervalued
"By remaining a fintech, PayPal retains the flexibility to return that excess capital to you, the shareholder, through its aggressive buyback program..."
Discover why this Narrative puts PayPal Holdings at 36% undervalued.
Bear case: 65% overvalued
"The rise of direct account to account payments and blockchain technologies is enabling merchants and consumers to bypass traditional payment processors altogether..."
Explore why this Narrative puts PayPal Holdings at 65% overvalued.
For PayPal Holdings, price is only one piece of the decision
Before you lean too hard on the P/E story, it helps to know that Simply Wall St’s broader checks on PayPal Holdings have raised specific concerns that merit a closer look. Take a closer look at 1 major warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com