
Why Arista Networks (ANET) Is Back In The Spotlight
Recent optimism around Arista Networks (ANET) has been driven by higher earnings and revenue forecasts tied to growing AI data center demand, after the stock closed at US$205 with a 2.81% gain.
That optimism has come on top of strong momentum, with Arista Networks posting a 90 day share price return of 26.86% and a year to date share price gain of 53.59%, alongside a 1 year total shareholder return of 42.40% that includes reinvested returns.
Scan how Arista Networks fits into the broader AI buildout by comparing it with a curated list of 86 AI infrastructure stocks powering next generation data centers worldwide.
After such a sharp run and upbeat AI expectations baked into Arista Networks, the real test now is simple. Is meaningful upside still ahead, or has most of the opportunity already played out in the current price?
Most Popular Narrative: 15% Undervalued
Against Arista Networks' last close at $205.19, the most followed narrative pegs fair value at about $241.04. This frames the current AI enthusiasm as still leaving room according to that model rather than fully pricing it in.
The renewed investment cycle in cloud and AI infrastructure now includes Arista Networks’ higher 2026 revenue outlook of about US$12.6b and specific goals for at least US$3.5b of AI fabrics revenue. Together with a maintained 62% to 64% gross margin range and a higher 48% to 49% operating margin target, this may support stronger earnings power.
See why 301 investors see Arista Networks as 15% undervalued.
Result: Fair Value of $241.04 (UNDERVALUED)
Still, the Arista Networks story can crack if hyperscaler spending softens or if large multiyear chip commitments face slower than expected AI networking demand.
Find out about the key risks to this Arista Networks narrative.
Another View: Arista Networks Through The Earnings Lens
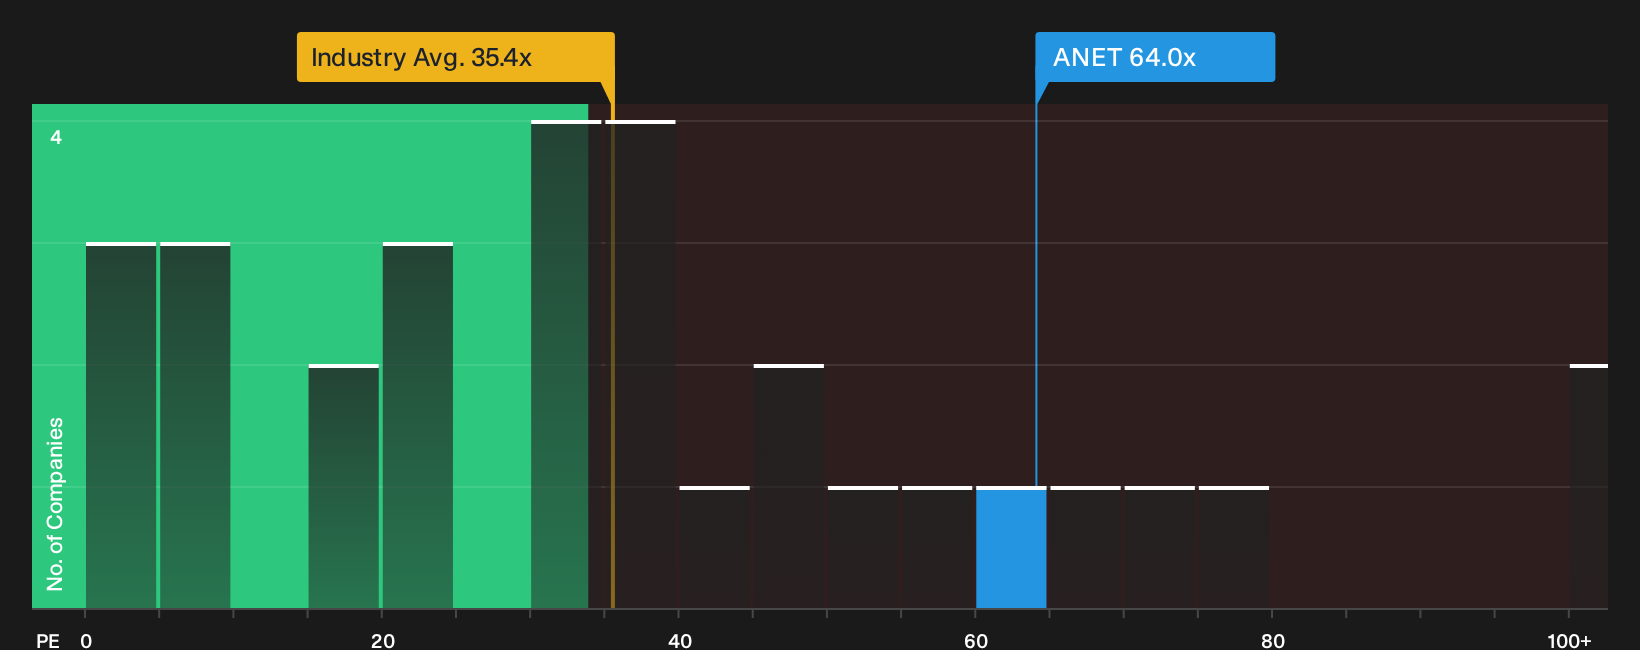
The first narrative painted Arista Networks as about 15% undervalued, yet the current P/E of 64x tells a tougher story. That multiple sits well above the US Communications sector at 35.4x and the fair ratio of 41.2x, which points to meaningful valuation risk if enthusiasm cools.
In practice, paying a P/E that far above peers and the fair ratio means you are leaning heavily on the AI buildout, margin targets and long term forecasts playing out close to plan. The question is simple: How comfortable are you paying that kind of premium when expectations already run this high?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Arista Networks so far. If you want to move quickly and build your own view from the ground up, start by weighing its 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Arista Networks?
Arista Networks gives you one side of the AI infrastructure story. Round out your watchlist by scanning for other opportunities that match your risk and return preferences.
- Spot potential upside early by reviewing a 16 high quality undiscovered gems that pair strong fundamentals with limited market attention.
- Strengthen your portfolio’s resilience by focusing on a list of solid balance sheet and fundamentals (23 results) that can better handle tougher conditions.
- Target reliable income potential by assessing 7 dividend fortresses offering higher yields supported by fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com