
Fortrea (FTRE) Stock Looks Reasonable Following Its 118% One Year Run
Fortrea Holdings has delivered a sharp share price swing over the past year, which naturally raises a question for anyone looking at the stock today. Are the cash flows the business can generate enough to support the current market value implied by that move?
- The stock has returned 118.0% over the past year, so anyone considering Fortrea Holdings now is effectively asking whether that jump is backed by the cash the business can produce.
- The company’s role as a contract research and services provider means growth plans, pricing power and capital intensity all feed directly into the timing and durability of its future cash flows.
- What if you looked at Fortrea Holdings through its sales instead? See what Fortrea Holdings's 0.7x P/S says about the price.
The issue now is whether Fortrea Holdings’ recent share price level at US$20.43 is in line with what its cash flows justify based on a Discounted Cash Flow (DCF) view.
If you want a broader reference point for Fortrea Holdings and its cash flow story, compare it with companies in the 29 high quality undervalued stocks.
Is Fortrea Holdings a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) approach here looks at the cash Fortrea Holdings is expected to generate for shareholders over time. The model starts from last twelve month free cash flow of about $200.8m and then projects a steady build in annual cash generation rather than a sharp jump or collapse.
Analyst projections and later trend estimates both point to growing free cash flow through the next decade, with figures for the late 2020s and early 2030s still sitting in the low to mid hundreds of millions of dollars. On this set of assumptions, the DCF outcome implies an intrinsic worth that sits substantially above the current share price of $20.43, suggesting the market is asking you to pay less than the modelled cash flows might justify. Find out what Fortrea Holdings could be worth using our Discounted Cash Flow (DCF) estimate.
The Fortrea Holdings Narrative: What Would Justify Today's Price?
Narratives for Fortrea Holdings pick up where the valuation puzzle leaves off and describe which paths for growth, margins and earnings would need to occur for the stock to be worth materially more or less than today’s price. Each scenario ties a fair value to a specific mix of possible catalysts and risks, which allows you to track over time which version of Fortrea Holdings' story seems closest to reality on Simply Wall St’s Community page.
Community views on Fortrea Holdings split between those who see more upside in the current setup and those who think expectations already run too hot.
Bull case: roughly fairly valued
"Post-spin, the company has executed significant cost optimization initiatives, achieving over $50 million in net savings year-to-date and targeting $90 to $100 million for the year…"
Discover why this Narrative puts Fortrea Holdings at roughly fairly valued.
Bear case: 57% overvalued
"Heavy reliance on a concentrated group of large customers, where the top 10 clients account for 59 percent of revenue and the largest single customer represents over 13 percent…"
Explore why this Narrative puts Fortrea Holdings at 57% overvalued.
One more Fortrea Holdings check that could change the story
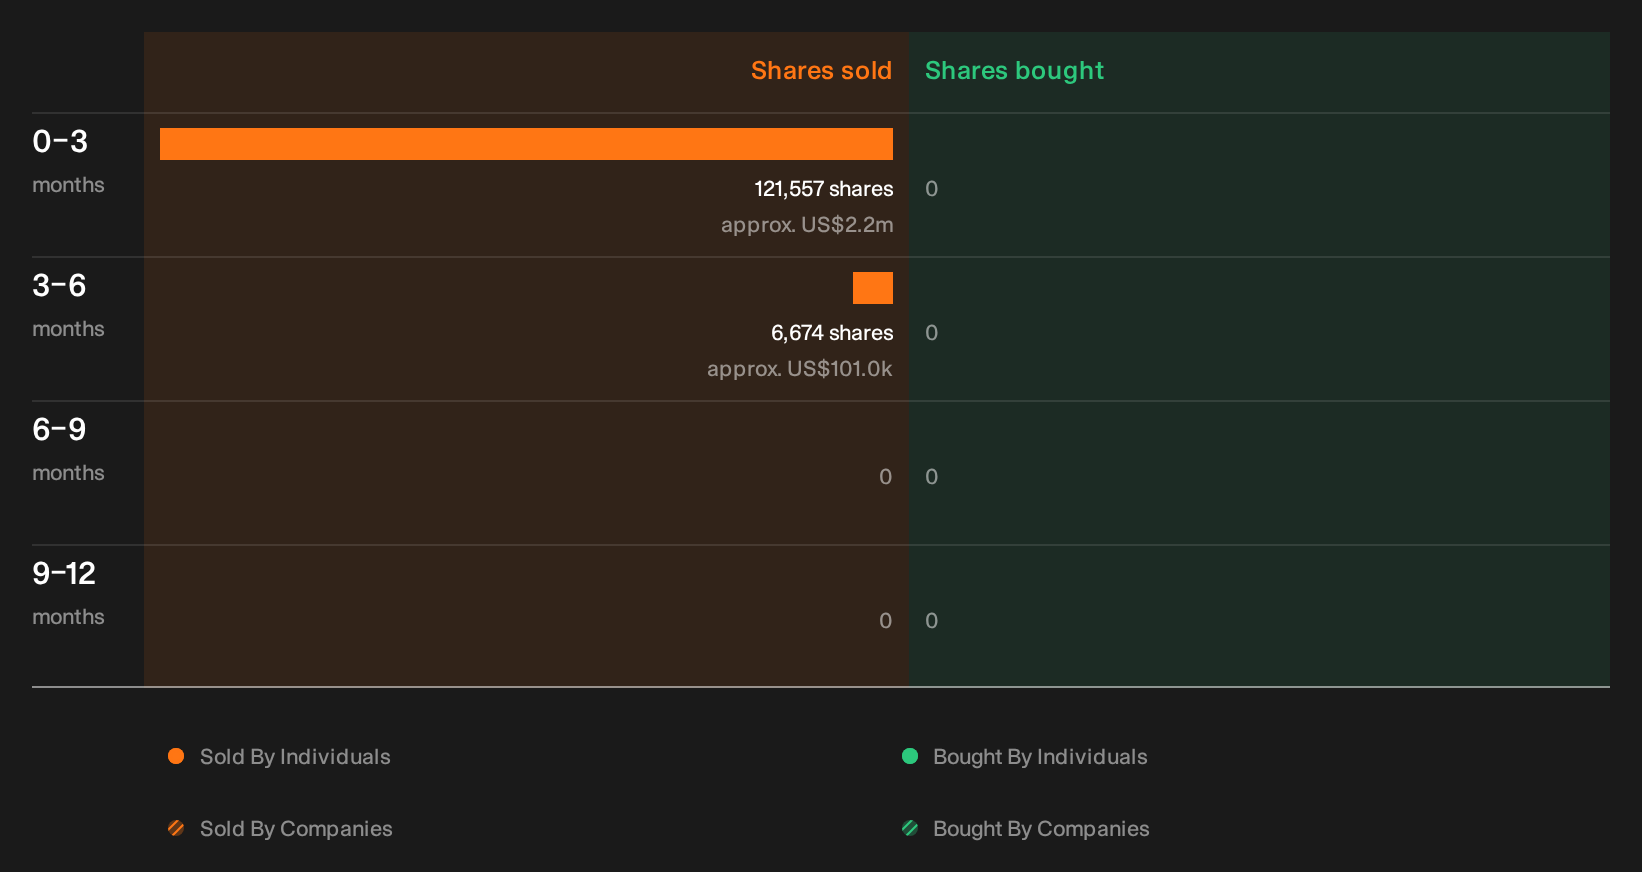
Valuation only tells part of the picture for Fortrea Holdings, and recent share dealings by people inside the business raise a separate question that careful investors often study closely. See the recent insider selling flagged for Fortrea Holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com