
GRAIL (GRAL) Stock Looks Overvalued On Its 131% One Year Run
GRAIL has seen its share price climb sharply over the past year, helped by enthusiasm around its Galleri multi cancer early detection test and fresh funding. With the stock now at US$108.52, the key issue for investors is how that price stacks up against the sales the business is actually generating.
- GRAIL has returned 131.0% over the past year, which raises the question of whether the share price has moved faster than its ability to grow revenue.
- Recent positive FDA commentary on Galleri and a US$110m financing round from Samsung can shape expectations for future test volumes, commercialization timing and the rate at which sales may build from here.
- Your read on GRAIL is one view; the desks covering it have another. See what analysts think GRAIL's shares could be worth.
The stock's next move may depend on whether that recent share price performance is well supported by the level of sales GRAIL is producing today.
If you are weighing GRAIL's rapid 131.0% one year move against its current sales base, it can help to compare it directly with 29 high quality undervalued stocks.
Is GRAIL Getting Expensive on Sales?
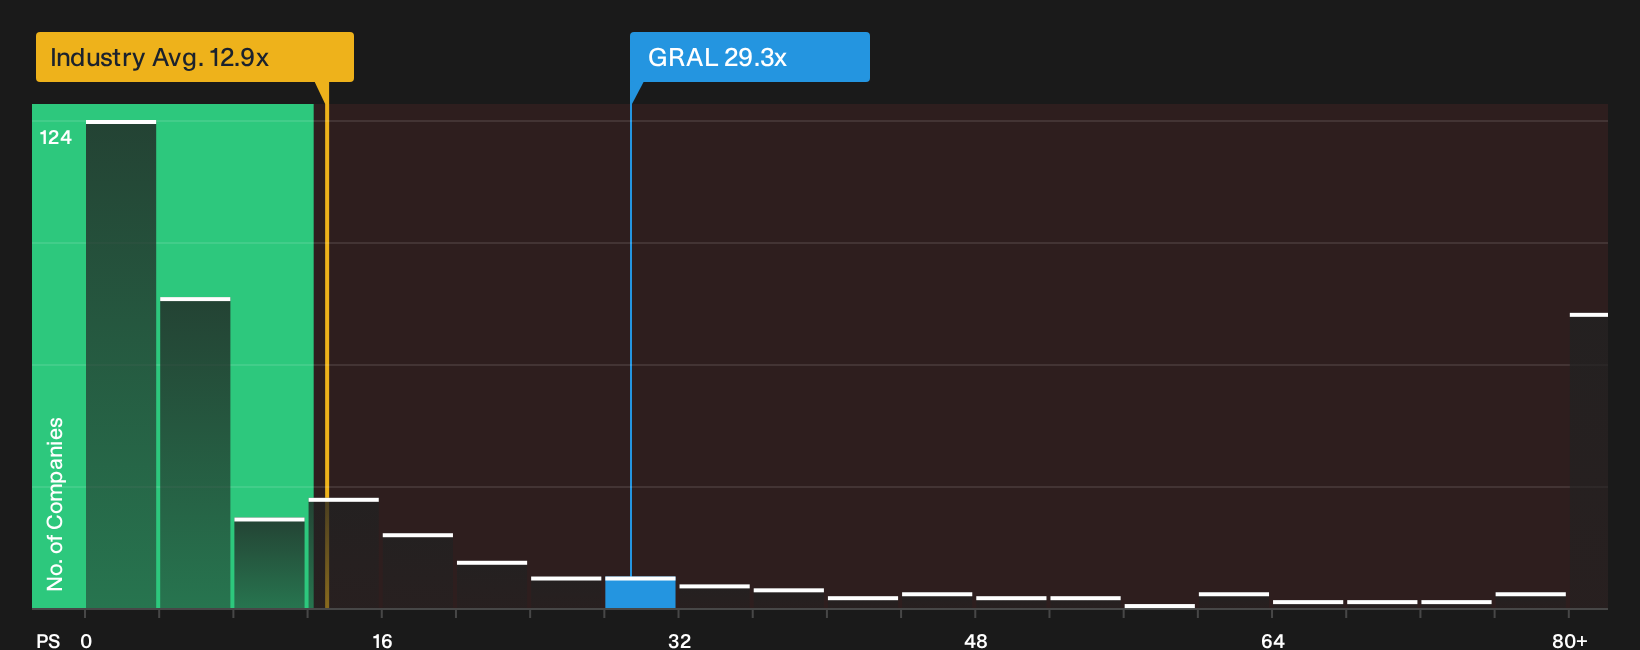
P/S is a better guide for GRAIL right now because investors are mostly paying for its current revenue base rather than earnings. At roughly 29.3x sales, the stock trades at more than double the Biotechs sector average of about 12.9x and also well above the peer group on roughly 13.7x. That is a rich headline number for any diagnostics business, even one tied to a high profile product like Galleri.
The fair value model suggests a lower P/S would be more in line with GRAIL's risk, profitability profile and market position, although the gap is so wide that it reads more as a warning flag than a precise target. Recent optimism around positive FDA staff commentary and the Samsung financing round has helped sentiment, yet the current P/S still prices GRAIL as a very expensive stock on this framework. Explore the numbers behind GRAIL's P/S valuation.
The GRAIL Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where GRAIL's valuation puzzle leaves off by spelling out what kind of future for growth, margins and earnings would need to play out for the stock to be worth materially more or less than it is today. Each one treats GRAIL's fair value as a hypothesis about the business that you can revisit over time rather than a one off snapshot, all housed on the Community page.
One of the top community narratives on GRAIL: roughly fairly valued
"The NHS Galleri trial and PATHFINDER 2 together create a large body of randomized and registrational data on stage shift and safety..."
Discover why this Narrative puts GRAIL at roughly fairly valued.
One more GRAIL factor to check before making a move
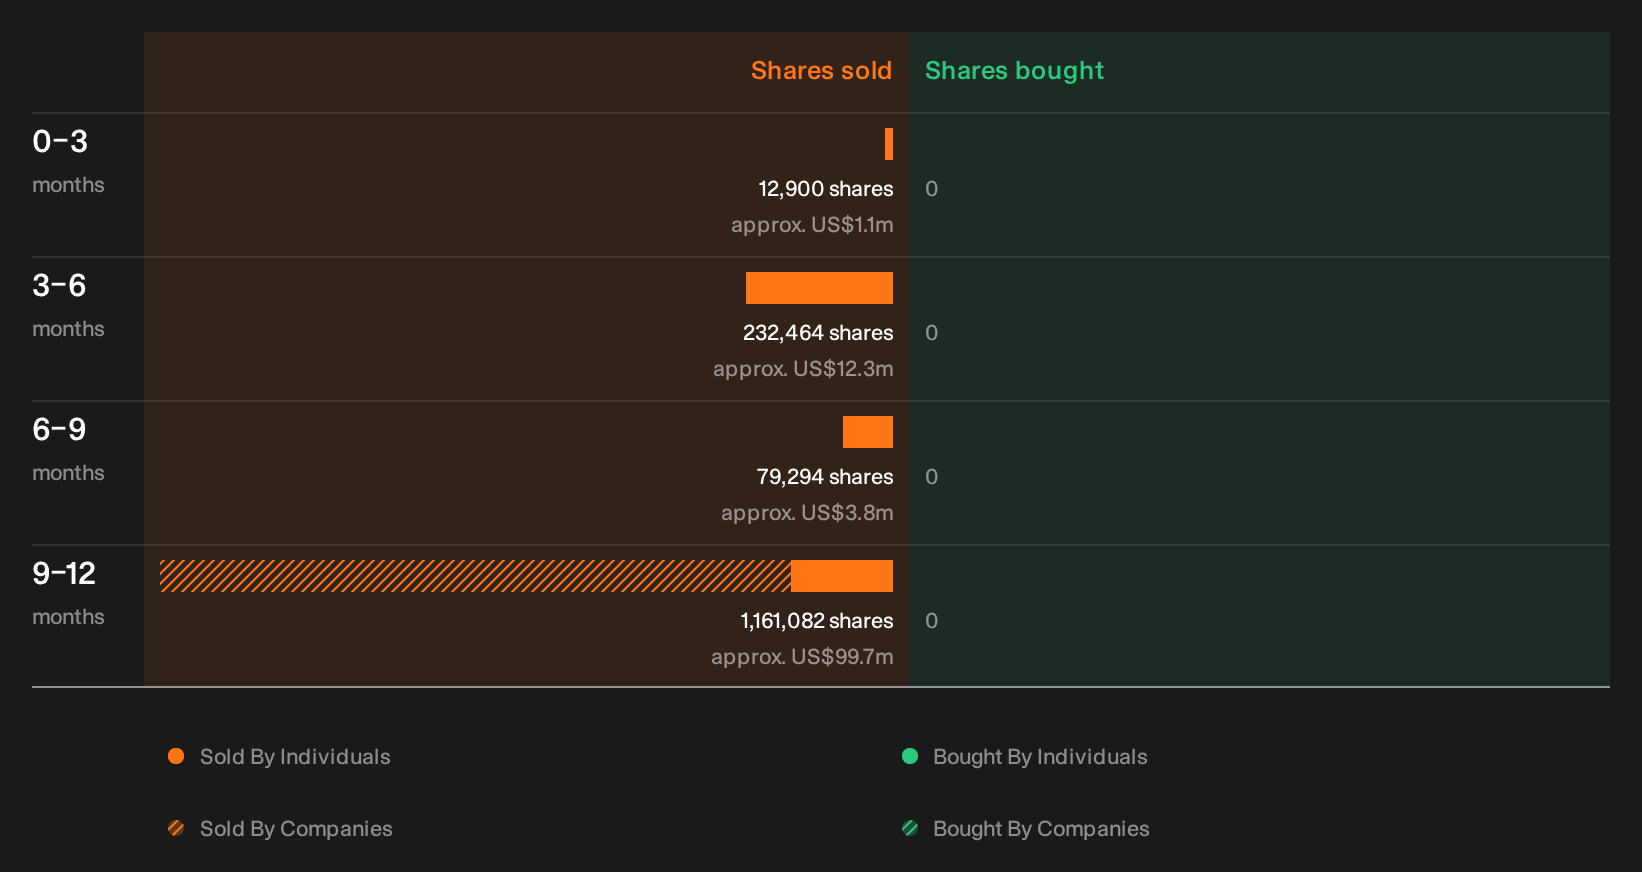
Before acting on any view of GRAIL's valuation, it is worth looking at what insiders have been doing with their own holdings, including who has been selling and on what scale. See the recent insider selling flagged for GRAIL.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com