
Asian Growth Stocks With Strong Insider Confidence
As Asian markets navigate a complex landscape of economic shifts and technological advancements, investors are increasingly focusing on growth stocks that demonstrate resilience and potential for long-term success. In this environment, companies with high insider ownership can signal strong confidence from those closest to the business, making them particularly appealing to investors seeking stability amid uncertainty.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 119.7% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 116.3% |
| Meiko Electronics (TSE:6787) | 19.2% | 33.8% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gold Circuit Electronics (TWSE:2368) | 29.8% | 43.6% |
| Fulin Precision (SZSE:300432) | 11.2% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's dive into some prime choices out of the screener.
Suzhou Maxwell Technologies (SZSE:300751)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Suzhou Maxwell Technologies Co., Ltd. specializes in the design, research and development, production, and sale of solar cell production equipment in China, with a market cap of CN¥56.66 billion.
Operations: The company's revenue segments include Individual Machines at CN¥1.27 billion, Components and Accessories at CN¥306.04 million, and Solar Cell Production Equipment at CN¥5.27 billion.
Insider Ownership: 39.3%
Suzhou Maxwell Technologies demonstrates strong growth potential with earnings forecasted to grow 50.03% annually, outpacing the Chinese market's 27.6%. Revenue is also expected to rise by 23.1% per year, surpassing the market average of 17.5%. Despite a volatile share price and a low projected return on equity of 15.6%, the company's insider ownership suggests alignment with shareholder interests. Recent earnings show a decline, but dividend distributions remain consistent at CNY 0.50 per share for September 2026.
- Unlock comprehensive insights into our analysis of Suzhou Maxwell Technologies stock in this growth report.
- Insights from our recent valuation report point to the potential overvaluation of Suzhou Maxwell Technologies shares in the market.

Auras Technology (TPEX:3324)
Simply Wall St Growth Rating: ★★★★★★
Overview: Auras Technology Co., Ltd. manufactures, processes, and retails electronic materials and computer cooling modules across multiple countries including China, Taiwan, Ireland, Singapore, and the United States with a market cap of NT$148.92 billion.
Operations: The company's revenue primarily comes from its Electronic Components & Parts segment, generating NT$30.81 billion.
Insider Ownership: 20.4%
Auras Technology exhibits robust growth potential, with earnings forecasted to grow significantly at 31% annually, surpassing the Taiwanese market's 25.3%. Revenue is also projected to increase by 25.7% per year, outpacing the market average of 21.8%. Despite a volatile share price recently and high levels of non-cash earnings, recent results show substantial growth in net income and sales compared to last year, indicating strong operational performance.
- Dive into the specifics of Auras Technology here with our thorough growth forecast report.
- Our valuation report here indicates Auras Technology may be overvalued.
King Slide Works (TWSE:2059)
Simply Wall St Growth Rating: ★★★★★★
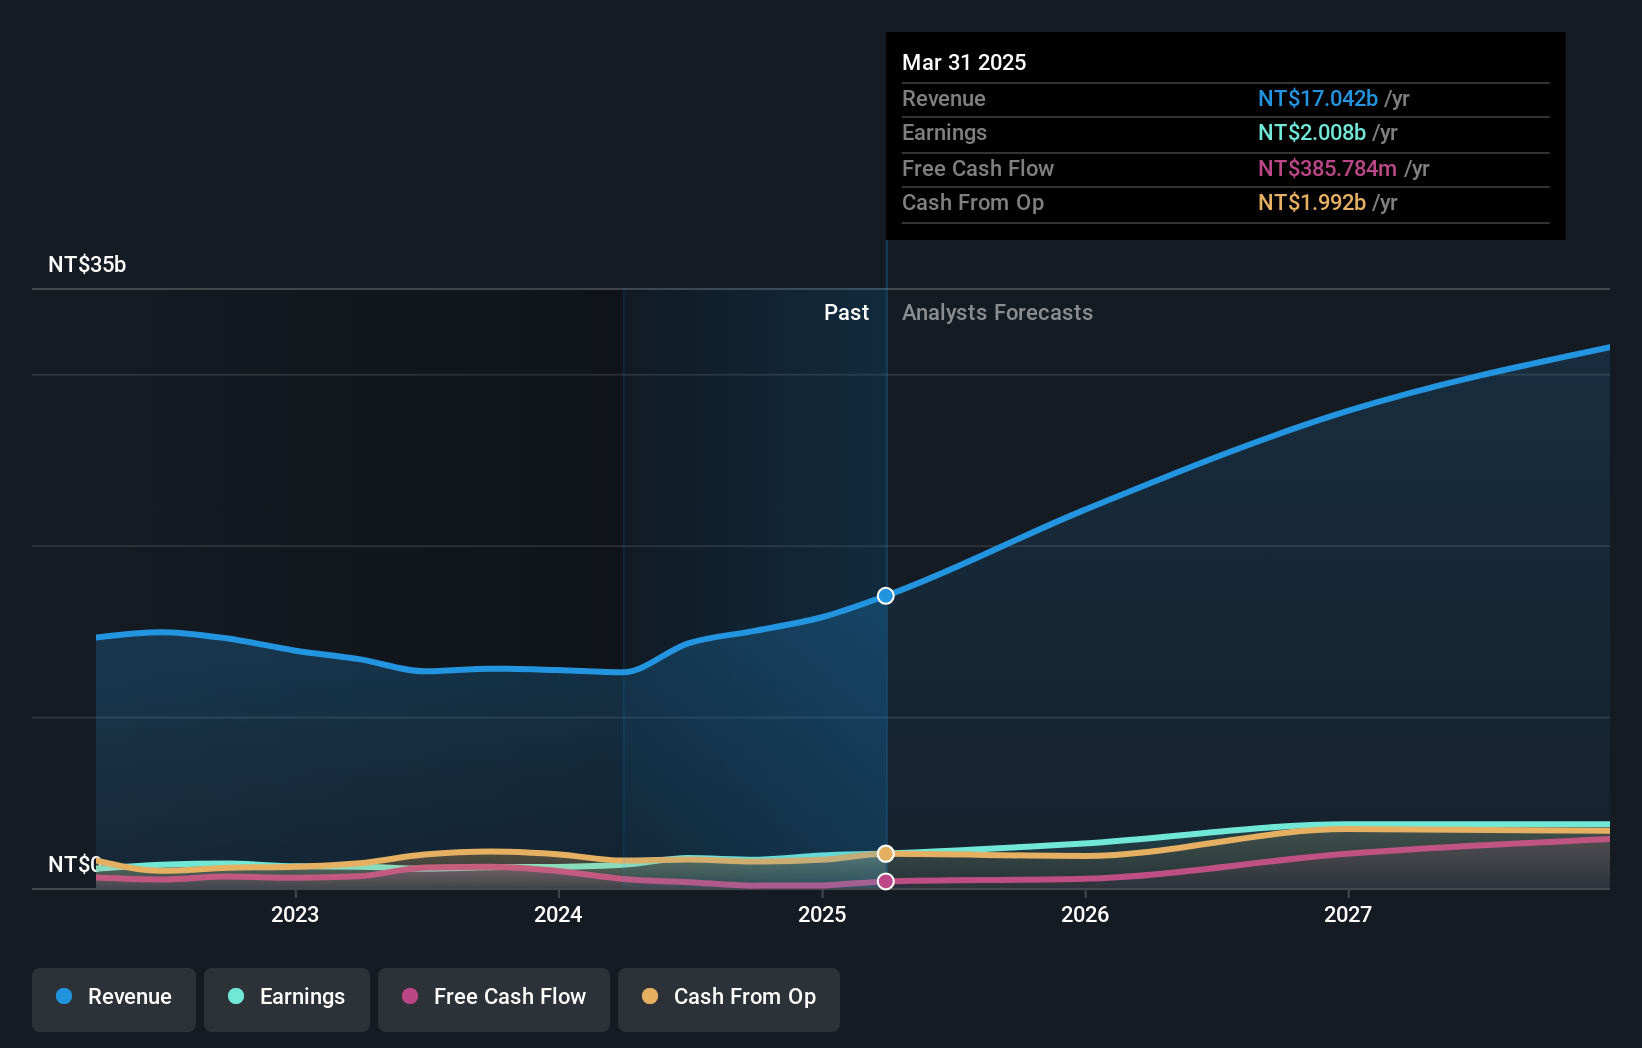
Overview: King Slide Works Co., Ltd. researches, designs, manufactures, distributes, and sells rail kits for cloud servers, network communications, kitchenware, and consumer electronics in Taiwan and internationally; it has a market cap of NT$1.21 billion.
Operations: The company's revenue segments include NT$2.02 billion from King Slide Works Co., Ltd. and NT$24.23 billion from King Slide Technology Co., Ltd.
Insider Ownership: 17.3%
King Slide Works demonstrates strong growth potential, with earnings expected to grow significantly at 44.1% annually, outpacing the Taiwanese market's 25.3%. Revenue is also forecasted to increase by 42.3% per year, exceeding market averages. Recent earnings results revealed a dramatic rise in net income and sales compared to last year, although the share price has been highly volatile recently. The company benefits from high insider ownership without substantial recent insider trading activity.
- Click here and access our complete growth analysis report to understand the dynamics of King Slide Works.
- Our expertly prepared valuation report King Slide Works implies its share price may be too high.

Summing It All Up
- Click here to access our complete index of 494 Fast Growing Asian Companies With High Insider Ownership.
- Curious About Other Options? AI is about to change healthcare. These 132 stocks are working on everything from early diagnostics to drug discovery. The best part - they are all under $10b in market cap - there's still time to get in early.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com