
NetApp (NTAP) Stock May Be 19% Below Fair Value On Cash Flow
NetApp has delivered a powerful run over the past few years, and the stock now changes hands at around US$192.91. With that kind of share price level, the real question for you is whether the current valuation lines up with the cash the business is expected to generate.
- Over the past 3 years, NetApp has returned 173.3%, which puts a lot of pressure on the current price to be supported by its underlying cash flows.
- The company’s storage and data management model tends to turn earnings into cash at a meaningful rate, which can matter a lot for how resilient those cash flows are against future investment needs.
- What if you looked at NetApp through its earnings instead? See why NetApp's 26.7x P/E tells a different valuation story.
The issue now is whether NetApp’s recent share performance is adequately underpinned by the intrinsic value suggested by its cash flows.
If you want a benchmark for whether NetApp’s cash flow driven story looks compelling, compare it with companies in the same bracket using the 29 high quality undervalued stocks
Is NetApp Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) model here is built around the cash NetApp can plausibly return to shareholders over time. Latest twelve-month free cash flow sits at about $1.68b, which gives the calculation a fairly solid starting point rather than a single boom year or one-off dip.
Analysts feeding into this DCF are assuming that free cash flow keeps growing from that base, with projections moving into the low $2b range by 2029, followed by more modest growth in the subsequent years. That pattern fits a mature software and hardware provider, where the story is less about rapid expansion and more about steady cash generation from storage and data management contracts. On those assumptions, the model puts NetApp's estimated intrinsic value meaningfully above the current share price of $192.91, which points to a gap between what the cash flows suggest and how the market is pricing the stock today. Find out what NetApp could be worth using our Discounted Cash Flow (DCF) estimate.
The NetApp Narrative: What Would Justify Today's Price?
Narratives for NetApp sit between the DCF puzzle above and the real world by spelling out what would need to happen to revenue, margins and earnings for the stock to trade meaningfully higher or lower than today. They live on Simply Wall St's Community page. Rather than relying on a single valuation output, each narrative lays out the specific assumptions behind its fair value so you can compare them with NetApp's reported results over time.
The community is broadly aligned on NetApp’s quality but splits on how much room is left in the current share price.
Bull case: roughly fairly valued
"Surging AI and hybrid cloud adoption is boosting demand for NetApp's integrated, subscription-based storage solutions and expanding its high-margin, recurring revenues..."
Discover why this Narrative puts NetApp at roughly fairly valued.
Bear case: 13% overvalued
"Rising DRAM and NAND component costs, combined with customer budgets that are typically set in dollar terms, increase the risk that price increases reduce future unit volumes or delay refresh cycles..."
Explore why this Narrative puts NetApp at 13% overvalued.
One more NetApp check that sits alongside the cash flow story
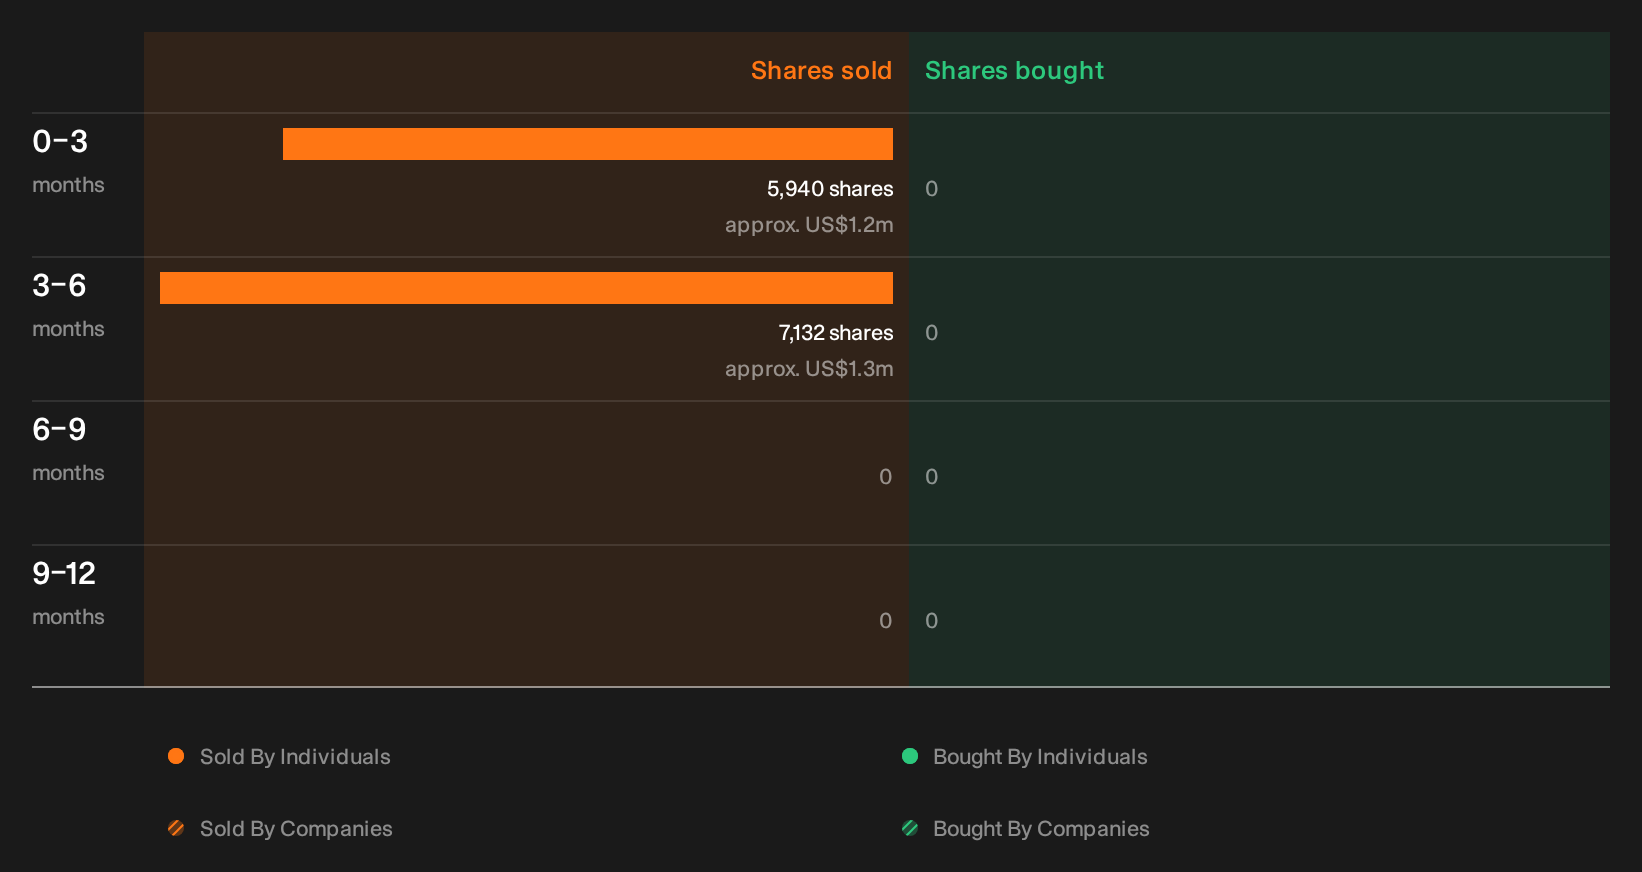
Price and cash generation only tell part of the story for NetApp, since recent activity from company insiders has raised a fresh question about how management are acting around the current valuation. See the recent insider selling flagged for NetApp.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com