
UBS Group (SWX:UBSG) Could Be 9% Undervalued Following Its US$7.9b Debt Tender
UBS Group (SWX:UBSG) is back in the spotlight after a large debt tender, with the bank accepting about US$7.9b of outstanding notes across nine issues and increasing its planned purchase size.
These buybacks of outstanding notes come after a busy period for UBS Group, where attention has swung between its capital plans and regulatory debates around AT1 capital. The recent tender activity appears to have coincided with fading short term share price momentum, despite strong multi year total shareholder returns.
Spot other banks and financials showing strong total return profiles and active balance sheet moves with a curated list of 171 high quality undervalued stocks.Bulls see UBS Group using the debt tender and strong multi year returns as proof the valuation still looks generous. Bears see fading short term momentum as a warning. Which case do the current numbers lean toward next?
Most Popular Narrative: 9% Undervalued
Against the latest close of CHF40.33, the most followed narrative puts UBS Group's fair value at CHF44.11, implying a clear discount while still stressing that execution and regulatory outcomes matter as much as the headline gap.
The ongoing integration of Credit Suisse is progressing ahead of schedule, driving meaningful cost savings, increased scale, and improved operating efficiency. As these synergies are realized through further platform migration and operational streamlining, UBS's net margins and return on equity are likely to improve, supporting higher earnings growth.
See why 56 investors see UBS Group as 9% undervalued.
Result: Fair Value of CHF44.11 (UNDERVALUED)
Still, the UBS Group story can shift quickly if proposed Swiss capital rule changes require tens of billions more in equity, or if compliance failures keep driving higher regulatory costs.
Find out about the key risks to this UBS Group narrative.
Another View: UBS Group On Earnings Multiples
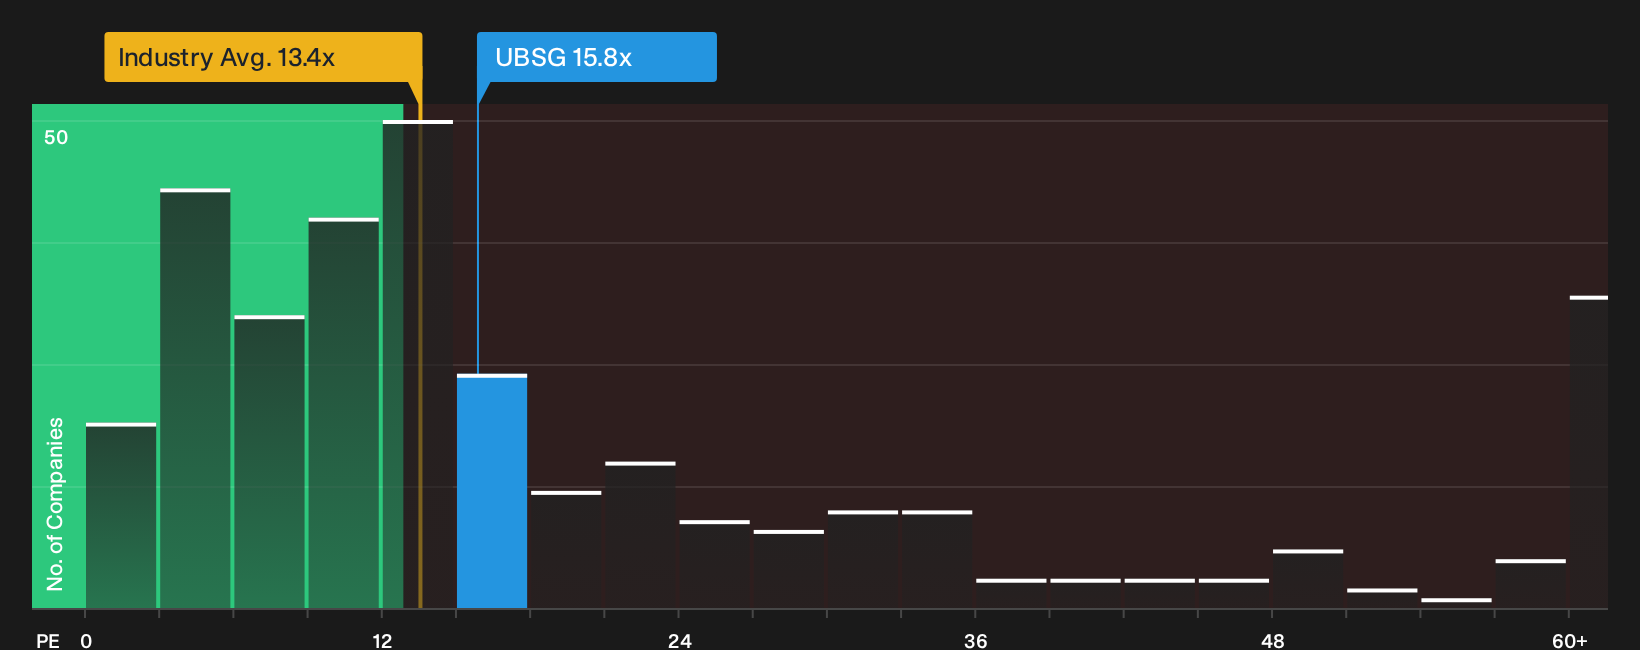
On the first cut, UBS Group looks cheap against a fair value of CHF44.11. Yet the current P/E of 15.8x is higher than the wider European capital markets group at 13.4x, even if it sits below a fair ratio of 23.8x that our model suggests the market could move toward.
That mix points to some valuation support but also less margin for error if earnings or returns disappoint. How comfortable are you paying a premium to the sector while assuming the franchise earns its way toward that higher fair ratio?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The split between UBS Group bulls and bears is clear, so use that tension as a prompt to move quickly, review the underlying evidence yourself, and then weigh up the 3 key rewards and 4 important warning signs in 3 key rewards and 4 important warning signs
Looking for more investment ideas beyond UBS Group?
If UBS Group has your attention, do not stop there. Use the same disciplined approach across sectors and find opportunities that better match your risk and income goals.
- Target potential mispricings by running through a curated collection of companies on our 171 high quality undervalued stocks that pair solid fundamentals with discounted valuations.
- Strengthen the income side of your portfolio by scanning a focused pool of high yield payers through the 160 dividend fortresses.
- Dial down portfolio stress and focus on resilience by filtering for businesses in the 229 resilient stocks with low risk scores before the market fully catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com