
Is Pfizer (PFE) Getting Too Pricey After Its 24% Rise?
Pfizer has delivered a 1 year gain that may catch the eye of investors who remember how volatile large drug makers can be, and the question now is whether the current share price at around US$27.93 is properly supported by its earnings power.
- The stock is up 23.9% over the past year. This puts more focus on whether that rise lines up with what the business is earning today and may earn in the near term.
- A new agreement to share a portion of extra overseas pricing revenue with the US Department of Health and Human Services can shape expectations for future profitability, since it affects how much of any higher international pricing flows through to Pfizer’s bottom line.
- Your read on Pfizer is one view; the desks covering it have another. See what analysts think Pfizer's shares could be worth.
The issue now is whether Pfizer's current valuation is justified by its earnings profile when set against the Fair Ratio benchmark.
If you want more context around Pfizer's 23.9% 1 year gain and the recent drug pricing headlines, it can help to compare it with 29 high quality undervalued stocks.
Does Pfizer Look Pricey on Earnings?
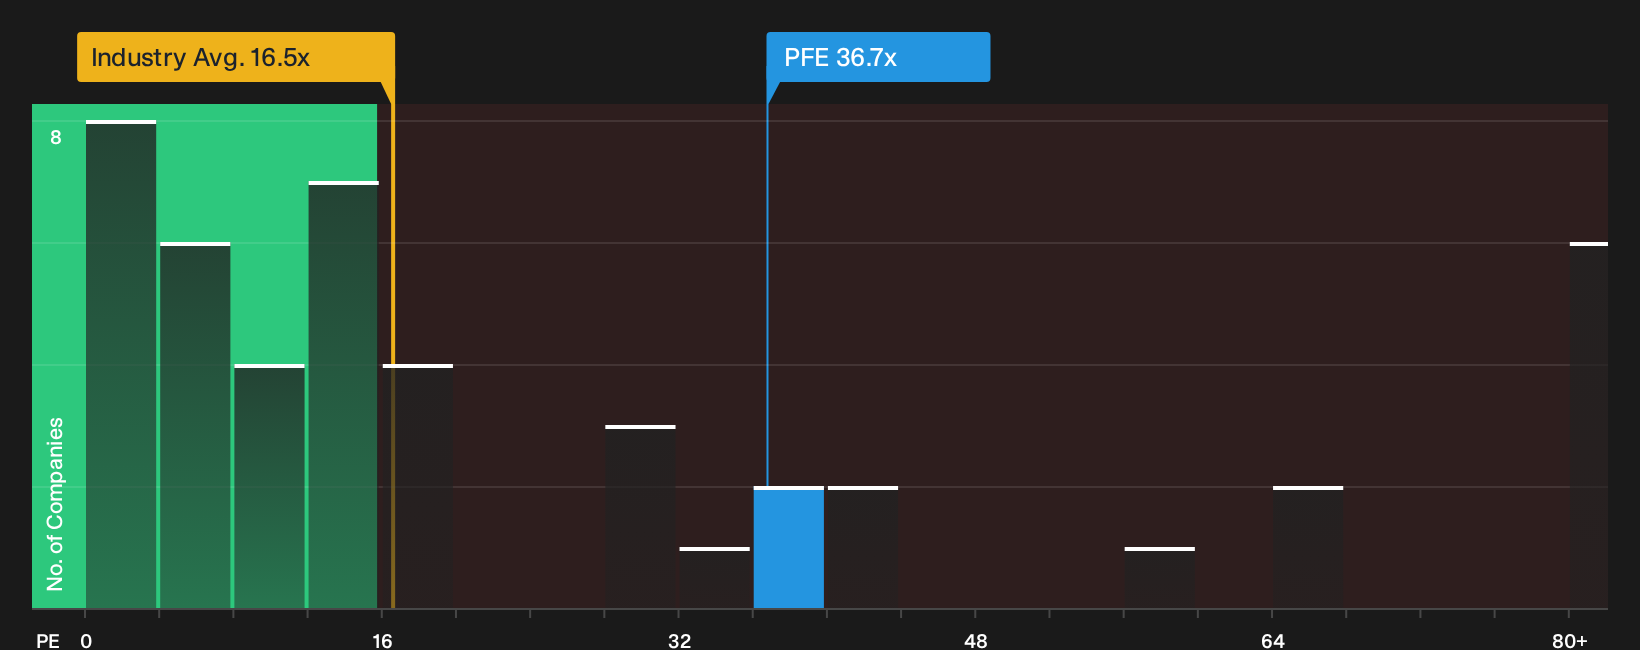
P/E works well for Pfizer because investors often focus on how much they are paying for each dollar of earnings in large, established drug groups. At a P/E of 36.7x, the stock trades above both the pharmaceuticals industry average of 16.5x and Pfizer's peer group on about 56.8x, which already reflects some market optimism around its earnings profile.
The Fair Ratio, which blends Pfizer's growth outlook, profitability, size and risk into a tailored benchmark, sits below the current multiple. As a result, the shares screen overvalued on this framework. Despite the new HHS revenue sharing deal shaping expectations for future overseas pricing economics, the market is still placing a richer earnings multiple on Pfizer than this model would suggest is warranted. Explore the numbers behind Pfizer's P/E valuation.
The Pfizer Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E and Fair Ratio leave off by explaining which future paths for Pfizer's growth, margins and earnings would need to occur for the share price to appear meaningfully higher or lower than it does today on the screen. Instead of giving a single number, they unpack the assumptions that number relies on so you can see what to monitor over time. These scenarios sit on Pfizer's Community page and turn the valuation puzzle into specific conditions you can follow.
Pfizer investors are weighing a community view that sees enough in the pipeline to keep the story roughly fairly valued against a more cautious camp that thinks the stock looks about 12% overvalued.
Bull case: roughly fairly valued
"Expansion of launched and acquired products, including Seagen and Biohaven portfolios that generated US$3.2b of Q2 2026 revenue and grew at double digit rates, supports the view that Pfizer can further shift its mix toward non COVID therapies..."
Discover why this Narrative puts Pfizer at roughly fairly valued.
Bear case: 12% overvalued
"Pfizer faces intensifying global pressure to contain healthcare costs, as governments and insurers negotiate aggressively for lower drug prices and plan to institute price caps..."
Explore why this Narrative puts Pfizer at 12% overvalued.
One more Pfizer factor to check before you act
Before you lean too heavily on any valuation work for Pfizer, it is worth looking at who is steering the business, how their incentives are set up and whether those rewards line up with shareholder outcomes. See who runs Pfizer and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com