
Newron Pharmaceuticals (SWX:NWRN) Stock Faces Mounting Loss Pressure On Thin Revenue
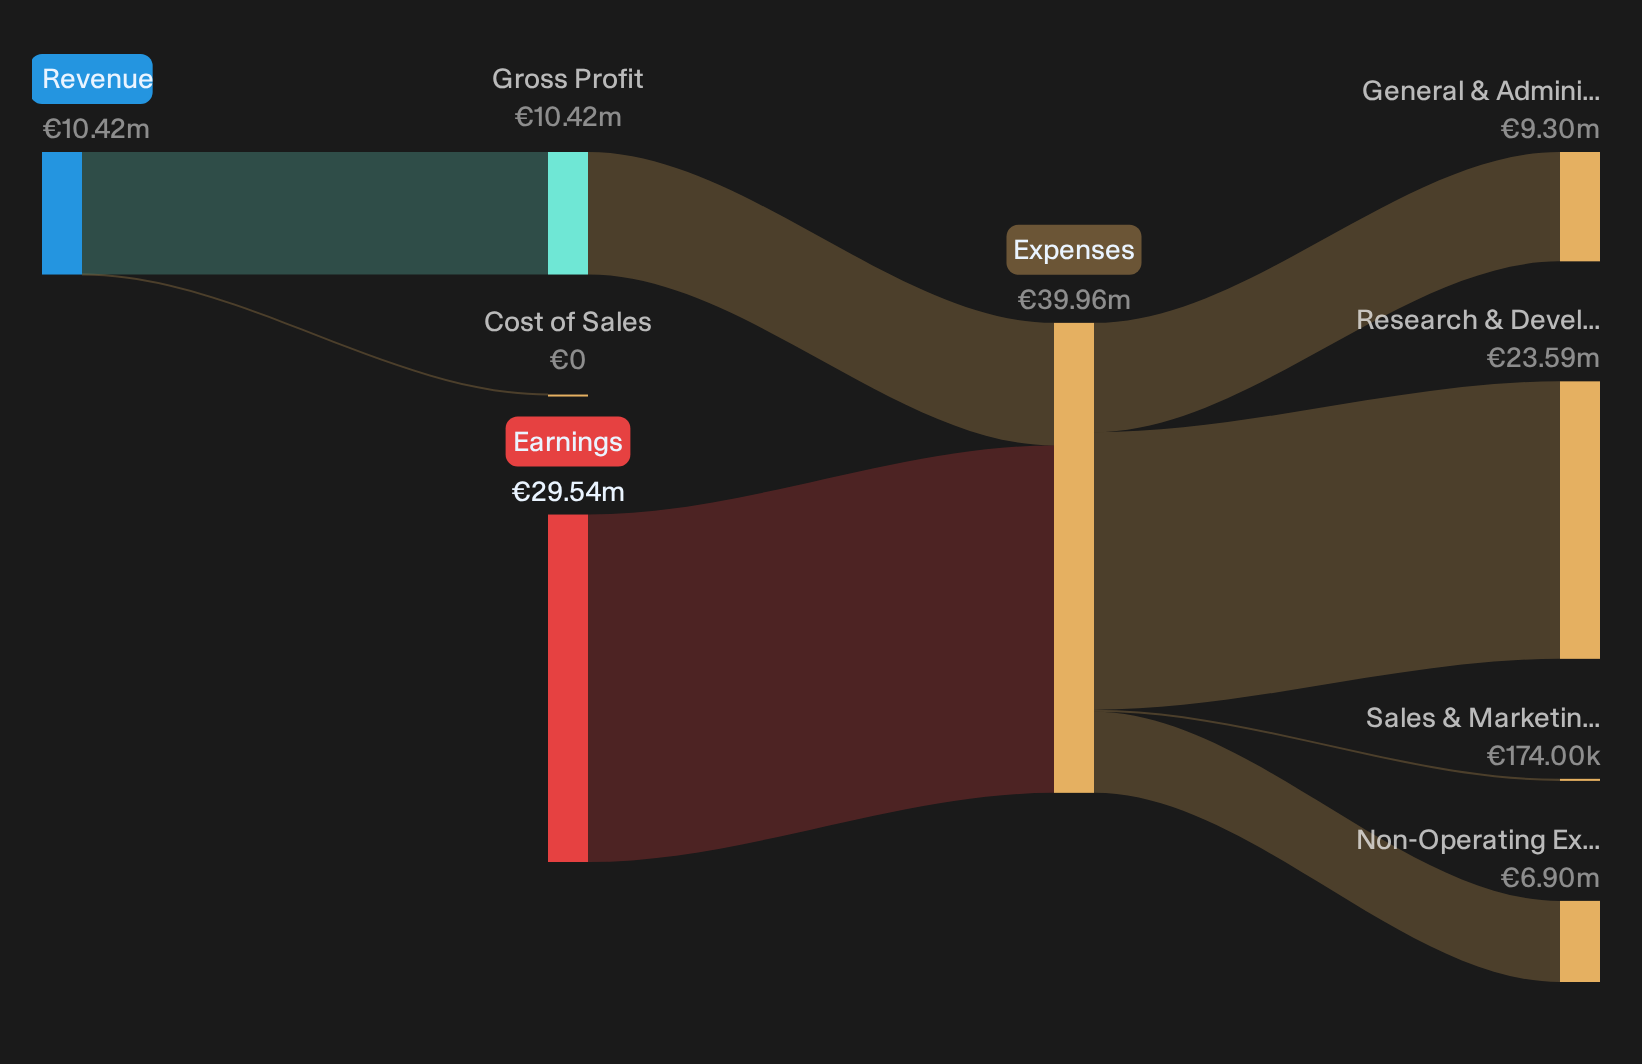
The Newron Pharmaceuticals stock closed today at CHF11.06, roughly flat over the past week after a weaker run across the last month and quarter. The market reaction looks muted; yet the headline from this half year is not about the share price. It is the strain running through the income statement. H1 2026 revenue came in at €3.189m while the company reported a loss of €16.372m, a sharp swing from the far smaller hit booked a year ago. For a biotech that still carries negative shareholders’ equity, that gap between sales and losses is the story to watch.
Concerned that Newron Pharmaceuticals is still posting losses on modest sales and want biotech exposure with sturdier finances instead? Take a look at our curated list of list of solid balance sheet and fundamentals stocks (198 results).
H1 2026 Earnings Summary
- Revenue (H1 2026 vs. H1 2025): €3.189m vs. €11.898m (reported decline in top line)
- Net Loss (H1 2026 vs. H1 2025): €16.372m loss vs. €0.073m loss (loss widened materially year on year)
- Basic EPS (H1 2026 vs. H1 2025): €0.80 loss per share vs. near breakeven at €0.00 loss per share (earnings per share moved further into loss)
- Pipeline Scale (Trailing 12 Months, 2025 H2 snapshot): 1 product in Phase II and 6 products in Phase III (clinical portfolio remains concentrated in late stage development)
Prefer clean charts over slogging through dense financial tables? See Newron Pharmaceuticals' full financial picture, including a clear view of its balance sheet strength and obligations, in our company report for Newron Pharmaceuticals.
Newron bull case hinges on clinical and funding milestones
Bulls argue Newron Pharmaceuticals is executing on a clear path to commercialize evenamide through late stage trials while shoring up funding. The half year numbers partly support that story. The pipeline snapshot still shows 1 Phase II and 6 Phase III programs, which aligns with the claim that evenamide is among the more advanced schizophrenia candidates. That concentration in pivotal studies matters because the business is running on €3.189m of H1 2026 revenue against a €16.372m loss. Investors are effectively funding those trials rather than a commercial franchise.
Funding visibility is a key plank of the bullish view. The latest report references the Eisai collaboration, a new funding agreement and revised EIB loan terms, which all point to some breathing room. With shareholders’ equity still negative, the thesis that capital is in place for clinical execution looks partially validated but not yet stress free.
Compare Newron Pharmaceuticals' clinical progress and fresh funding runway with how the market is actually pricing that story. See the consensus price target analysis for Newron Pharmaceuticals to gauge whether analysts think SWX:NWRN can justify this level of risk.Newron bear case focuses on shrinking cushion
Bears argue Newron Pharmaceuticals is over reliant on one molecule with thin funding support and that this half year will expose that fragility. The earnings print gives them several points. Licensing and milestone streams that are meant to backstop cash burn look weak, with H1 2026 revenue at €3.189m while the loss widened to €16.372m. That is exactly the kind of gap critics mean when they flag dependency on external partners and non recurring income. The concern about dilution risk also finds indirect support. Shareholders’ equity remains negative and management is still leaning on loan revisions and fresh agreements for breathing space rather than internally generated cash.
Where the bearish story lacks a clear win is clinical. The pipeline snapshot still shows 1 Phase II and 6 Phase III programs. There is no fresh clinical setback in this update, only rising financial pressure behind the same asset.
After a loss profile this heavy and shareholders’ equity still in the red, it is fair to ask if Newron Pharmaceuticals has other structural weak spots that are not obvious from headline numbers. Review our structured risk analysis for Newron Pharmaceuticals which shows 2 important warning signsStay Ahead Of Your Next Move
If Newron Pharmaceuticals' widening loss against modest H1 2026 revenue has your attention, register for free with Simply Wall St and add it to a Watchlist to keep an eye on share price versus fair value and wait for a risk level that suits you. After you decide to take a position, use the Portfolio Command Center to cut through market noise and focus on the key developments that affect your holdings. For a broader view on sentiment around Newron Pharmaceuticals and other ideas, tap into the Community and see how different investors are thinking about similar trade offs. Spotting hidden catalysts and potential risks early can help you react faster and stay a step ahead of the wider market.
Seeking Alternatives Beyond Newron Pharmaceuticals?
Fresh ideas can move fast. Breakout stories gain momentum, quiet opportunities get caught early, and late entries risk dropping returns. Scan under the radar for now and act now.
- Spot resilient income plays before they start flying by reviewing curated yield opportunities in the 159 dividend fortresses that focus on durability as much as payout.
- Hunt for future infrastructure winners while they are still under followed by scanning the 40 power grid technology and infrastructure stocks built around long term electrification and grid upgrades.
- Track quietly compounding businesses before momentum headlines hit by filtering for financially robust candidates inside the list of solid balance sheet and fundamentals stocks (198 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com