
Fortis (TSX:FTS) Completes $500 Million Note Offering, Is The 7% Undervalued View Still Compelling?
How Fortis stock fits into the latest $500 million funding move
Fortis (TSX:FTS) has just completed a $500 million fixed to floating rate note offering due 2057, issuing junior subordinated, unsecured, callable debt that could reshape its long term capital structure.
Recent trading in Fortis reflects this funding backdrop, with the share price at CA$75.8 after a 6.39% year to date share price return. Meanwhile, total shareholder return of 14.87% over one year and 63.63% over five years points to momentum that has built over time rather than faded.
Scan other regulated utilities that show similar balance sheet resilience and potential funding catalysts by reviewing the hand picked list of solid balance sheet and fundamentals (7 results) alongside Fortis.
Fortis looks like a solid regulated utility with fresh access to CA$500 million of long dated funding. The open question is whether that strength is already fully reflected in the current share price.
Most Popular Narrative: 7% Undervalued
Fortis last closed at CA$75.8, while the most followed narrative puts fair value at CA$81.63. This frames the new CA$500 million notes within a wider story about regulated cash flows and long term projects.
Substantial planned capital investments in grid modernization, renewable energy integration, and battery storage (e.g., $2.9B invested in H1 2025 and upcoming projects at ITC and FortisBC) position the company to benefit from policy-driven infrastructure upgrades and decarbonization mandates, supporting above-average asset base growth and improved earnings visibility.
See why 85 investors see Fortis as 7% undervalued.
Result: Fair Value of CA$81.63 (UNDERVALUED)
Still, the Fortis story can shift quickly if rising capital costs pressure its CA$5.6b annual spending plans or if regulators tighten allowed returns in key regions.
Find out about the key risks to this Fortis narrative.
Another View on Fortis valuation
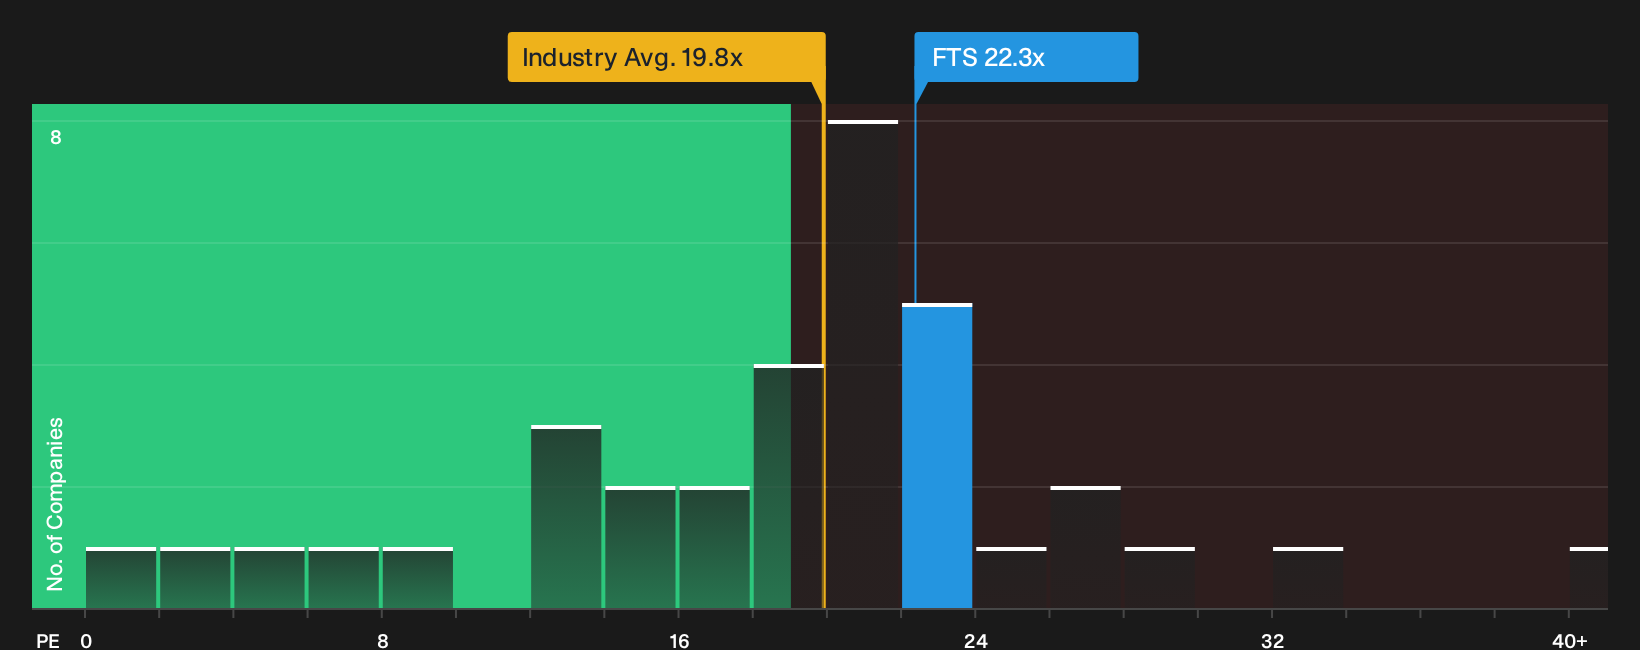
The first story presents Fortis as about 7% below fair value at CA$81.63. A different lens tells a tougher story. At a P/E of 22.3x, the stock trades richer than both Canadian peers at 20.9x and the wider North American utilities group at 19.8x, even though the fair ratio is 30.8x. That gap suggests investors already pay a premium today, while the model implies the multiple could move higher over time. Is that a healthy margin of safety or a lot of optimism baked in?
To see how that premium compares with the underlying numbers, and where the fair ratio might matter most, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Opinions differ on whether Fortis is fairly valued or still provides a margin of safety. You can assess the situation directly by reviewing the 3 key rewards and 2 important warning signs and weighing the evidence for yourself.
Looking for more Fortis style investment ideas?
If you only stop at Fortis, you risk missing other opportunities that match your goals, risk comfort, and time horizon across the broader market.
- Target steadier potential returns by checking the 8 resilient stocks with low risk scores which prioritizes balance sheet strength and historically lower price volatility.
- Hunt for better value by scanning the 7 high quality undervalued stocks where solid fundamentals meet prices that screen as below estimated fair value.
- Build a cash flow focused portfolio by reviewing the 1 dividend fortresses which spotlights higher yielding businesses with robust payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com