
Cenovus Energy (TSX:CVE) Stock Could Trade At A Discount To Earnings Value
Cenovus Energy has delivered a very strong multi year share-price run, which naturally raises a question for you as an investor. Is the current valuation still supported by the earnings power of the business, or has the share price moved ahead of what today’s profits justify?
- Over the past 5 years the stock has returned about 299.8%, which puts a lot of weight on whether current and future earnings can carry that kind of re-rating.
- The business model is heavily tied to converting commodity-linked revenue into stable earnings and cash flow, so the way Cenovus manages costs, capital spending and balance sheet risk can strongly influence how much profit each dollar of production translates into.
- The analysts covering Cenovus Energy have run their own numbers. See what analysts think Cenovus Energy's shares could be worth.
The issue now is whether today’s share price can be fully explained by Cenovus Energy’s earnings when set against a Fair Ratio benchmark.
If you want to test the same earnings based valuation question you are asking of Cenovus Energy across a wider set of opportunities, start by scanning 7 high quality undervalued stocks.
Is Cenovus Energy a Bargain on Earnings?
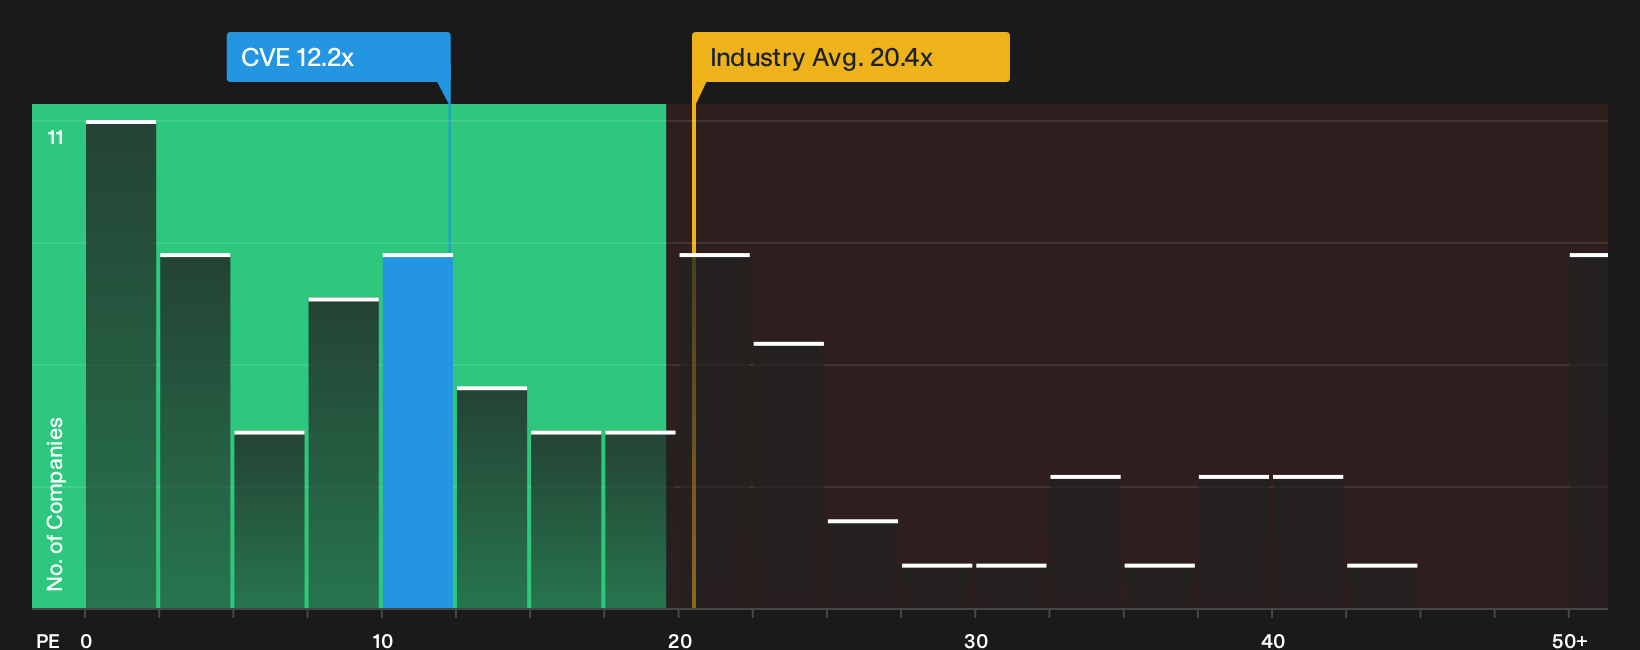
The P/E ratio suits Cenovus Energy because earnings are a key lens for a mature producer that already generates substantial free cash flow. On this metric the shares trade on about 12.2x earnings, which is below both the Oil and Gas sector average near 20.4x and the peer group around 17.1x. That gap indicates the market currently applies a lower earnings multiple to Cenovus than to many comparable producers.
A fair value framework that blends Cenovus Energy’s growth profile, profitability, size and risk points to a higher P/E than the one the market is using. In that context the current 12.2x sits on the cheaper side of that tailored benchmark, meaning that each CA$ of earnings is being valued more cautiously than the model would suggest. For you as an investor, a central consideration is whether the company’s earnings quality and future cash generation support the market keeping that discount in place or narrowing it over time. Explore the numbers behind Cenovus Energy's P/E valuation.
The Cenovus Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Cenovus Energy valuation puzzle leaves off by spelling out which assumptions on future growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price. Each one treats Cenovus Energy’s fair value as a thesis about the business that you can watch over time rather than a one off snapshot on a single date.
Community views on Cenovus Energy are split between those who see more upside in the long term cash story and those who focus on the execution and policy risks around that path.
Bull case: roughly fairly valued
"Completion of major projects and maintenance cycles positions Cenovus for higher production, lower costs, and stronger cash flow amid strong global energy demand…"
Discover why this Narrative puts Cenovus Energy at roughly fairly valued.
Bear case: roughly fairly valued
"Heavy reliance on long life oil sands and offshore projects, such as Foster Creek, Sunrise, Narrows Lake and West White Rose, exposes Cenovus to higher regulatory and cost pressures if long run policy and environmental requirements tighten…"
Explore why this Narrative puts Cenovus Energy at roughly fairly valued.
Cenovus Energy’s valuation check leaves one crucial angle unresolved
Price and earnings only tell part of the story for Cenovus Energy, because separate risk checks are flagging issues that could change how you view the whole picture. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com