
Is AI And Delivery Spending Altering The Investment Case For Amazon (AMZN)?
- Amazon.com has outlined heavy spending on AI infrastructure through AWS, new custom silicon partnerships, and a US$1.9b boost to its 2027 Delivery Service Partner program that supports higher driver pay, AI-powered safety tools, and expanded community initiatives.
- These commitments reinforce how Amazon.com is tying capital allocation directly to its logistics and cloud foundations, using AI for both last mile efficiency and data center performance, while also extending its reach through Anthropic, Qualcomm and a growing roster of third-party brands on its marketplace.
- We will now look at how Amazon.com's AI focused capital expenditure surge and DSP investment shape the broader investment narrative for the business.
Amazon.com Investment Narrative Recap
Owning Amazon.com still largely comes down to believing its heavy AI and logistics spending can translate into durable cash generation across AWS and retail. The short term swing factor is whether this capital cycle, including the US$220b capex plan, supports earnings without eroding margins too far. The latest DSP commitments look meaningful for service quality but do not materially change that near term earnings catalyst.
The biggest current risk remains cost escalation from labor, delivery networks, and data center buildouts outpacing measured revenue gains. Fresh wage and safety spending for drivers pushes that issue to the foreground. Investors will likely watch whether AI tools in routing and safety offset these higher costs fast enough to keep margins from slipping.
The US$1.9b DSP investment for 2027, on top of US$21.7b over eight years, is the clearest link between this news and Amazon.com’s wider story. Higher average pay near US$24 per hour, broader benefits, and AI based safety gear speak directly to the quality and reliability of last mile delivery, which supports the value of Prime and marketplace services.
Those same choices also sit right next to current risks. Labor and safety outlays are rising at the same time Amazon is funding large AI infrastructure and data center projects. The key execution question is whether AI guided routing, cameras, and smart glasses materially improve productivity and reduce accidents, so that logistics economics keep pace with what is being spent on drivers and equipment.
Amazon.com's narrative projects US$1,152.4b revenue and US$158.3b earnings by 2029, based on analysts assuming 14.1% yearly revenue growth and earnings rising by about US$23b from US$135.3b today.
Uncover why Amazon.com's fair value indicates a 28% potential upside to its current price, which could narrow quickly as sentiment catches up.
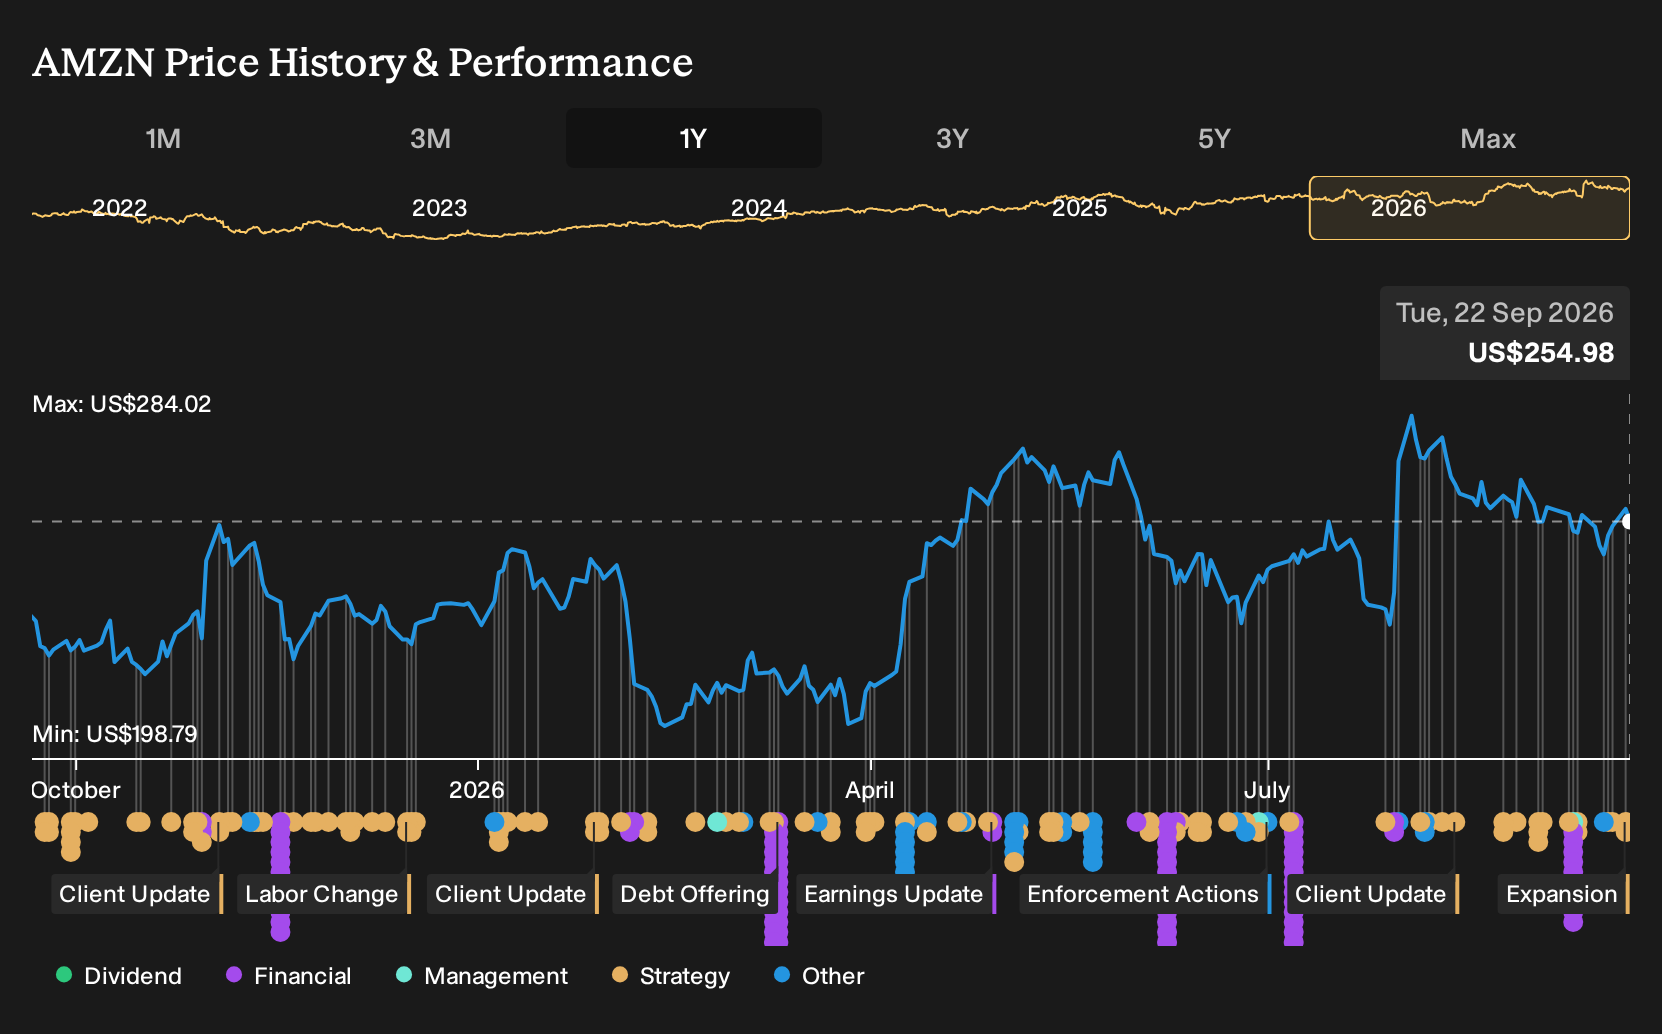
Exploring Other Perspectives
Fair value opinions on Amazon.com from 50 members of the Simply Wall St Community stretch from US$246.92 to US$475.09, which is a wide gap for the same stock. That range sits alongside rising AI capex, heavier DSP wage and safety commitments, and growing regulatory and competitive risks. Investor views clearly diverge, so explore several of these alternative takes before deciding how Amazon.com fits your own portfolio thesis.
Explore 49 other Amazon.com fair value estimates, including one that suggests it could be worth just $246.92.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Amazon.com research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Amazon.com. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amazon.com's overall financial health at a glance.
Looking For More Investment Ideas Beyond Amazon.com?
Once you have a view on Amazon.com, it can help to cross check that thesis against other opportunities that fit different risk, income, and quality profiles. The Simply Wall St Screener is built for exactly that, giving you a quick way to line up potential alternatives and see how they compare on fundamentals before you commit fresh capital.
- If you want higher return potential and can handle volatility, scan through 8 elite penny stocks with strong financials that combine small size with stronger balance sheets and cash flows than many peers.
- For investors who care more about resilience and capital preservation, start with 30 resilient stocks with low risk scores that score well on financial strength and business stability.
- If you prefer to focus on quality fundamentals that may not yet be widely appreciated, review the 16 high quality undiscovered gems that pair robust financial profiles with limited current market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com