
Could Green Bond Plans Change The Bull Case For Lerøy Seafood Group Stock?
- Lerøy Seafood Group recently appointed Danske Bank and DNB Carnegie to consider issuing NOK-denominated senior unsecured green bonds with a potential 6 year tenor and an indicated size of NOK 750 million, to fund projects under its Green Finance Framework.
- The contemplated green bond funding links Lerøy Seafood Group’s capital structure directly to its environmental project pipeline, tying future financing costs to the scale and timing of sustainability investments.
- We will now look at how Lerøy Seafood Group’s investment narrative could shift if green bond financing reshapes its future funding mix.
Scan how Lerøy Seafood Group’s green financing move compares with other balance sheet focused plays by running your eye over the handpicked list of solid balance sheet and fundamentals (197 results) in one place.
Lerøy Seafood Group Investment Narrative Recap
Lerøy Seafood Group is a bet on aquaculture efficiency and demand for traceable seafood. To stay invested, you need confidence that farming technology, vertical integration and global market access can offset pressure from feed costs, energy and logistics. The contemplated NOK 750 million green bond itself does not change that thesis, although it could influence how quickly environmental projects move.
In the short term, the key swing factor remains how production costs and salmon and trout prices interact after a period when spot pricing fell below production cost and squeezed margins. The main risk still sits with biology, regulation and cost inflation, not with funding access, assuming the green debt pricing stays reasonable and the balance sheet remains manageable.
Among recent developments, the focus on advanced farming technology such as submerged and shielding solutions feels most relevant to the new green bond plan. These are capital heavy projects. Management already flagged that such capex has lifted long term debt from NOK 7 billion to NOK 8.5 billion and puts pressure on free cash flow.
If Lerøy Seafood Group channels the contemplated bond proceeds into these green projects, execution will matter more than the headline size. Investors will likely watch whether survival rates, mortality and unit costs move in the right direction, and whether higher leverage coexists comfortably with a dividend that is currently not well covered by earnings.
Lerøy Seafood Group's current analyst narrative points to revenues of NOK 41.5b and earnings of NOK 3.7b by 2029, anchored on 6.4% yearly revenue growth and an earnings increase of NOK 2.7b from NOK 1.0b today.
Uncover why Lerøy Seafood Group's fair value indicates a 20% potential upside to its current price that could narrow quickly.
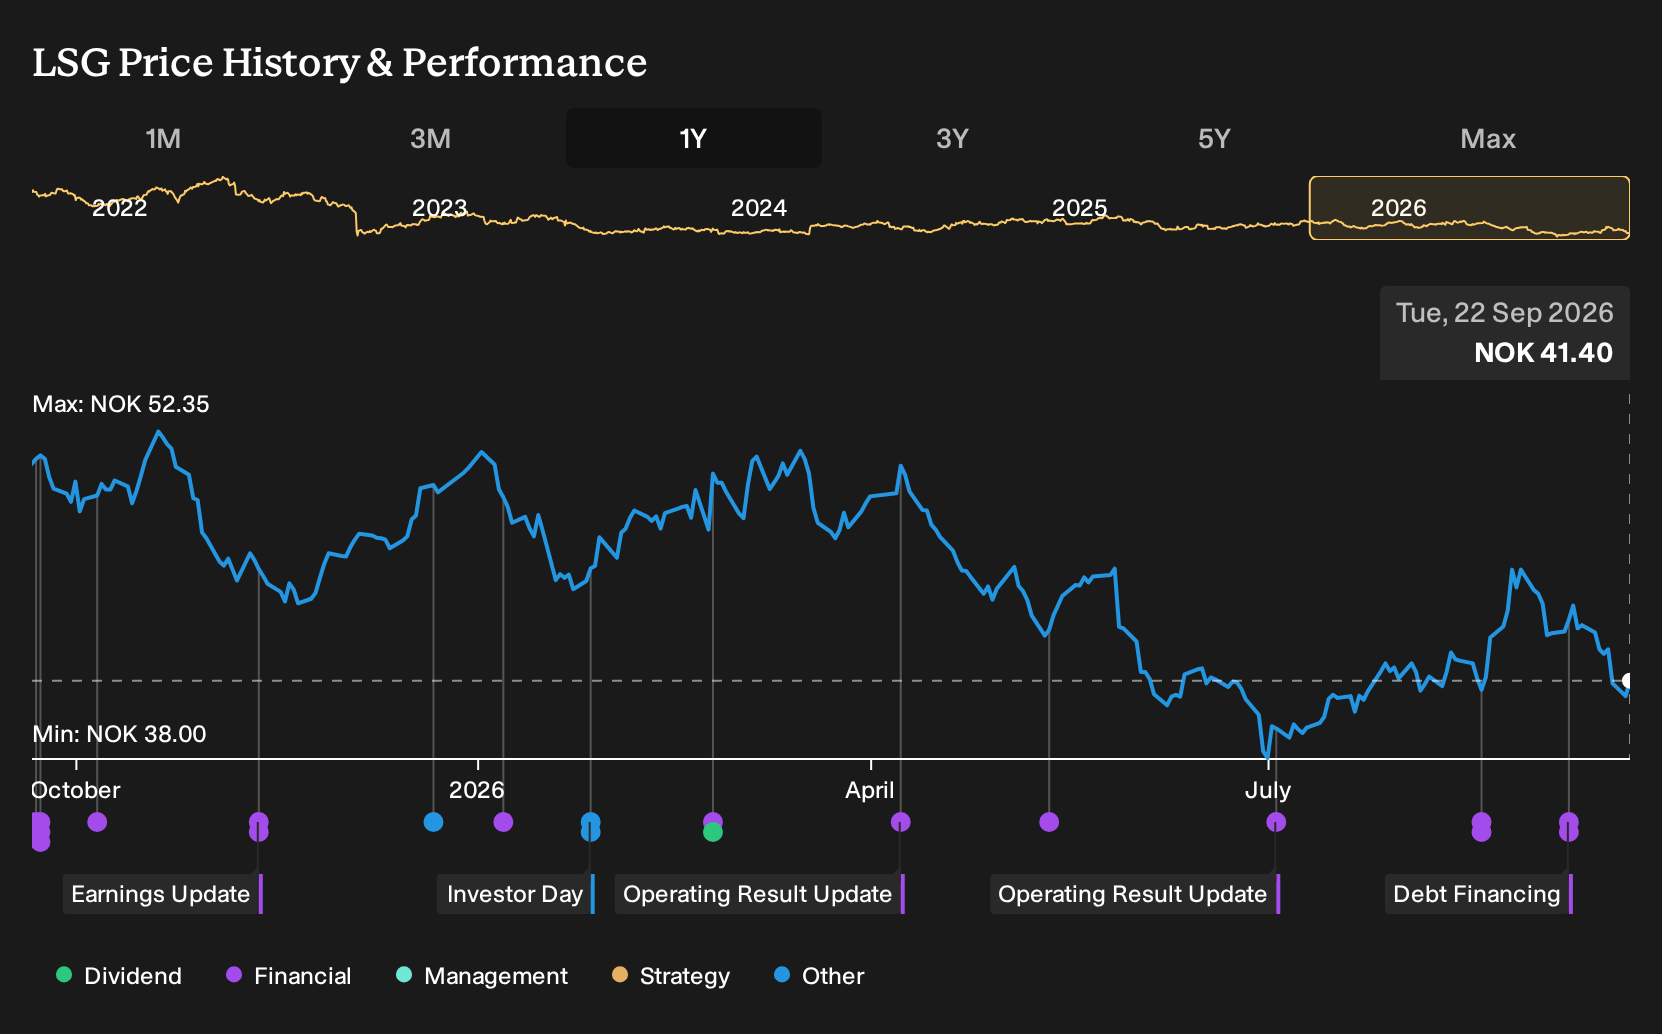
Exploring Other Perspectives
The lowest analysts focus on execution risk in Lerøy Seafood Group’s new shielding technologies rather than financing. Before this green bond news, they were already pencilling in about NOK 46.5b of revenue and NOK 3.2b of earnings by 2029. That is a more cautious path, and this funding step may yet reshape those expectations.
Explore another Lerøy Seafood Group fair value estimate, including one that suggests it could be worth just NOK49.50.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Lerøy Seafood Group research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Lerøy Seafood Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lerøy Seafood Group's overall financial health at a glance.
Looking for more investment ideas beyond Lerøy Seafood Group?
Once you have a view on Lerøy Seafood Group, it can help to cross check that thesis against other opportunities with different risk and return profiles using the Simply Wall St Screener.
- For investors who want potential mispricing with quality fundamentals, scan a 170 high quality undervalued stocks that may warrant a closer look.
- If capital preservation ranks high for you, filter for companies in the 230 resilient stocks with low risk scores that score well on resilience and stability.
- For those hunting for future market leaders before they hit the spotlight, sift through a curated 615 high quality undiscovered gems that the market may not be fully focused on yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com