
Is REX American Resources (REX) Undervalued Following A Fresh P/E Reassessment?
REX American Resources (REX) has drawn fresh attention after a market reassessment of its valuation, with the stock trading on a P/E ratio below the broader Oil and Gas peer group.
Recent trading has been choppy, with a 2.6% 1 day share price return and a 4.5% 7 day share price return. The 1 month share price return is slightly negative, yet REX American Resources still carries a 36.6% year to date share price return and a 5 year total shareholder return of 232.5%. This may indicate positive long term momentum, while the latest move appears more like a valuation reset than a fresh breakout.
Scan the market for other potential valuation reset stories by comparing REX American Resources with a curated 29 high quality undervalued stocks.
For REX American Resources, that recent jump and pullback sits on a fault line between confidence in a solid ethanol producer and cooler sentiment around what its earnings are worth. Is the current P/E simply catching up to reality?
Price-to-Earnings of 12.2x: Is it justified?
On simple numbers alone, REX American Resources looks cheap against its peers, with a P/E of 12.2x at a last close of $44.25, while recent returns have beaten both the wider US market and the Oil and Gas sector.
The P/E metric compares the share price with earnings per share and gives a quick read on how much investors are willing to pay for each dollar of profit. For a producer like REX American Resources, where earnings quality is flagged as high and profit margins are currently 17.6%, that earnings yardstick carries real weight for valuation work.
REX is described as good value on this measure when lined up against the US Oil and Gas industry average P/E of 13.2x. The gap to the immediate peer group is even wider, with the peer average at 27.2x. That difference suggests the market is attaching a lower price tag to REX American Resources earnings despite strong recent profit growth of 134.6% over the past year and earnings growth over five years of 21.7% per year, so investors are paying far less for each dollar of profit than for many comparable stocks.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 12.2x (UNDERVALUED)
Still, REX American Resources faces real pressure points, including ethanol price volatility and reliance on US fuel and feed demand, which may act as potential brakes on the story.
Find out about the key risks to this REX American Resources narrative.
Another view on REX American Resources
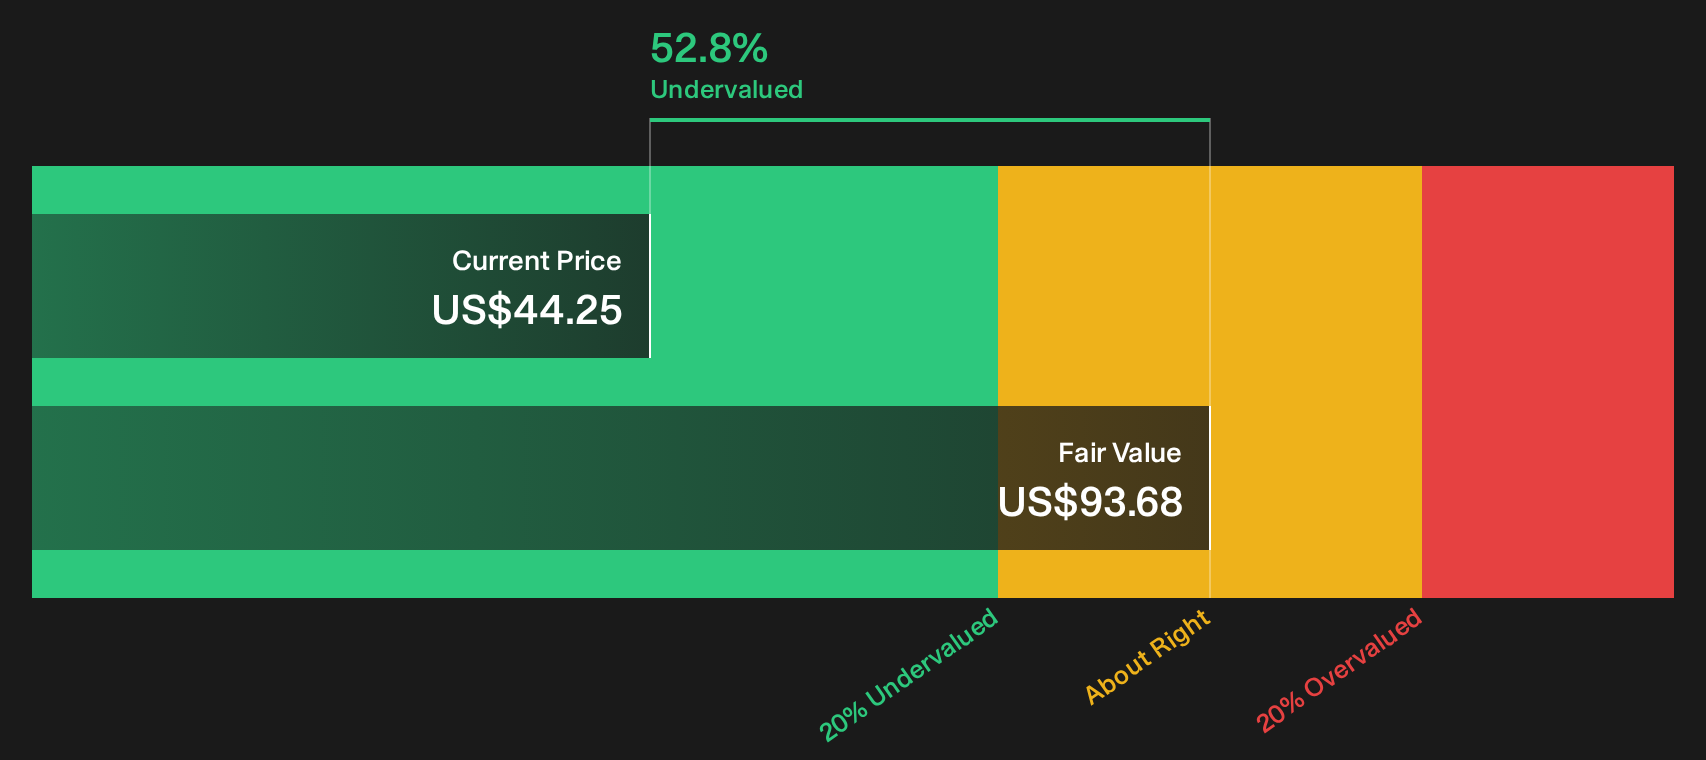
The multiple story says REX American Resources looks inexpensive. A different lens tells a similar story. Our DCF model estimates future cash flows at $93.68 per share, against the current $44.25 price, which points to the stock trading well below that implied value.
Investors who lean on cash flow based tools may treat this as a second opinion rather than a verdict. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out REX American Resources for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around REX American Resources in this piece may feel cautiously optimistic, so move quickly to weigh the evidence and settle on your own call. To see what investors are already optimistic about, review the 2 key rewards.
Looking for more investment ideas beyond REX American Resources?
If REX American Resources has sharpened your focus on valuation and quality, broaden your watchlist now so you do not overlook other compelling setups.
- Hunt for potential bargains by reviewing companies that screen as 29 high quality undervalued stocks based on both fundamentals and price.
- Prioritise resilience by scanning a list of solid balance sheet and fundamentals (23 results) so you can focus on businesses with financial strength front and centre.
- Get ahead of the crowd by zeroing in on a 16 high quality undiscovered gems before they sit firmly on everyone else's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com