
Is Wheaton Precious Metals (TSX:WPM) Still Below Fair Value As Earnings And Cash Flow Impress?
Why Wheaton Precious Metals Is Back In Focus
Wheaton Precious Metals (TSX:WPM) is back on investor radars after recent commentary linked its share price strength to a mix of solid earnings, healthier free cash flow, and a higher dividend.
Recent trading has reflected that story. Wheaton Precious Metals has a 90 day share price return of 35.05% and a year to date share price return of 33.86%. The 1 year total shareholder return of 46.35% and 5 year total shareholder return of 372.94% point to momentum building over both shorter and longer horizons.
Compare Wheaton Precious Metals’ momentum with other precious metal specialists by scanning our hand picked 36 elite gold producer stocks that share similar earnings strength, cash generation, and dividend profiles.
After that sharp move, Wheaton Precious Metals trades at a clear gap to both analyst targets and intrinsic value estimates. Is the current CA$216.78 price already generous, or is it still below where fair value clusters?
Most Popular Narrative: 9% Undervalued
Against the CA$216.78 share price, the most followed narrative for Wheaton Precious Metals points to a fair value estimate of CA$237.67, which frames the current move as a rerating rather than a fully stretched story.
Robust pipeline of new and expanding streaming agreements, including the ramp-up at Salobo III, commercial production at Blackwater, accelerated Phase 2/3 expansions at Blackwater, and new streams like Goose and Platreef, positions Wheaton for approximately 40% organic production growth by 2029, directly supporting higher future revenue and earnings growth.
See why 56 investors see Wheaton Precious Metals as 9% undervalued.
The narrative builds this fair value using a 7.98% discount rate and analyst assumptions for revenue and profit over the next few years, then discounts those cash flows back to today. That framework sits alongside the analyst target of roughly CA$244.61, which is about 12.8% above the latest close, and together they form a valuation band that many investors monitor when weighing the recent share price strength.
Result: Fair Value of CA$237.67 (UNDERVALUED)
Still, the Wheaton Precious Metals narrative could be knocked off course if competition for new streams squeezes deal economics, or if higher global minimum taxes drag on future cash flows.
Find out about the key risks to this Wheaton Precious Metals narrative.
Another View On Wheaton Precious Metals’ Valuation
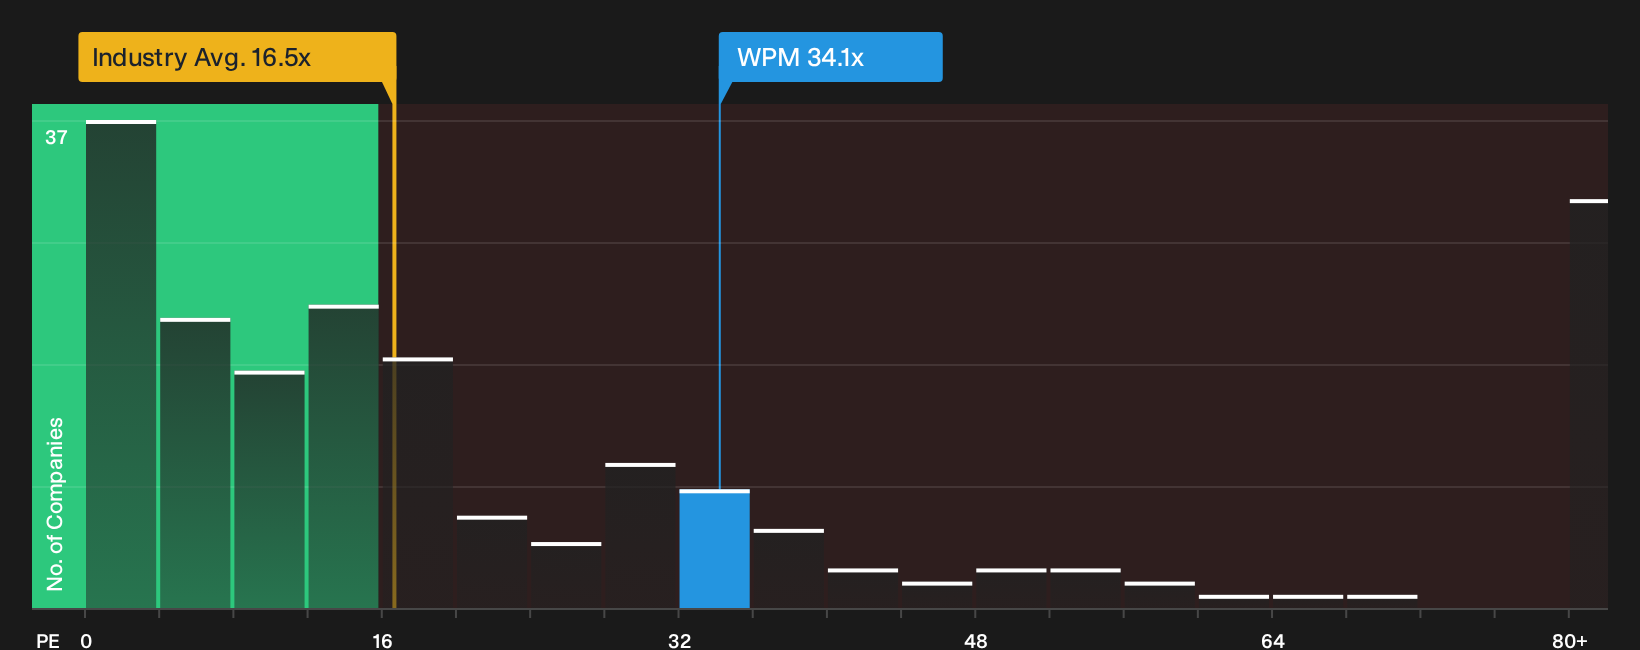
The story shifts once the focus moves from discounted cash flows to what the market is actually paying for Wheaton Precious Metals today. The stock trades on a P/E of 34.1x, which is more than double the Canadian Metals and Mining industry at 16.5x and well above peer averages at 18x.
The fair ratio sits at 19.1x, far below the current multiple. That gap suggests investors are already paying a heavy premium for the quality of Wheaton Precious Metals, which raises a simple question: How much optimism are you comfortable underwriting at this price?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of optimism has already been priced into Wheaton Precious Metals, and some clear concerns sit alongside it. Move quickly and test the numbers yourself against your own risk tolerance. To see how the positives stack up against the potential red flags in one place, review the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Wheaton Precious Metals?
If Wheaton Precious Metals has sharpened your appetite for quality opportunities, do not stop here. Put the same discipline to work across other ideas worth your time.
- Target resilient balance sheets and fundamentals by scanning our list of solid balance sheet and fundamentals (7 results) that can help anchor your portfolio when conditions turn choppy.
- Hunt for mispriced quality by reviewing the 7 high quality undervalued stocks that combine stronger fundamentals with prices that still trail underlying business strength.
- Spot earlier stage potential by tracking the 17 elite penny stocks with strong financials that pair higher risk with business models you can actually assess on the numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com