
Monolithisch India And 2 Other Indian Growth Stocks To Own
Indian inflation pressures are building again, according to recent commentary from Crisil, which keeps the focus firmly on companies that can grow earnings without relying on cheap money. That is where financially sound, faster growing Indian stocks come into play. Investors looking for potential long term compounding stories may find this especially interesting. This article highlights three such candidates from our growth focused stock filter.
The three stocks below are just a starting sample from this healthy high growth potential theme. The full screen surfaced 136 more companies with equally compelling narratives that are not covered here.
If you want to identify and analyze those additional ideas with the same filter that underpins this article, head straight into the Healthy high growth potential screener.
Monolithisch India (NSEI:MONOLITH)
Monolithisch India is a specialist supplier of ramming mass, a heat resistant lining material for induction furnaces used in steel, metallurgy and foundry plants, which directly ties its fortunes to heavy industry production. It generated about ₹1,538 million from ramming mass and related products and carries a market value of roughly ₹27.9 billion.
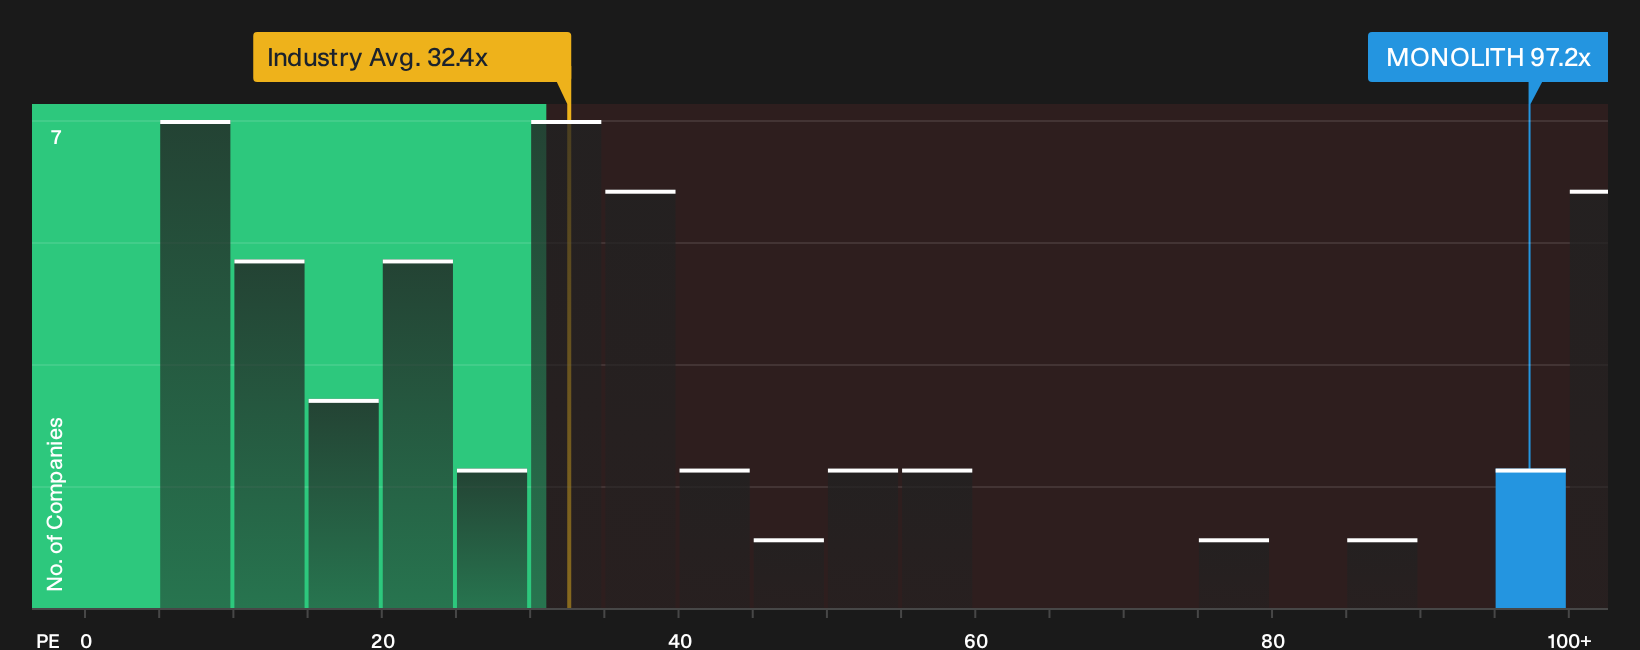
Earnings for Monolithisch India are forecast to grow 35.58% a year, with revenue expected to rise 35.4% annually and a recent Q1 2026 net profit of ₹100.71 million from higher ramming mass demand. That growth profile sits alongside a rich 97.2x P/E, which makes the outcome highly sensitive to one unseen pressure on future pricing power.
That sensitivity makes it worth reviewing the full analysis report for Monolithisch India to see what could either compress that multiple or justify it.
Timex Group India (BSE:500414)
Timex Group India designs, manufactures, and sells branded wristwatches across India and overseas, which is the kind of branded consumer product business analysts link to the screener’s earnings growth theme. It generated about ₹8,486 million from watches and after sales services and carries a market value near ₹71 billion.
Timex Group India lines up with the screener through strong earnings expectations, with analysts projecting about 31.8% annual profit growth and 24.8% revenue expansion over the next 3 years. Recent Q1 FY2027 results show higher sales and net income. This keeps attention on how far margins can stretch if one shifting pressure on profitability holds in their favor.
If that margin trend is what you are watching, go straight to the analysis report for Timex Group India to see where Timex Group India’s pricing power could really be tested.

Cemindia Projects (BSE:509496)
Cemindia Projects runs large marine and heavy civil concrete contracts that fit the Healthy high growth potential theme, with its ₹102.1 billion construction arm in India feeding the earnings engine and supported by a roughly ₹226.6 billion market value.
Cemindia Projects brings together complex marine works and broader infrastructure jobs in a way that fits the screener’s focus on strong earnings momentum and solid financial footing, while also giving investors exposure to long duration contracts that can compound over multiple project cycles.
"A robust pipeline of opportunities (₹87,000 to ₹90,000 crore), driven by increased government and private investment in transport, water, and logistics infrastructure, increases visibility for sustained order inflow, creating a strong runway for topline growth."
What happens if a single pressure on future profitability shifts just as that pipeline of work starts to translate into higher reported earnings?
If that profit pressure is what you are weighing up, read the full narrative for Cemindia Projects to see how Cemindia Projects’ order book, risks, and execution could be decoupling.

Seeking Fresh Alternatives For Your Curiosity?
Fresh opportunities do not stay under the radar for long. Strong ideas can gain momentum fast once the crowd catches on. Scan these candidates while it matters and consider them at an early stage.
- Spot income workhorses built for reliability and use the 159 dividend fortresses to find payouts that could help steady your portfolio before yields start dropping.
- Track future facing infrastructure as AI spending continues to grow and run through the 86 AI infrastructure stocks while these picks are still under the radar for now.
- Target metal producers that could benefit if demand increases and filter the field with the 17 top copper producer stocks ahead of any significant price moves.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com