
Asian Stocks Estimated To Be Undervalued In September 2026
As of September 2026, the Asian markets are navigating a complex landscape marked by rising interest rates and geopolitical tensions, with recent rate hikes by the Bank of Japan adding to the cautious sentiment. Amidst these challenges, investors are increasingly focused on identifying undervalued stocks that may offer potential opportunities for growth despite broader market uncertainties. In this context, understanding what constitutes an undervalued stock—such as strong fundamentals or resilience in volatile conditions—can be crucial for making informed investment decisions in Asia's diverse economic environment.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Shizuki Electric (TSE:6994) | ¥1208.00 | ¥2298.03 | 47.4% |
| Rakus (TSE:3923) | ¥1082.00 | ¥2063.55 | 47.6% |
| PAL GROUP Holdings (TSE:2726) | ¥1486.00 | ¥2869.67 | 48.2% |
| Niterra (TSE:5334) | ¥7218.00 | ¥13807.95 | 47.7% |
| HD Hyundai Energy SolutionsLtd (KOSE:A322000) | ₩116800.00 | ₩222309.08 | 47.5% |
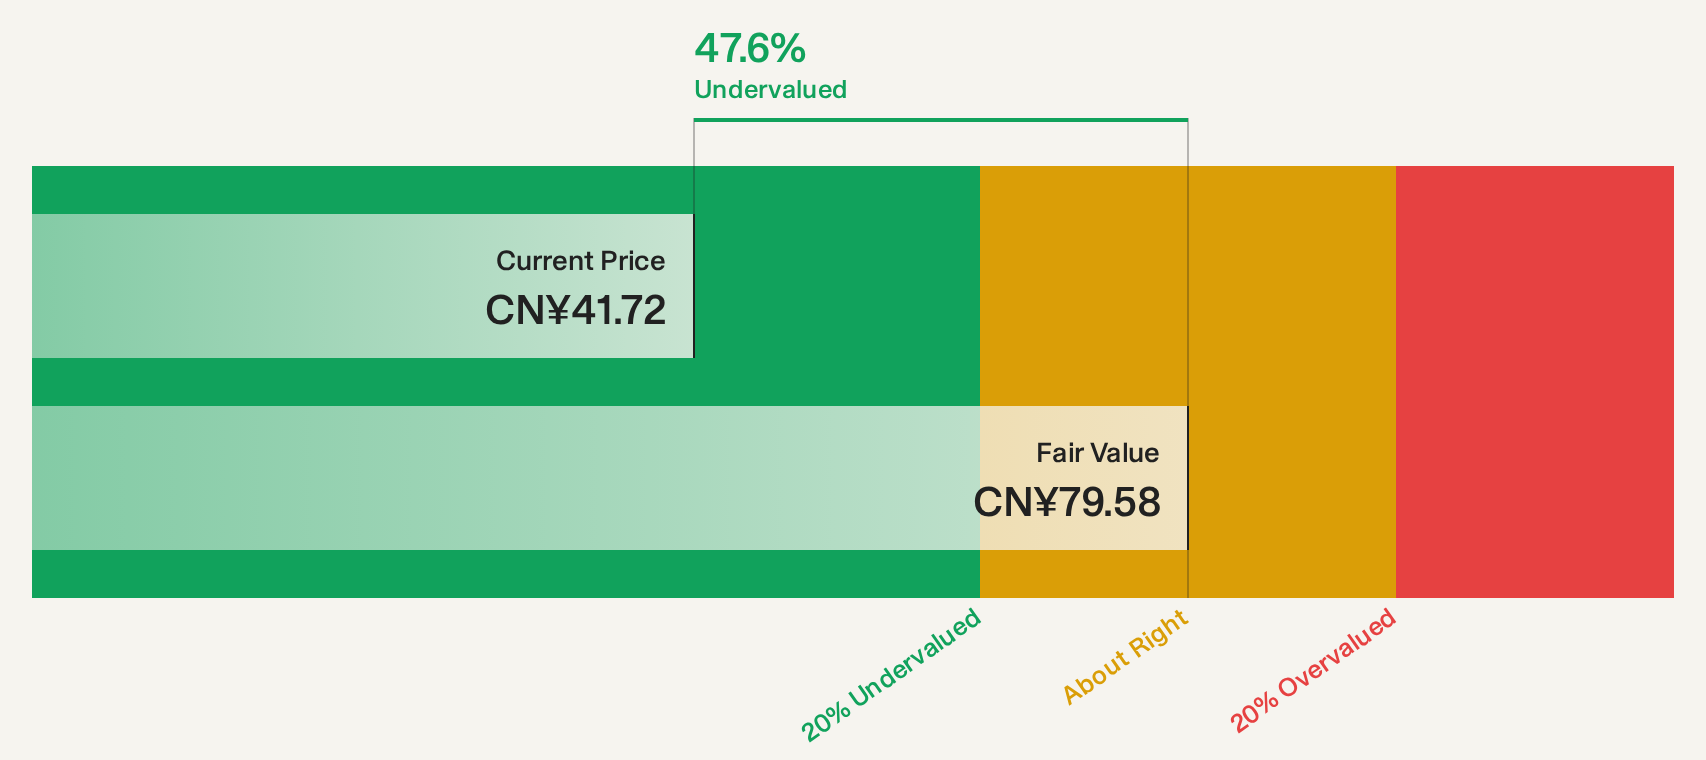
| Double Medical Technology (SZSE:002901) | CN¥40.57 | CN¥79.60 | 49% |
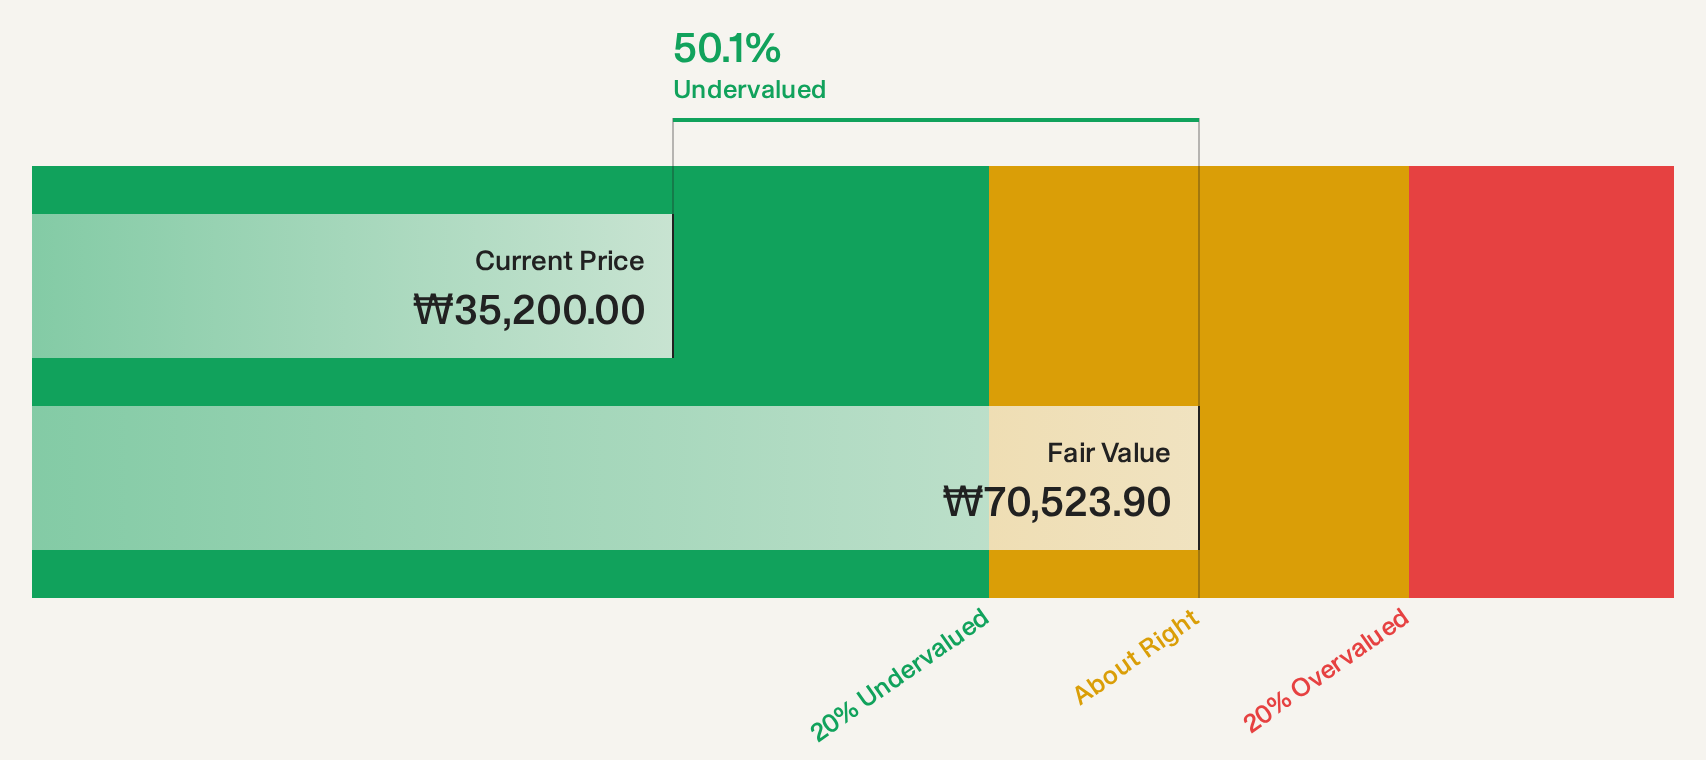
| Dongwon Industries (KOSE:A006040) | ₩35200.00 | ₩70372.87 | 50% |
| Cheil Worldwide (KOSE:A030000) | ₩17630.00 | ₩33818.96 | 47.9% |
| AK Medical Holdings (SEHK:1789) | HK$4.935 | HK$9.55 | 48.3% |
| 3SBio (SEHK:1530) | HK$16.77 | HK$32.14 | 47.8% |
Here's a peek at a few of the choices from the screener.
Dongwon Industries (KOSE:A006040)
Overview: Dongwon Industries Co., Ltd. operates in the marine and fisheries, distribution, and logistics sectors both in South Korea and internationally, with a market cap of ₩1.55 trillion.
Operations: Revenue segments for the company include marine and fisheries, distribution, and logistics operations across domestic and international markets.
Estimated Discount To Fair Value: 50%
Dongwon Industries is trading at ₩35,200, significantly below its estimated future cash flow value of ₩70,372.87, indicating it may be undervalued based on cash flows. Despite a high debt level and forecasted earnings decline of 34.5% annually over the next three years, recent earnings show strong growth with net income rising to KRW 101 billion in Q2 2026 from KRW 82 billion a year ago.
- In light of our recent growth report, it seems possible that Dongwon Industries' financial performance will exceed current levels.
- Click here and access our complete balance sheet health report to understand the dynamics of Dongwon Industries.
Maoyan Entertainment (SEHK:1896)
Overview: Maoyan Entertainment is an investment holding company that operates a platform in the entertainment industry in the People’s Republic of China, with a market cap of HK$4.66 billion.
Operations: The company's revenue is primarily derived from its Business Services segment, which generated CN¥3.95 billion.
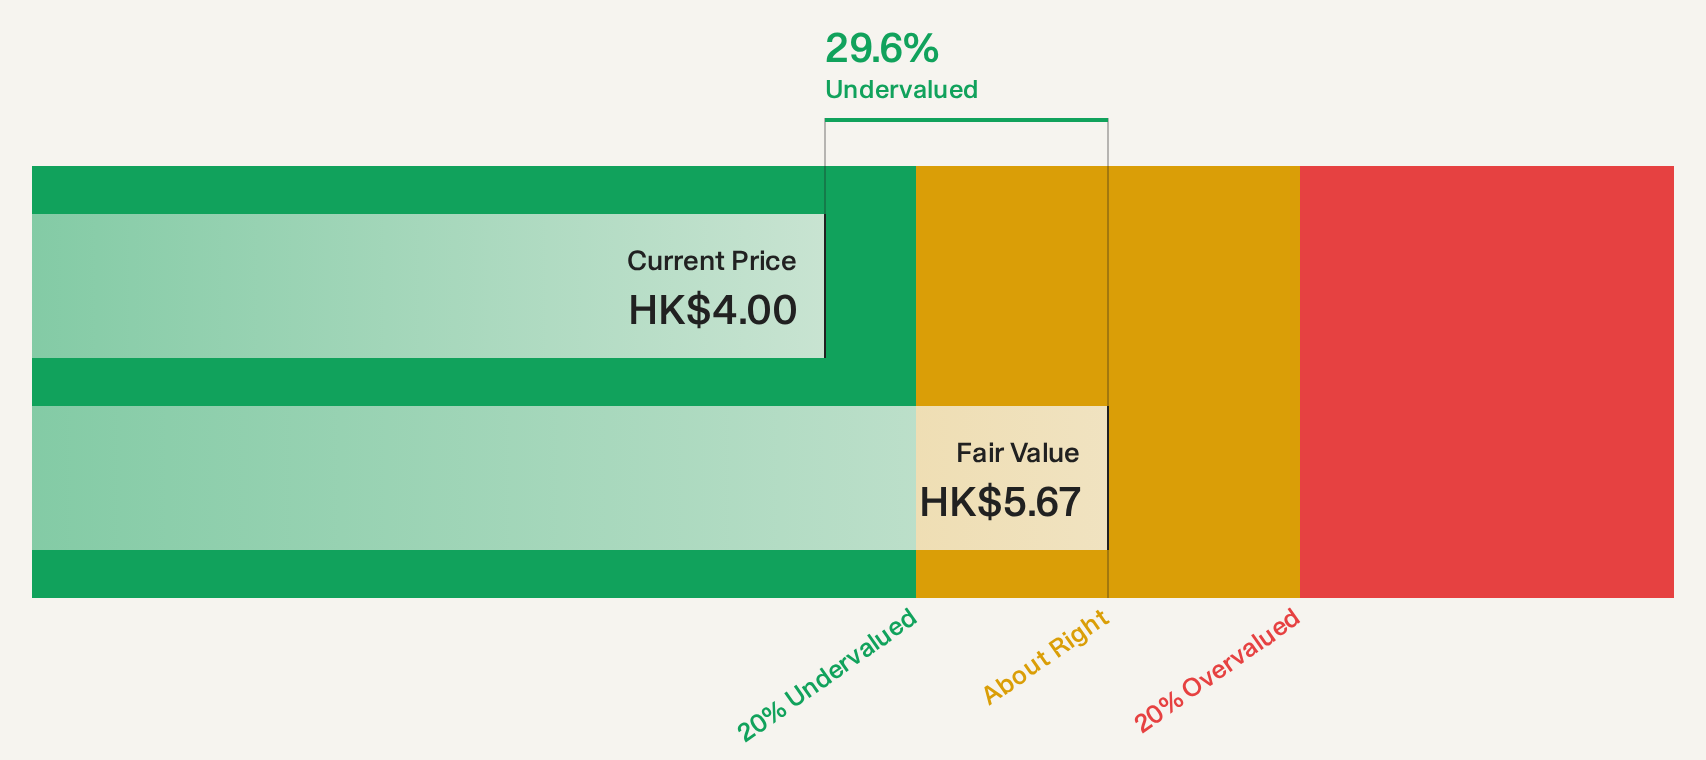
Estimated Discount To Fair Value: 29.3%
Maoyan Entertainment is trading at HK$4.01, below its estimated future cash flow value of HK$5.67, suggesting potential undervaluation based on cash flows. Despite a challenging first half of 2026 with a net loss of CNY 27.59 million and decreased revenue due to the Chinese film market downturn, earnings are forecasted to grow significantly over the next three years. However, revenue growth is expected to lag behind the Hong Kong market average.
- The growth report we've compiled suggests that Maoyan Entertainment's future prospects could be on the up.
- Dive into the specifics of Maoyan Entertainment here with our thorough financial health report.
Double Medical Technology (SZSE:002901)
Overview: Double Medical Technology Inc. is involved in the research, development, production, and sale of high-value medical consumables in China with a market cap of CN¥16.41 billion.
Operations: The company's revenue is primarily derived from its Trauma Product segment at CN¥1.04 billion, followed by Spine Products at CN¥513.09 million, Minimally Invasive Surgery Products at CN¥426.57 million, Joint Products at CN¥239.18 million, Neurosurgical Products at CN¥117.82 million, and Dental Products at CN¥76.35 million.
Estimated Discount To Fair Value: 49%
Double Medical Technology, trading at CN¥40.57, is valued below its future cash flow estimate of CN¥79.6, indicating potential undervaluation. Despite a 53.1% earnings growth last year and a recent buyback of 4.39 million shares for CN¥180.41 million, the company faces challenges with slower projected earnings (7.9%) and revenue growth (13.2%) compared to the broader Chinese market averages of 27.6% and 17.5%, respectively.
- Our comprehensive growth report raises the possibility that Double Medical Technology is poised for substantial financial growth.
- Navigate through the intricacies of Double Medical Technology with our comprehensive financial health report here.
Next Steps
- Dive into all 77 of the Undervalued Asian Stocks Based On Cash Flows we have identified here.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Take control of your financial future using Simply Wall St, offering free, in-depth knowledge of international markets to every investor.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com