
Fuji (TSE:6134) Could Be 31% Below Fair Value Following FTSE All World Inclusion
Index inclusion puts Fuji on more global radars
Fuji (TSE:6134) has been added to the FTSE All-World Index in USD terms, a move that can draw fresh attention from index trackers and large institutional investors.
Short term trading has been lively, with Fuji’s 1-day share price return of 4.54% and 7-day share price return of 6.10% coming after a 90-day share price decline of 11.91%. The 1-year total shareholder return of 162.23% points to longer term momentum that index inclusion may now be amplifying.
Scan other global industrials riding similar index-driven attention with our hand picked list of solid balance sheet and fundamentals (21 results) to see how Fuji compares on fundamental strength.
Fuji now trades below both analyst targets and one intrinsic value estimate, even after the index driven jump. Is that a genuine margin of safety, or a warning that the market smells risk?
Price-to-earnings of 27.8x for Fuji: Is it justified?
Fuji closed at ¥7,179 while carrying a P/E ratio of 27.8x, a level that places the stock at a premium compared with both its Machinery peers and the broader Japan market.
The P/E multiple benchmarks what buyers are willing to pay today for each unit of earnings. For an industrial robotics and machine tools specialist like Fuji, that figure often reflects expectations around future profit growth, earnings quality and how durable those cash flows might be across product cycles.
Forecasts in the data point to earnings growth of 25.5% per year and revenue growth of 12.7% per year, with margins currently at 11.4% and higher than last year. Taken together with high quality earnings and profit growth of 62.5% over the past year, the current P/E of 27.8x indicates that the market is pricing in stronger profitability than the Machinery industry average. The fair P/E of 29.7x also suggests the ratio could reasonably skew higher if those expectations are met.
The gap to sector benchmarks is wide. The P/E of 27.8x is described as expensive versus the Japan Machinery industry average of 13.3x and also higher than the 22x peer average, which points to investors paying a clear premium for Fuji compared to similar companies.
Explore the SWS fair ratio for Fuji.
Result: Price-to-earnings of 27.8x (OVERVALUED).
Still, Fuji faces real pressure points if global electronics demand cools or if China and broader Asian orders wobble. This could test today’s premium P/E and sentiment.
Find out about the key risks to this Fuji narrative.
Another view on Fuji’s value
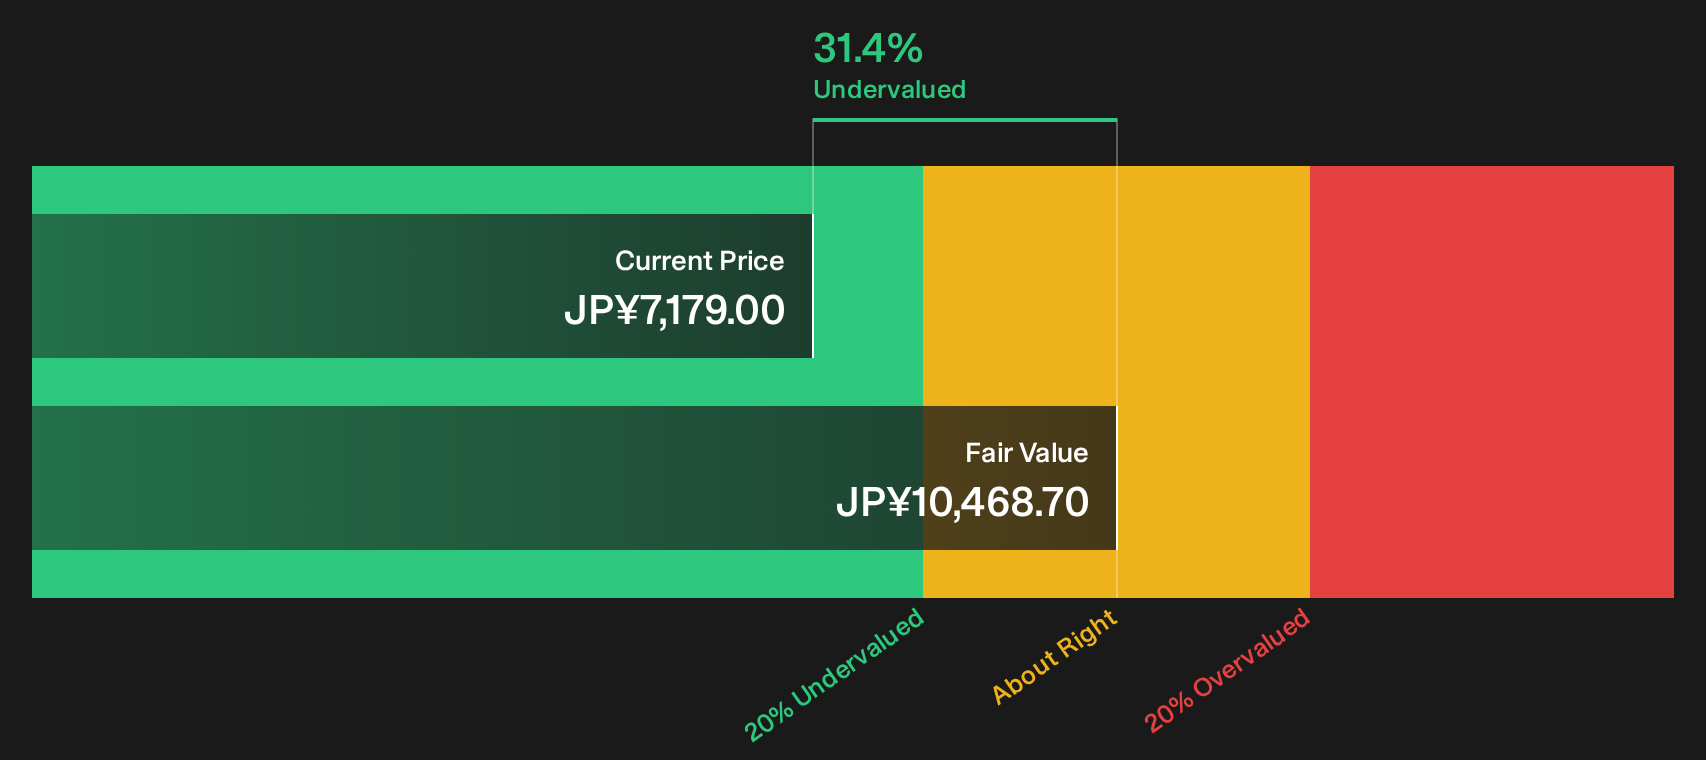
The earnings multiple paints Fuji as expensive, yet the SWS DCF model offers a very different angle. On that framework, the shares at ¥7,179 are trading about 31.4% below an estimated future cash flow value of ¥10,468.7, which frames the current price as a discount rather than a premium. Which lens do you trust more when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fuji for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Fuji’s valuation and risk profile make this a moment to move fast and rely on your own homework rather than headlines. Weigh both sides of the story by reviewing the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Fuji?
If Fuji has your attention today, do not stop there. Broaden your watchlist with other opportunities that match the kind of discipline you want in a portfolio.
- Target potential mispricings by scanning a curated set of companies that combine quality fundamentals with discounted valuations through the 17 high quality undervalued stocks.
- Prioritize stability and capital strength by checking companies with cleaner balance sheets and resilient financial profiles using the list of solid balance sheet and fundamentals (21 results).
- Hunt for lesser known opportunities with strong underlying metrics by reviewing the 75 high quality undiscovered gems before others catch on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com