
Oversea-Chinese Banking (SGX:O39) Could Be 18% Overvalued After Its Recent Rally
Oversea-Chinese Banking (SGX:O39) has attracted investor attention after recent share price moves, with the stock closing at S$32.14 on 14 September 2026. The bank’s valuation metrics and business mix now draw closer scrutiny.
Recent price action suggests momentum in Oversea-Chinese Banking is building, with a 1-day share price return of 1.48% and a 7-day gain of 3.68%. The picture is stronger over longer horizons, with a 90-day share price return of 28.82% and a year-to-date rise of 61.91%. The 1-year total shareholder return of 103.66% and 5-year total shareholder return of 266.26% point to investors reassessing both growth potential and risk across different timeframes.
Scan for other banks showing similar momentum and financial scale to Oversea-Chinese Banking by zeroing in on our curated list of solid balance sheet and fundamentals (197 results).
Oversea-Chinese Banking has produced strong shareholder returns and runs a sizeable, diversified franchise, yet the recent surge in the share price raises a sharper issue. Are you now paying a fair price for that strength?
Most Popular Narrative: 18% Overvalued
Against a last close of S$32.14, the most followed narrative pegs Oversea-Chinese Banking's fair value at S$27.18 using a 6.74% discount rate. That gap raises a simple question for investors weighing the recent rally: are expectations already well ahead of the modelled fundamentals?
The expansion of OCBC's wealth management platform and continued strong net new money inflows (SGD 9 billion in 1H25), supported by a growing affluent and middle class in Southeast Asia, position the bank for long-term, higher-margin fee income growth even as net interest margins face cyclical headwinds. This is likely to support stronger earnings resilience and rising net margins over time.
See why 93 investors see Oversea-Chinese Banking as 18% overvalued.
Result: Fair Value of S$27.18 (OVERVALUED)
Still, Oversea-Chinese Banking's narrative could be challenged if interest rate cuts compress net interest margins or if wealth and insurance income swing sharply with market volatility.
Find out about the key risks to this Oversea-Chinese Banking narrative.
Another View: Oversea-Chinese Banking On Cash Flows
The analyst narrative tags Oversea-Chinese Banking as around 18% overvalued at S$27.18, yet our DCF model points in the opposite direction. On a cash flow basis, the shares trade below an estimated future value of S$39.20. This frames the recent rally as a possible discount rather than excess. Which story do you think better fits your own assumptions?
To unpack how this cash flow view is built and where the key swing factors sit, take a closer look at the SWS DCF model, step by step, through Look into how the SWS DCF model arrives at its fair value..
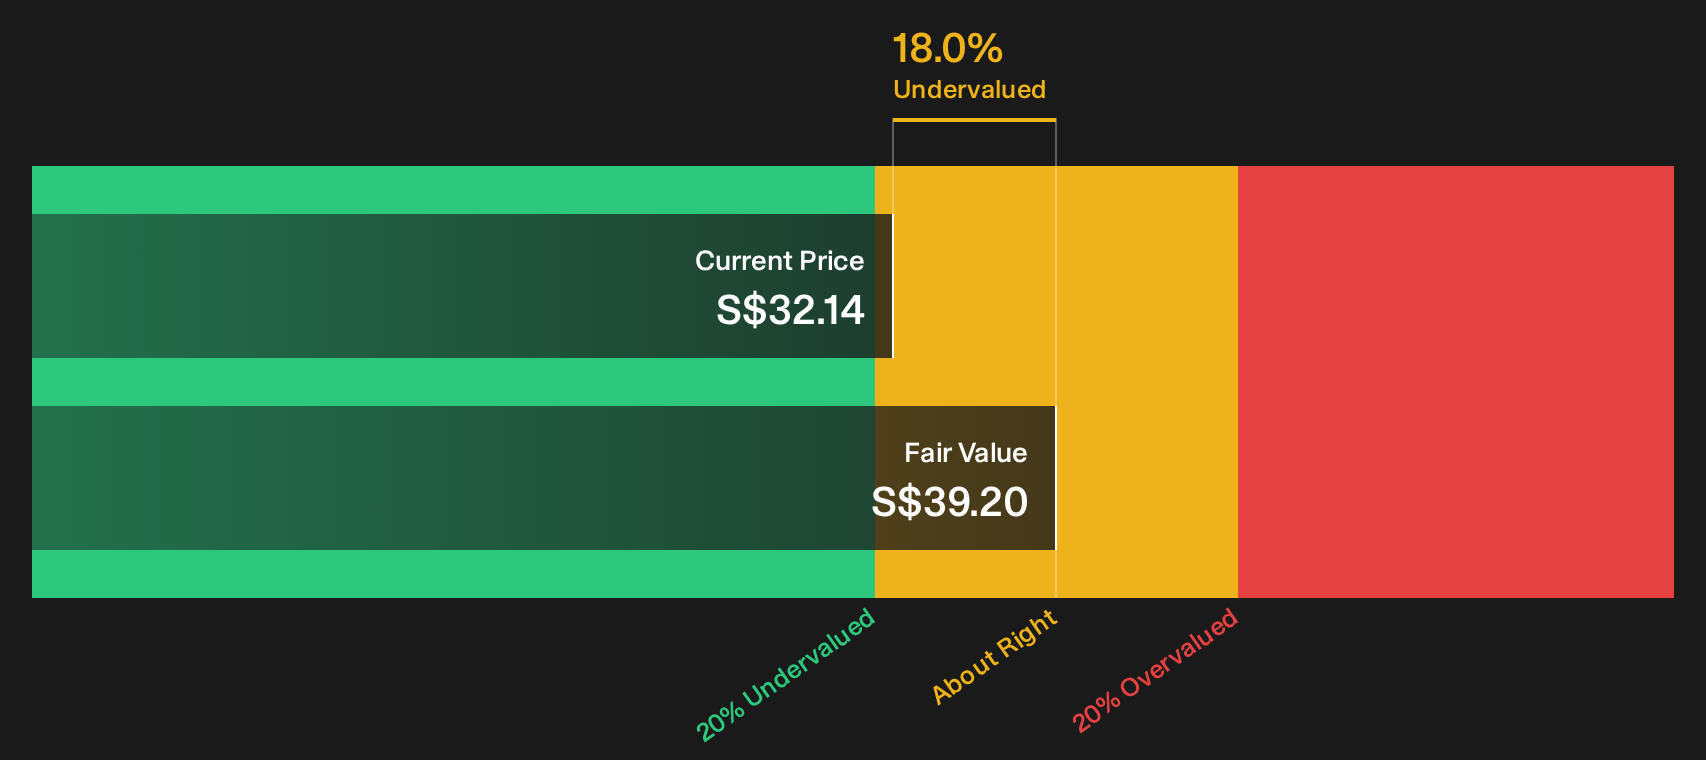
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Oversea-Chinese Banking for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 170 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Views on Oversea-Chinese Banking are clearly split, so use that tension as a prompt to move fast, review the data, and decide where you stand. To understand both the concerns and the upside being discussed around the stock, start with the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Oversea-Chinese Banking?
Do not stop your research at Oversea-Chinese Banking. Broaden your watchlist with a mix of resilient balance sheets, value ideas, and income opportunities.
- Spot fresh value candidates early by scanning our 616 high quality undiscovered gems before they attract wider attention.
- Lock in your focus on sturdier businesses using the 230 resilient stocks with low risk scores so sharp drawdowns do not catch you off guard.
- Build a watchlist of potential income workhorses with the 159 dividend fortresses and avoid missing yield opportunities that match your comfort level.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com