
3 U.S. Energy Infrastructure Stocks Tied To GOP Deregulation Worth Watching
Election cash is already reshaping the policy conversation, and utilities tied to regulated pipes and power lines sit close to that fault line. A large Republican funding edge, plus new freedom for coordinated party spending, has raised the stakes for potential deregulation and permitting shifts. This piece explains how that backdrop connects to three U.S. regulated utilities and energy infrastructure stocks that are exposed to these political currents, and why their stories may be relevant when you evaluate your portfolio.
The stocks discussed below are a small sample, and the full screen surfaced 17 more U.S. regulated utilities and energy infrastructure companies with equally compelling policy stories around pipes, power lines, and potential GOP deregulation. To identify and analyze the highest-conviction ideas from that broader universe, head straight into the U.S. Regulated Utilities and Energy Infrastructure Benefiting from Potential GOP Deregulation screener.
Antero Midstream (AM)
Antero Midstream runs gathering pipelines, processing plants, and water handling infrastructure in the Appalachian Basin, a midstream hub that is front and center for U.S. pipeline permitting debates. The business generated about US$1.0b from Gathering and Processing and US$278 million from Water Handling, with a market value near US$10.1b.
Antero Midstream gives you direct exposure to regulated pipelines and water systems serving Appalachian gas production, the kind of midstream asset base investors watch when GOP-leaning deregulation could speed approvals. The stock offers income and infrastructure scale, while margins and dividend support hinge on what happens when one unseen pressure on funding costs shifts.
When that funding pressure shifts, review the Antero Midstream financial health report to see how Antero Midstream’s balance sheet could amplify or cushion the next policy-driven move.

World Kinect (WKC)
World Kinect is an energy management specialist in the screener because part of its fuel distribution activity is directly exposed to U.S. regulation on environmental and fuel standards, which can shift the economics of its aviation, land, and marine businesses.
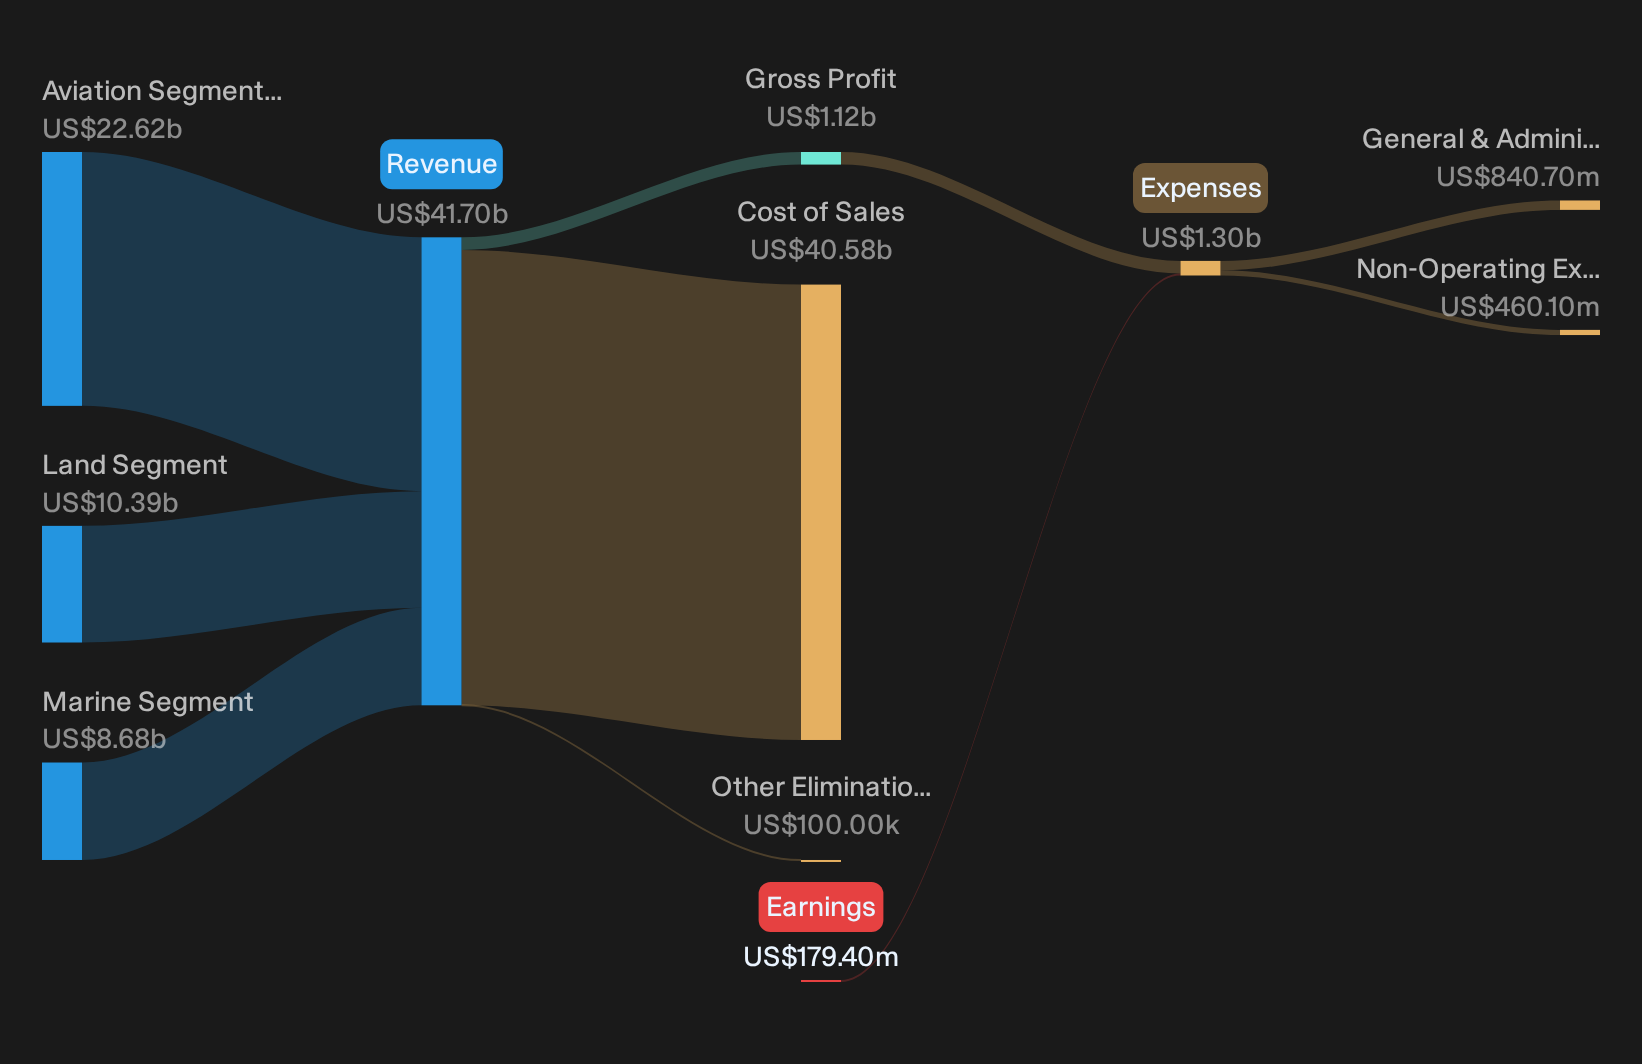
World Kinect runs a global fuel and energy platform, supplying jet fuel, liquid fuels, natural gas, and marine fuels, with revenue led by Aviation at about US$22.6b, followed by Land at roughly US$10.4b and Marine at around US$8.7b. The stock carries a market value near US$1.8b.
Investors looking at World Kinect in this policy-sensitive screen are weighing a fuel distributor that is trying to reposition itself around cleaner energy and tighter cost control as campaign cash raises the odds of looser rules for traditional fuels.
"The company is well positioned to participate in the global demand for renewable fuels and carbon reduction solutions, having already built operational capabilities and customer relationships in renewables. Management's capital allocation, supported by recent divestitures and increased cash flow, places World Kinect in a position to acquire technology-driven or renewable energy assets at distressed prices while some competitors hesitate."
One potential consideration for investors is how a shift in its fuel mix and contract structure could change the way each additional dollar of sales affects profit margins.
That shift in economics is exactly where the story gets interesting, and the full narrative for World Kinect shows how World Kinect could accelerate or stall as policy and fuel mix evolve.
Hess Midstream (HESM)
Hess Midstream runs U.S. oil, gas, and water pipelines tied to federal and state permitting, fitting squarely into this regulated midstream screen. It earned about US$858 million from Gathering, US$614 million from Processing and Storage, and US$142 million from Terminaling and Export, giving the stock a roughly US$8.3b market value.
Hess Midstream gives you direct exposure to U.S. pipeline and storage projects where permitting rules and environmental policy shape how quickly new connections move from plan to reality. The business combines fee-based cash flows, a high dividend yield, and significant leverage, so what happens when one unseen pressure on policy and funding costs moves even slightly could matter a lot for income and valuation.
That kind of sensitivity to policy and funding makes it worth reading the 3 key rewards and 2 important warning signs before those cash flows start decoupling from the headline story.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. The strongest stories can start breaking out while others are still reading last week's headlines. Keep your curiosity flying while it matters and get in early.
- Spot resilient cash generators before momentum traders arrive by scanning the list of solid balance sheet and fundamentals (23 results) that keeps weaker fundamentals from crowding your watchlist.
- Target durable income plays while yields are still under the radar for now by reviewing the 7 dividend fortresses that focuses on higher-yield payers with staying power.
- Chase next-wave infrastructure momentum before it is fully priced by checking the 40 power grid technology and infrastructure stocks curated around companies tied to grid upgrades and reliability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com