
Is REA Group (ASX:REA) Fairly Valued Following Its ACCC Resolution?
Regulatory outcome reshapes REA Group’s commercial settings
REA Group (ASX:REA) has entered a court enforceable undertaking with the ACCC, resolving competition concerns and committing to more flexible listing requirements and downgrade options for real estate agency clients on realestate.com.au.
REA Group’s share price has retreated 10.73% over the past month despite a 19.45% 90 day share price return, while the 1 year total shareholder return has declined 31.06%. This points to fading momentum after an earlier rebound.
The A$157.17 share price and recent pullback suggest investors are still recalibrating how much regulatory risk to price in after the ACCC process. At the same time, the resolution removed the immediate threat of legal action and kept the commercial model intact.
Spot opportunities around REA Group's regulatory reset by scanning a curated field of property-focused platforms and related plays through 16 high quality undiscovered gems.REA Group’s pullback and fresh ACCC settings put you at a fork in the road. Is this A$157.17 level already fair, or is it worth holding fire for a cleaner entry as the valuation picture fills out next?
Most Popular Narrative: 6% Overvalued
According to the most followed REA Group narrative, the A$157.17 share price sits modestly above a fair value estimate of A$148, which leaves only a slim valuation gap for investors to work with.
Working IV ≈ AU$145 (centre of the legitimate cluster, asset-WACC DCF, own-history multiple, SOTP, with the book-anchored Montgomery and tangible-book methods shown but excluded). IV range AU$120–160. Downside floor (no-growth EPV) ~AU$55. Reverse-DCF check: the price implies ~8–9% long-run growth, below what the franchise has consistently delivered, no veto.
See why 10 investors see REA Group as 6% overvalued.
Result: Fair Value of A$148 (OVERVALUED)
Still, REA Group’s thesis leans heavily on pricing power and regulatory freedom, so any harsher ACCC remedy or slower listing volumes could quickly challenge this fair value story.
Find out about the key risks to this REA Group narrative.
Another take on REA Group’s valuation
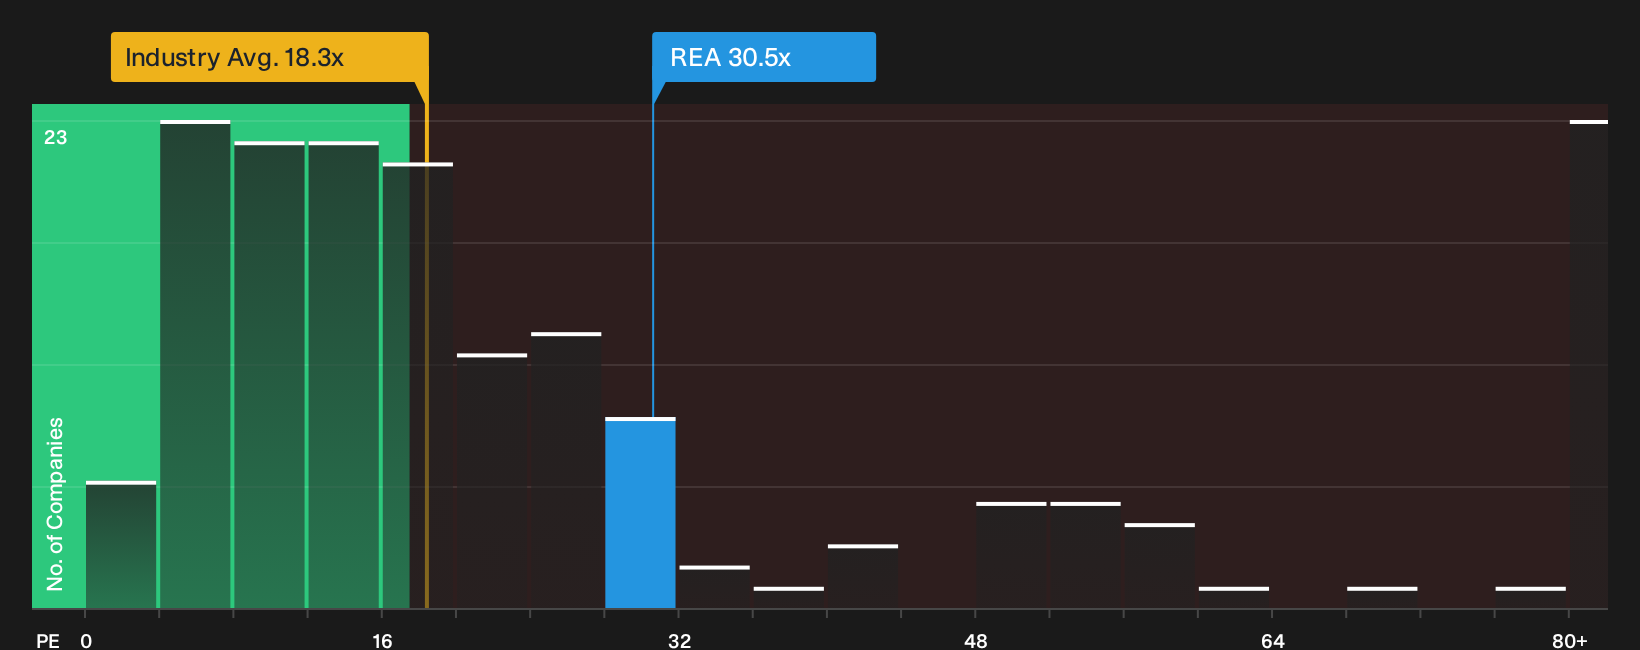
On earnings multiples, REA Group looks a bit richer than the headline “fair value A$148” narrative suggests. The stock trades on a P/E of 30.5x, which is slightly above the estimated fair ratio of 29.2x and well ahead of the global Interactive Media and Services average of 18.3x. That gap leaves less room for error if growth or pricing power disappoint.
For investors weighing that trade off between quality and price, the question is whether a premium of this size still feels comfortable once regulatory and competition risks are factored in, or whether there are cleaner opportunities elsewhere that offer more headroom as sentiment turns.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on REA Group’s pricing and regulatory setup can pull you in either direction, so move quickly and test the numbers yourself. To stress test your own view against the optimistic angles in the data, start by unpacking the 2 key rewards
Looking for more REA Group style investment ideas?
Do not stop your research at REA Group. Fresh ideas often come from comparing opportunities side by side, and missing that step can cost you real upside.
- Target resilient opportunities that aim to limit shocks by screening for 7 resilient stocks with low risk scores that might better match your comfort level.
- Hunt for pricing gaps by scanning a focused pool of 5 high quality undervalued stocks that pair stronger fundamentals with more breathing room on valuation.
- Prioritise financial strength by filtering for a list of solid balance sheet and fundamentals (12 results) and see which businesses back their story with sturdier foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com