
Lucid Group (LCID) Following Bolt Deal Faces A Fresh Valuation Test
Lucid Group (LCID) has partnered with Bolt to roll out SAE Level 4 autonomous mobility services across Europe, using its upcoming midsize platform and NVIDIA Hyperion based architecture.
Lucid Group shares trade at US$4.30 after a sharp 1-day share price return of 5.13% and a 7-day gain of 3.37%. However, the stock is still down 21.96% over 30 days and 61.43% year to date, while the 1-year total shareholder return has fallen 80.84%. This leaves the new Bolt partnership and the recent CFO transition sitting against a backdrop of longer term weakness that the market may reassess if it sees this European autonomous push as meaningfully changing Lucid's risk and growth profile.
Scan how Lucid Group’s autonomous push compares with other potential breakouts by reviewing a curated set of 17 high quality undiscovered gems in adjacent technologies and mobility platforms.
Lucid Group now combines a weak share price record with a fresh autonomous story and a sizeable analyst price gap. Does that balance of risk and potential upside still favour new buyers at this level once valuation is in focus?
Most Popular Narrative: 49% Undervalued
Lucid Group’s most followed narrative anchors on a fair value of $8.40 against a last close of $4.30. This frames the current Bolt and autonomy news inside a much larger long term upside thesis built on partnerships, new platforms and Saudi production.
The newly announced Uber and Nuro partnership, including a planned $300 million Uber investment and a commitment to deploy at least 20,000 Lucid Gravity vehicles as robotaxis over six years, is expected to open a large and fast-growing autonomous fleet market to Lucid, driving significant revenue expansion and potential margin improvement via technology licensing and high-volume fleet sales.
See why 184 investors see Lucid Group as 49% undervalued.
Result: Fair Value of $8.40 (UNDERVALUED)
Still, the Lucid Group story can break if heavy losses persist or if fresh capital raises and dilution outpace any benefits from partnerships and new platforms.
Find out about the key risks to this Lucid Group narrative.
Another View: Lucid Group Looks Expensive On Sales
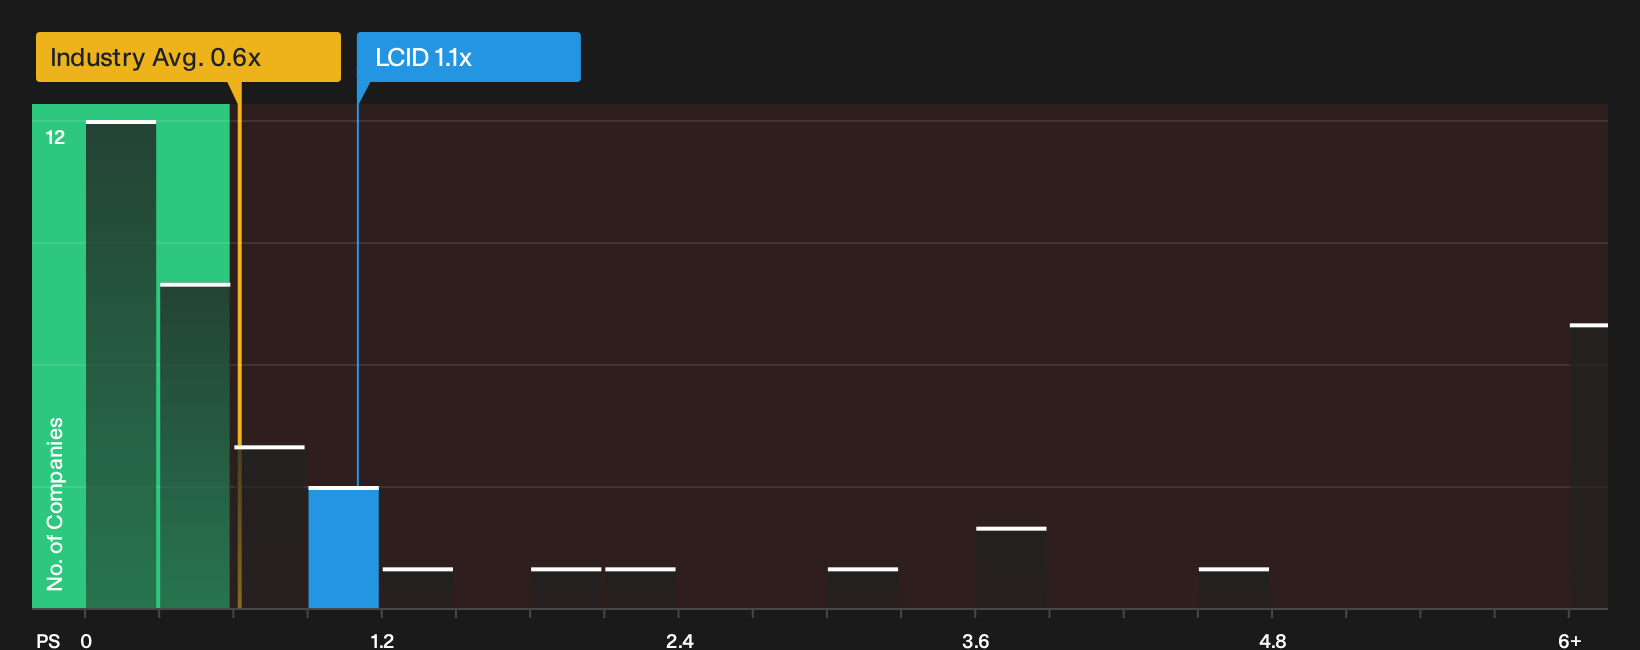
The fair value story around Lucid Group at $8.40 leans on long term growth and margin repair. A straight P/S check paints a tougher picture. The stock trades on 1.1x sales against 0.6x for the US Auto industry and 0.5x for peers, while the fair ratio sits at 0x. That gap points to clear valuation risk if revenue or profitability disappoint.
Before focusing only on the upside narrative, it is worth stress testing these assumptions against a simple multiples breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Lucid Group story today. If you want to move quickly and ground your own stance in data, start with the 1 key reward and 4 important warning signs.
Looking for more Lucid Group investment ideas?
Do not stop your research with Lucid Group alone. Broaden your watchlist with data-backed screens that highlight different kinds of opportunities you might otherwise miss.
- Target potential mispricings by running a focused search through 30 high quality undervalued stocks which combines solid financial profiles with attractive entry points.
- Prioritise resilience and capital protection by reviewing a curated 30 resilient stocks with low risk scores tailored to steadier balance sheets and lower overall risk scores.
- Strengthen your income stream by scanning 7 dividend fortresses that offers higher yields while aiming to keep payout quality in clear view.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com