
What Xero (ASX:XRO)'s SignWell Integration Means For Shareholders
- On 9 September 2026, SignWell Inc. announced a native integration with Xero Limited, allowing users to send Xero quotes and invoices for legally binding eSignatures directly from SignWell with synced audit trails and SOC 2 Type II-certified security.
- This link between Xero and SignWell tightens Xero’s role in day to day approval workflows, which may influence subscriber retention, ARPU potential, and how efficiently accountants and small businesses manage billing and compliance.
- We will now look at how this native SignWell integration could influence Xero's broader investment narrative around product depth and stickiness.
Xero Investment Narrative Recap
To own Xero, you need to believe its small business platform can keep attracting new users while convincing existing subscribers to pay for more tools over time. The SignWell integration fits that thesis by making approvals, quotes and invoicing feel more automated inside the core product. For near term share price moves, this looks incremental rather than a major catalyst.
The more immediate swing factors stay the same. You are still watching whether subscriber growth holds up as long idle accounts are removed, and how much pricing complexity weighs on ARPU. The bigger risk remains cost discipline, especially as hiring in higher cost markets and product expansion could pressure already lower profit margins.
The embedded bill payment solution looks closest in spirit to this SignWell tie up. Both push Xero deeper into day to day workflows that matter for cash collection and payables. When customers process payments and approvals inside the accounting platform, usage tends to become more frequent and the product is harder to switch away from.
That link to usage intensity is what matters for future catalysts. If embedded bill pay and workflow tools like SignWell drive more activity per subscriber, they can support the aim of balancing subscriber growth with healthier ARPU. Execution risk remains around communicating new bundles and price points clearly so that customers see value in the extra functionality rather than feeling pushed into higher tiers.
Xero Consensus Growth Assumptions
Xero's narrative projects NZ$5.2b revenue and NZ$632.1m earnings by 2029. This implies 23.9% yearly revenue growth and an earnings increase of roughly 3.8x from NZ$167.4m today.
Uncover why Xero's fair value indicates a 107% potential upside to its current price, which could close faster than many investors expect.
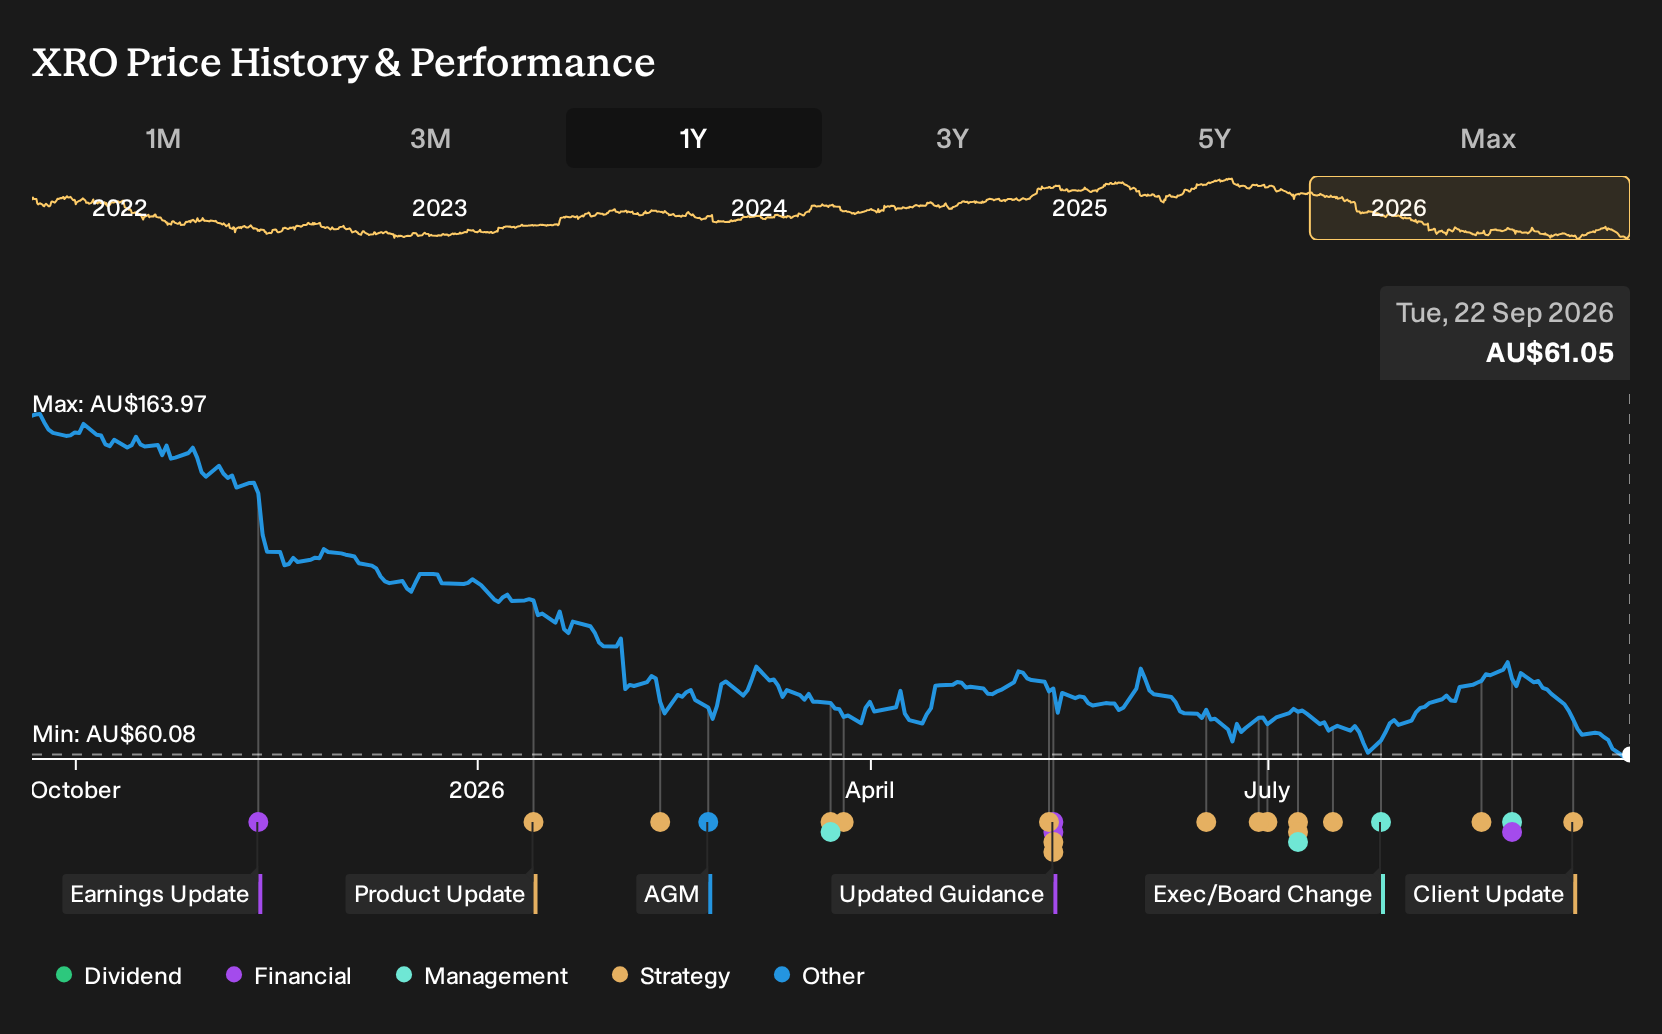
Exploring Other Perspectives
Some analysts see this SignWell move as a real test of the bullish workflow story around Xero. The most optimistic forecasts were already baking in NZ$6.2b of revenue and NZ$887.6m of earnings by 2029. You can now ask whether tighter approval flows justify that optimism or push you toward a different view.
Explore 7 other Xero fair value estimates, including one that suggests as much as 228% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Xero research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Xero. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Xero's overall financial health at a glance.
Looking for more investment ideas beyond Xero?
If the Xero story has sharpened your thinking about software, it can help to stress test that framework on other opportunities. The Simply Wall St Screener lets you scan the market through different lenses so you can line up a shortlist that fits your own risk tolerance and return goals.
- Focus on value by hunting for established businesses trading below their estimated worth with the help of our 5 high quality undervalued stocks that already clear high quality and balance sheet filters.
- Prioritise resilience and capital preservation by filtering for companies that score well on stability using a 7 resilient stocks with low risk scores tailored to lower volatility and stronger fundamentals.
- Cast a wider net for future favourites by using a 16 high quality undiscovered gems that spot financially solid stocks which are not yet widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com