
UK Chemical Shutdowns Could Lift Evonik Stock And European Chemical Shares
UK chemical plants going quiet is not just another gloomy headline about heavy industry. When Ineos moves to mothball three Hull facilities because gas is too expensive, capacity on one side of the market shrinks and pricing power can shift somewhere else. This article unpacks that story and walks through three large UK and European integrated chemical majors that screen as potential beneficiaries of tighter UK supply conditions.
The stocks covered below are only a starter set, and the full screen surfaced 7 more large-cap chemicals groups with equally compelling narratives that are not broken out in this article. To identify and analyze the broader opportunity across UK and European integrated producers that could benefit from tighter UK capacity, head straight to the UK & European Integrated Chemical Majors Benefiting from UK Capacity Curtailments screener.
Evonik Industries (XTRA:EVK)
Evonik Industries plugs neatly into this screen because it is a large, integrated chemicals producer that spans basic intermediates and higher value additives, giving it scope to benefit if tighter UK capacity shifts volumes and pricing towards continental producers.
Evonik Industries runs a broad chemicals portfolio across Advanced Technologies, Custom Solutions and Infrastructure, generating about €6.0b, €5.5b and €3.0b in segment revenue respectively, and carries a market value of roughly €8.0b.
"Aggressive cost optimization and a shift to specialty chemicals are set to strengthen margins and align with rising demand for sustainable solutions."
What happens to Evonik’s margin story if one unseen pressure on its European cost base and pricing power moves in the wrong direction?
If that pressure point matters to your thesis, read the full narrative for Evonik Industries to see how Evonik Industries’ margin story could be decoupling from UK gas stress.

Wacker Chemie (XTRA:WCH)
Wacker Chemie slots cleanly into this UK and European capacity story because it is a diversified producer with plants across multiple regions. Any squeeze on UK output can shift more business toward its silicones, polymers, biosolutions and polysilicon franchises.
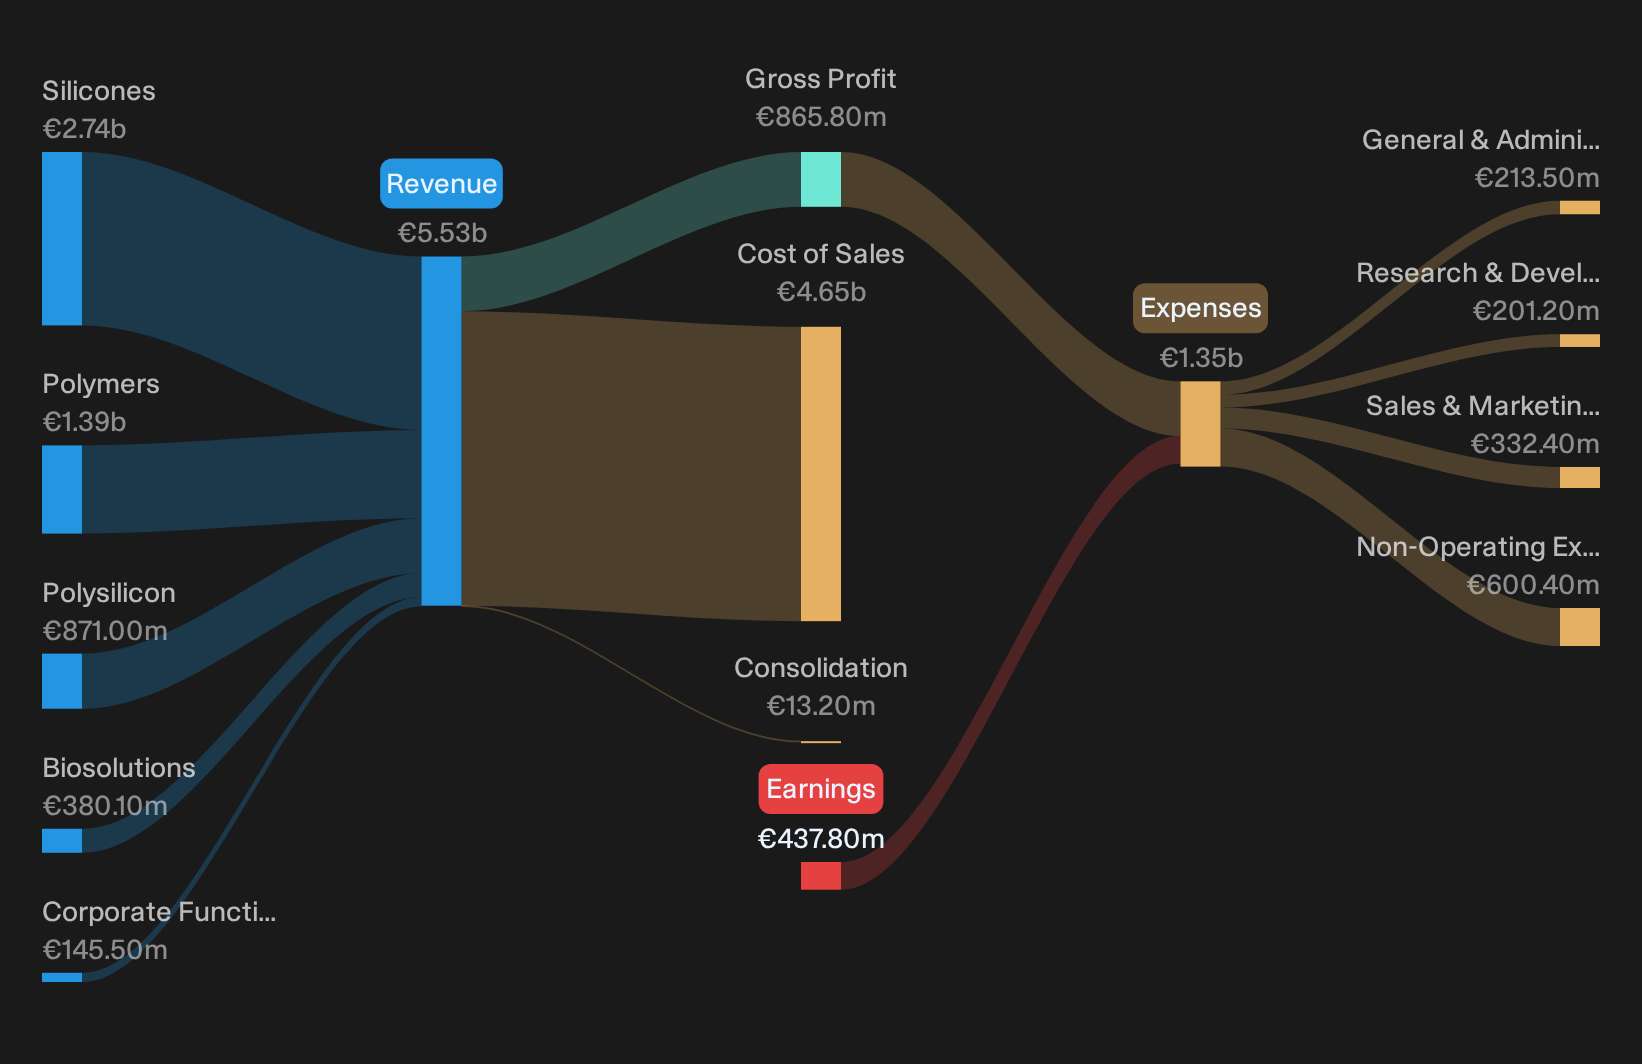
Wacker Chemie generates about €2.7b from Silicones, €1.4b from Polymers, €871 million from Polysilicon and €380 million from Biosolutions, plus smaller corporate items, and the stock carries a market value of roughly €4.3b.
Investors watching the Hull closures are really asking how a broad-based chemicals group like Wacker Chemie might turn tighter UK supply into better economics in higher value product lines.
"While analyst consensus expects specialty silicones to drive incremental margin gains through product mix and improved utilizations, a much more pronounced margin upside could materialize as Wacker's recent capacity investments are absorbed into booming end-markets for advanced batteries and e-mobility, enabling operating leverage that sharply lifts both top-line growth and EBITDA margin well ahead of expectations."
What happens to that margin story if one underappreciated pressure point on regional pricing and volumes shifts in Wacker Chemie’s favor?
If that shift is what you are betting on, read the full narrative for Wacker Chemie to see how Wacker Chemie’s capacity build and pricing power could be accelerating.
Arkema (ENXTPA:AKE)
Arkema plugs into this screen as a France headquartered specialty materials group with a broad European footprint and the flexibility to shift output across adhesives, advanced polymers and coatings when UK basic chemical capacity tightens.
Arkema generates about €3.4b from Advanced Materials, €2.7b from Adhesive Solutions and €2.2b from Coating Solutions, with smaller corporate and segment adjustments, and the stock has a market value of roughly €4.3b.
"Arkema has started up a 15% PVDF capacity expansion in Calvert City, Kentucky, an investment of around US$20 million that was delivered on time and within the initial budget, according to company disclosures."
What happens to Arkema’s earnings power if one underappreciated shift in regional capacity and pricing plays out differently than most investors expect?
If that shift in regional chemistry is what you are hunting, go straight to the full narrative for Arkema to see how Arkema’s earnings power could be accelerating.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. By the time momentum headlines hit, early entries are already flying. Use these under the radar for now screens while it matters and get in early.
- Hunt for resilient compounding potential by filtering for businesses in the 230 resilient stocks with low risk scores that aim to keep portfolio volatility from quietly creeping higher.
- Target growing cash engines by scanning the 170 high quality undervalued stocks while valuations still look reasonable and before a breakout rerates the quality that others have not yet priced in.
- Ride the AI infrastructure build out by reviewing the 86 AI infrastructure stocks before the crowd catches every headline and tightens the entry window.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com