
ATI (ATI) Has Investors Paying Closer Attention, But Why?
ATI (ATI) heads into Morgan Stanley's 14th Annual Laguna Conference with investors focused on aerospace and defense demand, record backlog, and margin progress, even as recent earnings estimates have edged slightly lower.
The share price tells a mixed but powerful story. ATI is trading at US$189.16 after slipping about 9% over the past month and 5% over 90 days, yet the year to date share price return of roughly 59% and a 1 year total shareholder return of about 137% point to strong momentum that has built over time as investors reassess the growth potential and risk profile around aerospace, defense and specialty energy demand, especially with the Morgan Stanley conference giving management another platform to reinforce that thesis.
Scan other aerospace and defense suppliers showing similar momentum and capacity build outs by reviewing the hand picked 40 power grid technology and infrastructure stocks aligned with ATI's end markets.
ATI now trades well below the average analyst target, even after a strong multi year run and recent pullback. Is the discount signaling opportunity, or a fair warning that the market’s caution is justified?
Most Popular Narrative: 5.6% Undervalued
ATI's most followed valuation storyline puts fair value at $200.33 versus the latest close of $189.16, a modest gap that keeps attention on how durable its aerospace, defense and energy demand really is.
Recent long-term contract expansions with both Boeing and Airbus, including new titanium alloy sheet supply and broader product offerings, lock in higher volumes and minimums, expand ATI's share, and feature inflation pass-through and attractive pricing. These elements directly support reliable, higher-margin revenue growth and a structurally improved earnings base through the decade.
See why 18 investors see ATI as 6% undervalued.
Result: Fair Value of $200.33 (UNDERVALUED)
Still, if aerospace customers pull back on orders or global trade barriers further weigh on ATI's non defense markets, the 5.6% undervaluation narrative could weaken.
Find out about the key risks to this ATI narrative.
Another View: ATI Looks Expensive On Earnings
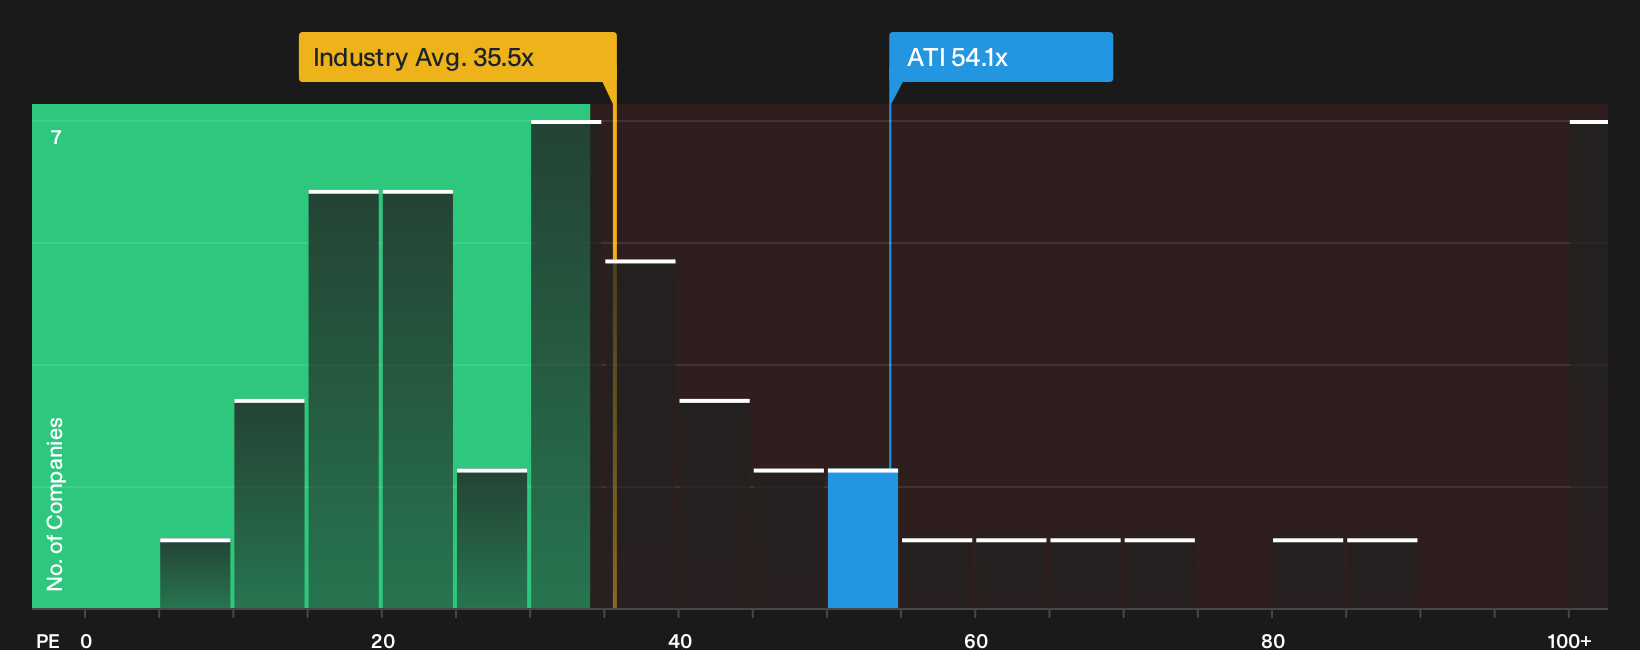
On the flip side of that 5.6% undervalued storyline, ATI trades on a P/E of 54.1x. That is richer than the US Aerospace & Defense industry at 35.5x and also above a fair ratio estimate of 32.1x, which points to valuation risk if sentiment cools.
ATI also screens as pricey versus its peer average P/E of 70.9x. This still leaves limited room if the market shifts closer to the 32.1x fair ratio instead. Is this a premium you are comfortable paying for the current growth and margin profile, or is it time to stress test your assumptions using other tools like cash flow and balance sheet strength?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on ATI's valuation and risk profile make this a judgment call rather than a consensus. Act while the data is fresh and weigh both sides of the story by reviewing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond ATI?
If ATI has you rethinking your watchlist, now is the moment to widen the field and pressure test your next moves with fresh, data backed ideas.
- Target resilient potential by scanning a 30 resilient stocks with low risk scores, which can help you focus on businesses with steadier profiles when conditions change.
- Hunt for mispriced quality using the 17 high quality undiscovered gems and see which under followed stocks match the kind of fundamentals you want on your side.
- Strengthen your core holdings with a list of solid balance sheet and fundamentals (23 results) before the next bout of volatility highlights which companies had financial room to move.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com