
BYD (SEHK:1211) Stock May Be Overvalued Despite Fresh US Market Access Pressure
BYD has had a tough year on the market, and the slide in the share price raises a simple question for investors who care about fundamentals. Is the current valuation still in step with what the company is earning today?
- The stock is down 23.1% over the past year, which puts a sharper focus on whether the recent share price now lines up with the business’s earnings power.
- Recent headlines around access to the US and other overseas markets may influence how investors think about the durability and timing of BYD’s profit stream.
- The analysts covering BYD have run their own numbers. See what analysts think BYD's shares could be worth.
The issue now is whether BYD’s current share price is adequately supported by its earnings when judged against the Fair Ratio benchmark.
If you are questioning whether BYD’s recent share price slide still lines up with its earnings, it can help to compare that same Fair Ratio lens across 170 high quality undervalued stocks.
Does BYD Look Pricey on Earnings?
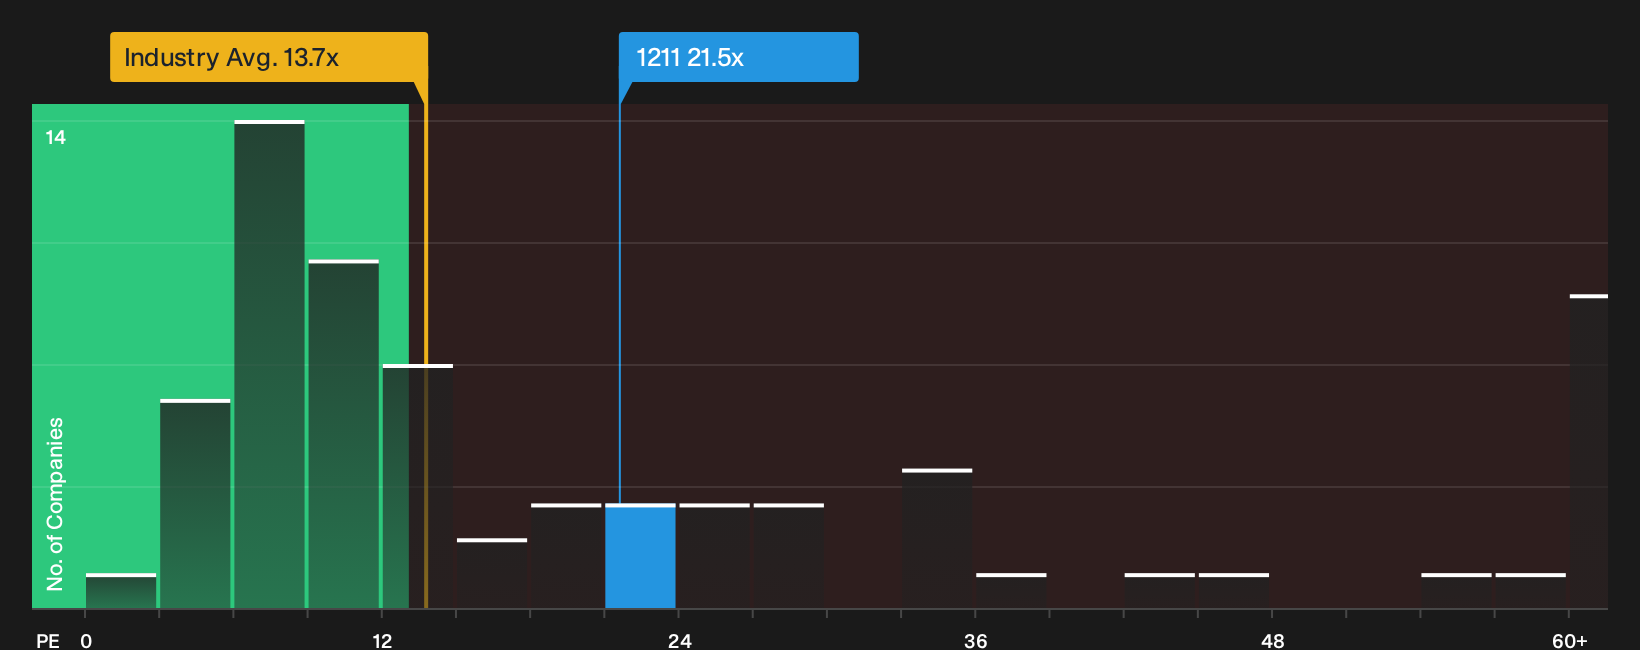
The P/E ratio is a useful lens for BYD because earnings remain a key reference point for how investors frame the business today. On that score, the stock trades on about 21.5x earnings, very close to the peer group average of roughly 21.4x. That level is above the wider Auto sector, where the typical P/E is nearer 13.7x, so the market is attaching a richer tag to BYD than to the sector overall.
Despite recent headlines about potential limits on Chinese EVs in the US, the valuation still reflects a premium story rather than a bargain one. On Simply Wall St’s Fair Ratio framework, which adjusts the P/E you might expect for BYD’s size, margins, industry and risk profile, the current multiple screens as overvalued. For anyone weighing the recent share price slide against that premium earnings tag, it is worth considering how big a gap the model is flagging before deciding whether the current level looks interesting or not. Explore the numbers behind BYD's P/E valuation.
The BYD Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the BYD valuation puzzle leaves off. They explain what would need to happen to BYD's future growth, margins and earnings for the share price to look meaningfully higher or lower than today. Each narrative anchors a fair value on a specific mix of potential catalysts and risks, so you can track over time which version of events appears to be unfolding on the Community page.
One of the top community narratives on BYD: 47% undervalued
"For years, the market viewed BYD as the "budget" alternative to Tesla, a battery company that happened to make cars..."
Discover why this Narrative puts BYD at 47% undervalued.
BYD’s valuation still leaves one big piece of the puzzle unresolved
The market price tells you what investors pay for BYD today, but analyst projections sketch where they think the business could be a few years from now. This gives you a different anchor to compare with the current multiple. Explore where analysts expect BYD to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com