
Toronto-Dominion Bank (TSX:TD) Just Gave Investors Something To Think About
Why TD’s record quarter matters for shareholders
Toronto-Dominion Bank (TSX:TD) just posted record third quarter earnings of CA$4.7b, with earnings per share of CA$2.77 and an 8% jump in revenue, putting fresh attention on the stock.
Management also reported a 16% return on equity, plans to add 100 new U.S. branches by 2028, and an intention to return more than CA$13b to shareholders by fiscal 2027 through buybacks.
The latest quarterly update lands after a strong run in the shares. A CA$174.10 price and a year to date share price return of 34.11% have contributed to a 1 year total shareholder return of 64.11% and a 5 year total shareholder return of 154.73%. This suggests momentum has been building as Toronto-Dominion Bank pairs record profits with ongoing capital market activity and fresh bond issuance.
Scan other banks showing similar momentum to Toronto-Dominion Bank by reviewing our hand picked 6 high quality undervalued stocks that combine earnings power with balance sheet strength.
Toronto-Dominion Bank shares have raced ahead to fresh records and a packed capital plan, so the real tension now is whether you pay up today or sit tight and hope for a cheaper entry before the next move.
Most Popular Narrative: 3% Undervalued
Against a last close of CA$174.10, the most followed narrative pegs Toronto-Dominion Bank’s fair value at CA$179.14, implying a modest discount and placing more weight on long term cash generation than on recent share price strength.
Strong revenue growth, digital innovation, strategic restructuring, and diversified operations position TD for sustained profitability and shareholder returns in evolving financial markets.
See why 177 investors see Toronto-Dominion Bank as 3% undervalued.
Result: Fair Value of CA$179.14 (UNDERVALUED)
Still, this Toronto-Dominion Bank narrative could be knocked off course if regulatory costs stay elevated or if Canadian real estate credit losses run higher than analysts expect.
Find out about the key risks to this Toronto-Dominion Bank narrative.
Another view on Toronto-Dominion Bank’s valuation
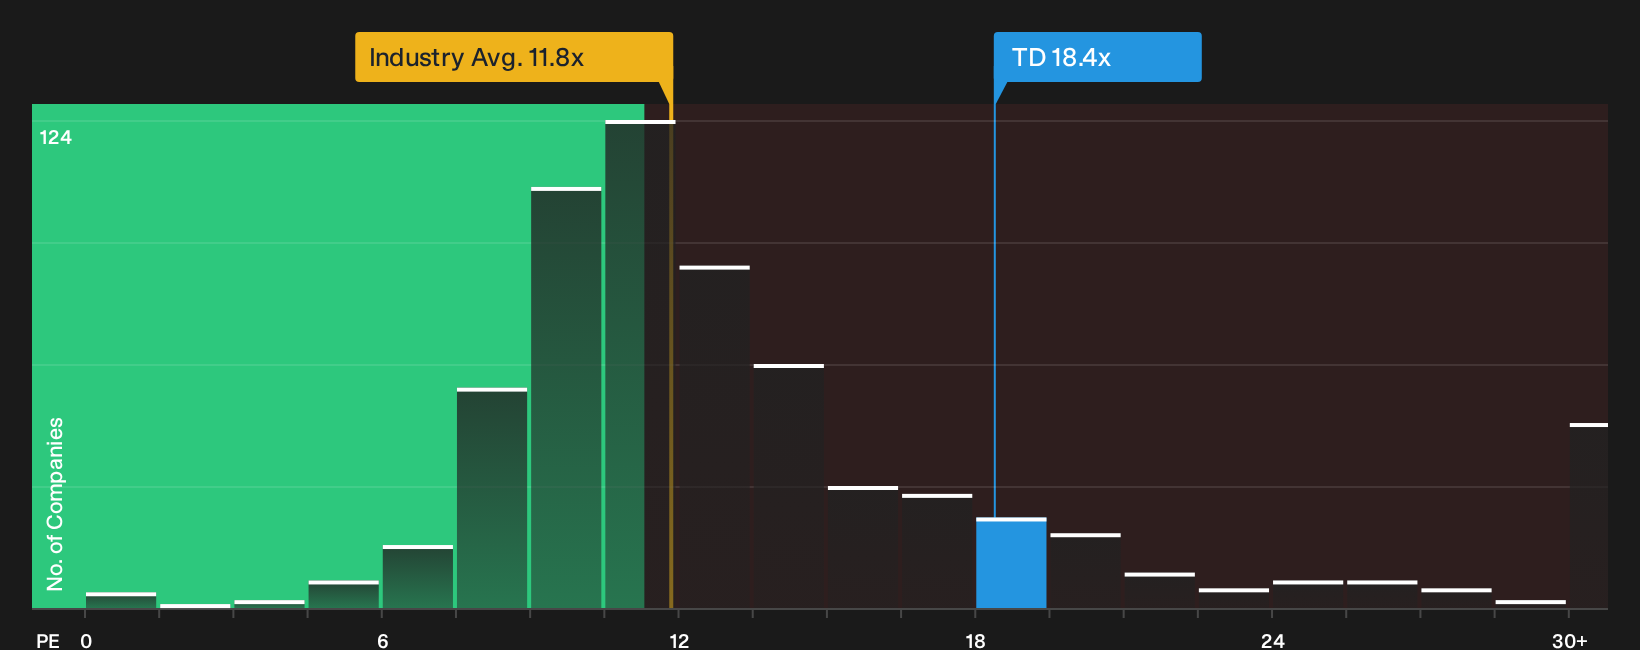
The narrative summary points to Toronto-Dominion Bank trading below an estimated fair value of CA$179.14, yet the market is not treating the shares as outright cheap on earnings. At a P/E of 18.4x, TD trades above the peer average of 17.6x and well above the wider North American banks group on 11.8x. The fair ratio suggests 16.6x may be a level the market could drift toward. If sentiment cools, would investors focus more on the discount to fair value or the richer earnings multiple?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Toronto-Dominion Bank is clearly positive, but the real edge comes from working through the numbers yourself and pressure testing the story. To see what is driving that optimism around potential upside, take a closer look at the 3 key rewards.
Looking for more investment ideas beyond Toronto-Dominion Bank?
If you only stop at Toronto-Dominion Bank, you risk missing other opportunities where price, balance sheet quality, and income potential line up in your favour.
- Target resilient candidates that prioritise stability and capital protection through our 8 resilient stocks with low risk scores.
- Hunt for quality at a reasonable price by reviewing the 6 high quality undervalued stocks that match your return and risk preferences.
- Strengthen your portfolio’s foundation by scanning the list of solid balance sheet and fundamentals (7 results) for businesses built on sturdier financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com