
Discover 3 ASX Penny Stocks With Market Caps Under A$2B
The Australian share market is poised for a stronger start, with ASX 200 futures indicating a potential gain following a global rally that saw significant advances in technology and growth stocks. Amidst these broader market movements, investors are considering the impact of fluctuating oil prices and interest rate expectations on their portfolios. Although the term "penny stock" might seem outdated, it still highlights opportunities in smaller or newer companies that can offer affordability and growth potential when backed by strong financials.
Let's review some notable picks from our screened stocks.
Duratec (ASX:DUR)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: Duratec Limited, with a market cap of A$565.37 million, provides assessment, protection, remediation, and refurbishment services for steel and concrete infrastructure assets in Australia.
Operations: Duratec's revenue is primarily derived from its key segments, including Defence (A$157.75 million), Buildings & Facades (A$138.84 million), Mining & Industrial (A$114.34 million), and Energy (A$91.56 million).
Market Cap: A$565.37M
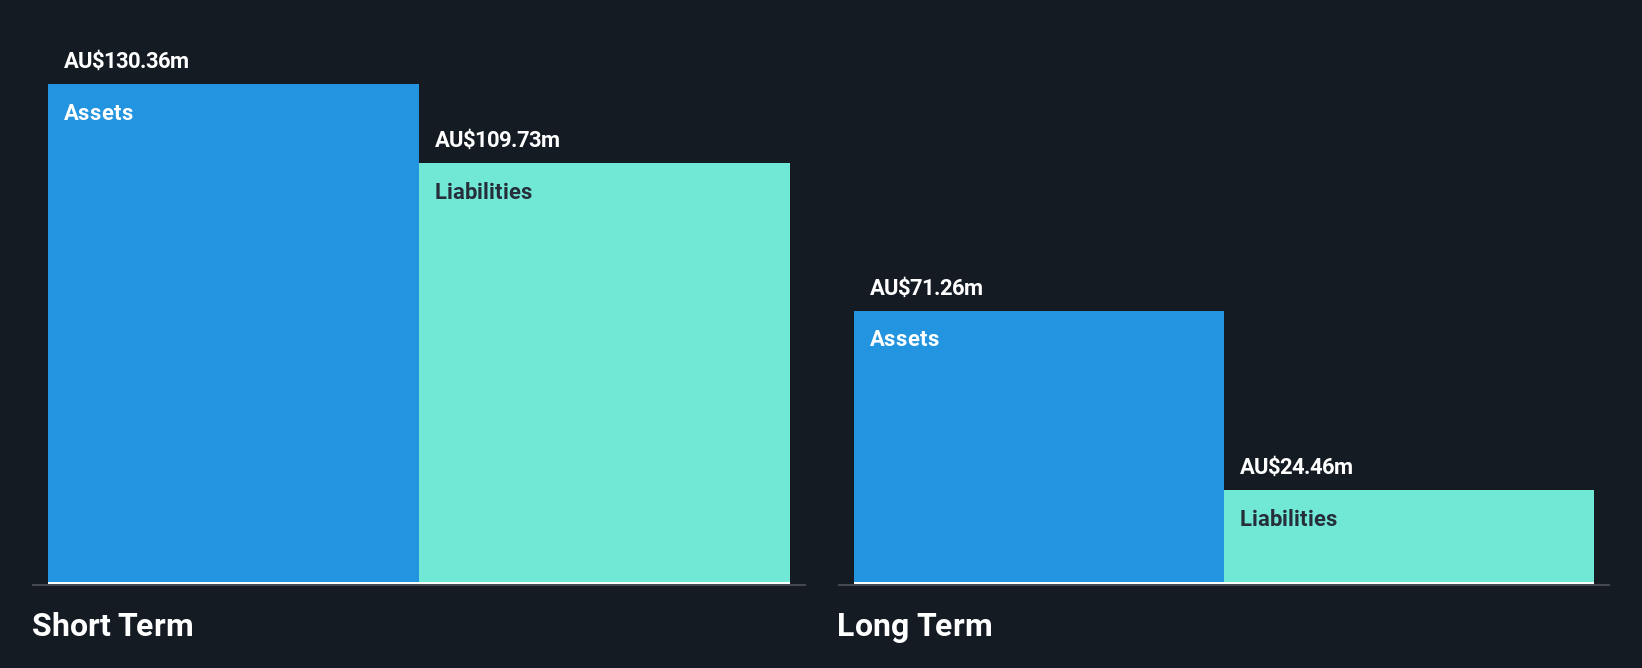
Duratec Limited, with a market cap of A$565.37 million, has demonstrated solid financial health and strategic growth initiatives. Despite earnings growth of 4.1% over the past year lagging behind its five-year average of 24.3%, the company maintains a robust balance sheet with short-term assets exceeding liabilities and more cash than total debt. Recent announcements highlight an acquisition strategy aimed at enhancing capabilities while maintaining cultural alignment and strategic fit, supported by a cash balance of A$78.8 million and strong funding capacity for organic expansion and acquisitions. The board's seasoned experience further bolsters confidence in navigating future opportunities effectively.
- Dive into the specifics of Duratec here with our thorough balance sheet health report.
- Examine Duratec's earnings growth report to understand how analysts expect it to perform.
Generation Development Group (ASX:GDG)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: Generation Development Group Limited operates in the diversified financial services sector in Australia, with a market capitalization of A$1.20 billion.
Operations: The company's revenue is primarily derived from Benefit Funds at A$436.98 million, followed by Managed Accounts Business (Evidentia) at A$63.16 million, Benefit Funds Management & Funds Administration (Generation Life) at A$64.41 million, Research and Ratings (Lonsec) at A$46.14 million, and Group Services (Corporate) contributing A$20.54 million.
Market Cap: A$1.2B
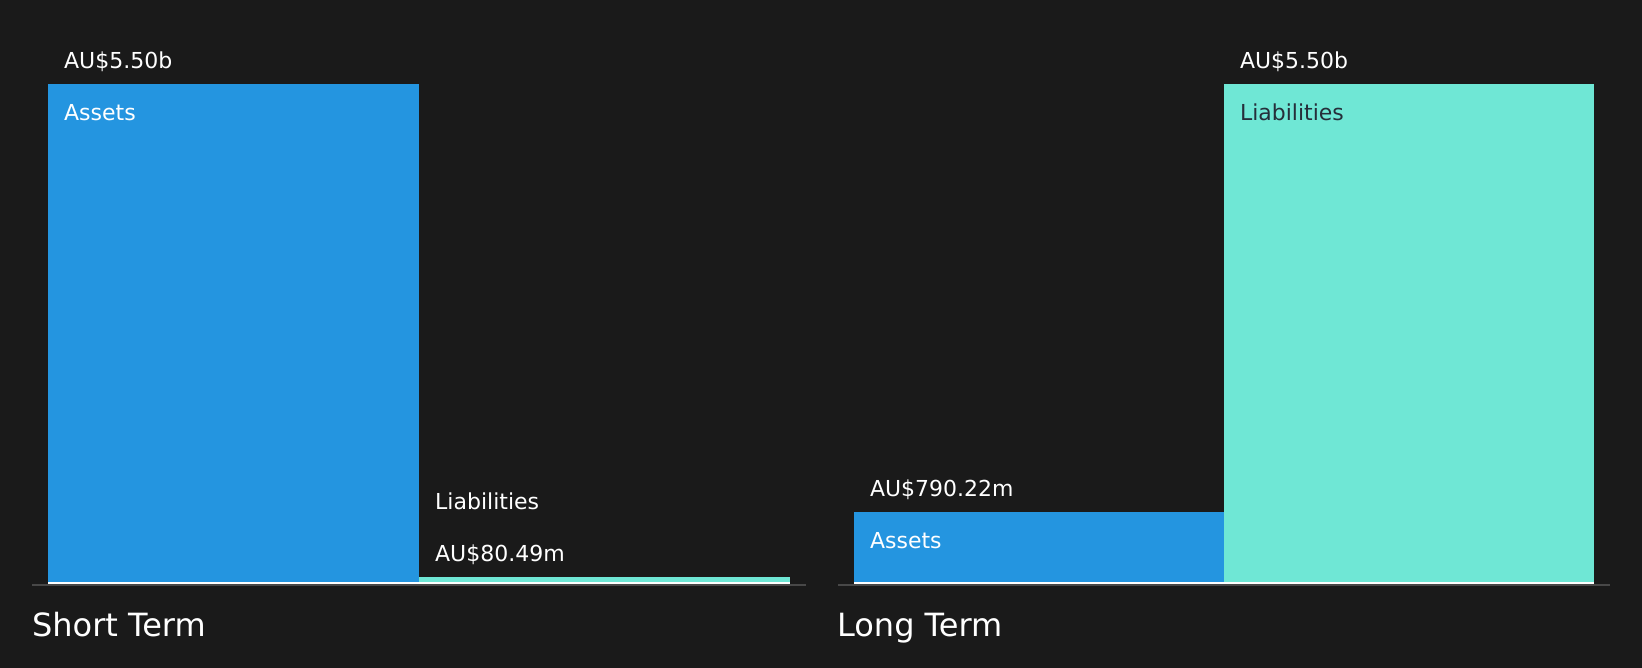
Generation Development Group, with a market cap of A$1.20 billion, operates in the diversified financial services sector and shows both strengths and challenges typical of penny stocks. The company's short-term assets (A$6.4 billion) comfortably cover both its short-term (A$114.9 million) and long-term liabilities (A$6.3 billion), indicating strong liquidity. Despite a low return on equity at 4.4%, earnings are forecast to grow by 21.22% annually, although recent negative earnings growth (-10%) presents concerns about immediate profitability trends. Management's limited experience is offset by an experienced board, while high-quality past earnings provide some confidence in operational stability moving forward.
- Click to explore a detailed breakdown of our findings in Generation Development Group's financial health report.
- Evaluate Generation Development Group's prospects by accessing our earnings growth report.
Silex Systems (ASX:SLX)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: Silex Systems Limited is a technology commercialization company focused on the research, development, and licensing of SILEX laser enrichment technology across Australia, the United States, and the United Kingdom, with a market cap of A$1.30 billion.
Operations: The company's revenue segments consist of A$13.28 million from Silex Systems and A$2.09 million from Translucent.
Market Cap: A$1.3B
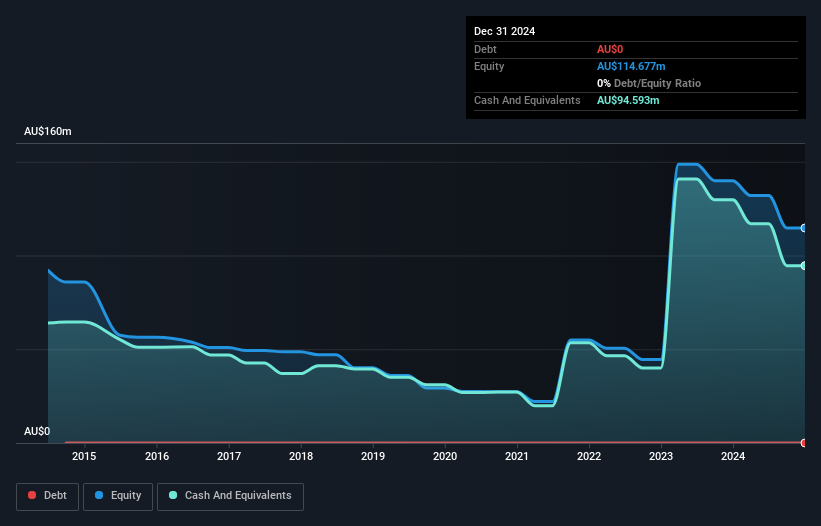
Silex Systems, with a market cap of A$1.30 billion, is currently unprofitable but demonstrates potential typical of penny stocks through its technology commercialization efforts. The company reported sales of A$13.71 million for the year ended June 2026, an increase from A$7.27 million the previous year, though net losses remain significant at A$38.62 million. Despite these losses, Silex maintains strong financial health with no debt and sufficient short-term assets (A$190.2M) to cover liabilities and sustain operations for over three years due to positive free cash flow growth and stable shareholder equity without dilution concerns.
- Navigate through the intricacies of Silex Systems with our comprehensive balance sheet health report here.
- Understand Silex Systems' earnings outlook by examining our growth report.
Summing It All Up
- Discover the full array of 396 ASX Penny Stocks right here.
- Ready To Venture Into Other Investment Styles? The best AI stocks today may lie beyond giants like Nvidia and Microsoft. Find the next big opportunity with these 19 smaller AI-focused companies with strong growth potential through early-stage innovation in machine learning, automation, and data intelligence that could fund your retirement.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com