
Is CNX Resources (CNX) Still Undervalued After Its Transparency Push?
CNX Resources has delivered a 5 year return that would have tested the patience and rewarded the discipline of long term holders, yet the recent pullback leaves a fresh question on the table about what its current price really asks you to pay for its earnings. With the stock down in the short term and fresh headlines around its environmental disclosure efforts, the key issue now is how all of that lines up against the profit engine that ultimately has to justify the valuation.
- Over the past 5 years the share price has gained 153.5%, which puts real weight on whether the underlying earnings can carry that kind of step up in investor expectations.
- CNX has expanded its public transparency program to include continuous radiation monitoring at certain sites, which can influence future cost structures, regulatory risk and how investors think about the durability of its cash generation from gas production and related operations.
- Your read on CNX Resources is one view; the desks covering it have another. See what analysts think CNX Resources's shares could be worth.
The stock's next move may depend on whether CNX Resources' current share price is still in line with what its earnings suggest it should be.
If you want to test the same earnings question you are asking of CNX Resources across a wider field, compare it with companies in the 30 high quality undervalued stocks
Is CNX Resources Still Cheap on Earnings?
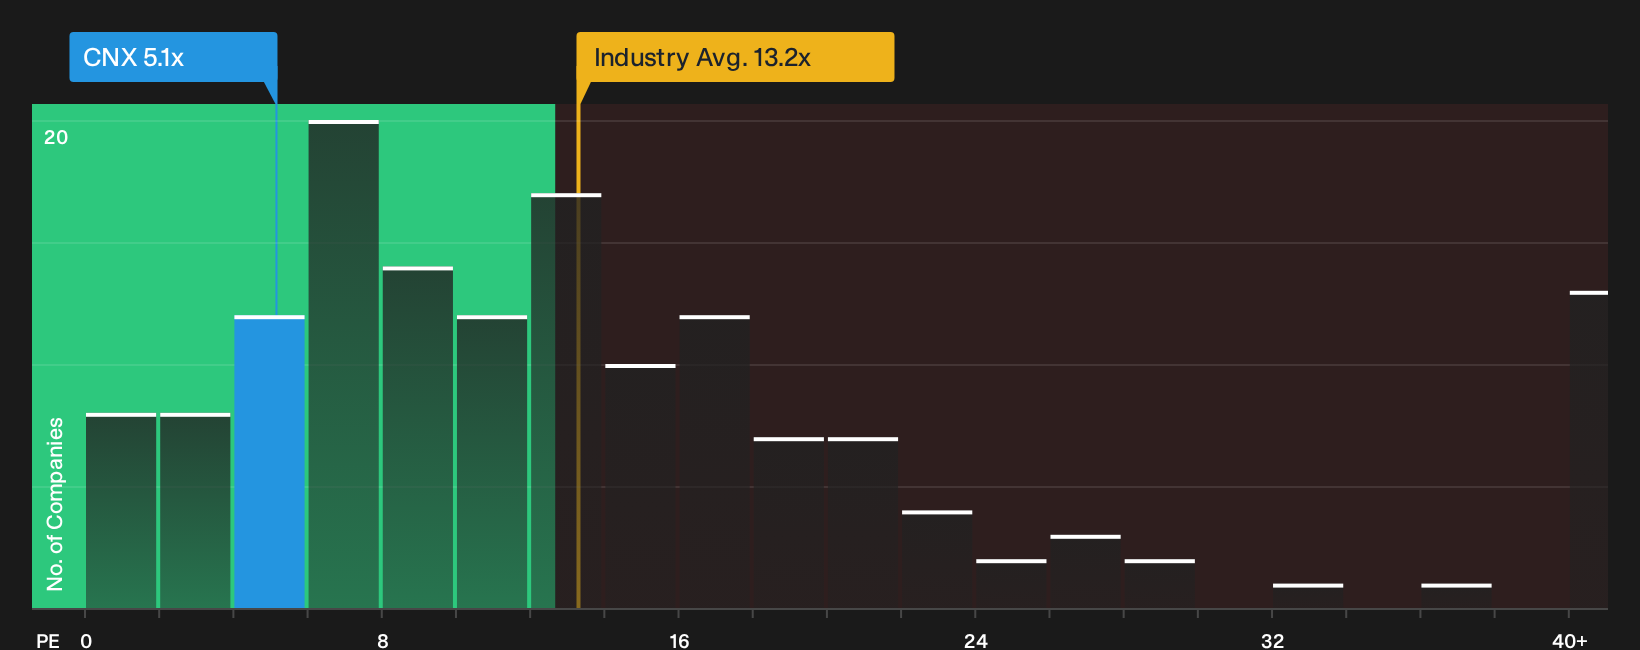
The P/E ratio fits CNX Resources because earnings are the key driver most investors watch for a gas focused producer. On that measure, the stock changes hands at about 5.1x its trailing earnings, which is far below the Oil and Gas sector average of roughly 13.2x and also well under the peer group around 29.7x. The gap suggests investors are paying a much lower price for each dollar of CNX Resources earnings than for typical competitors.
Because of that, and because the fair multiple that blends CNX Resources growth profile, profitability, size and risk points to a higher P/E than the current figure, the shares screen as undervalued on this framework. The recent move to expand radiation monitoring and disclosure has raised attention around environmental risk. Yet despite that extra scrutiny, the market is still pricing the stock at a clear discount to those benchmarks. Explore the numbers behind CNX Resources's P/E valuation.
The CNX Resources Narrative: What Would Justify Today's Price?
Narratives on CNX Resources pick up where the P/E puzzle leaves off and map out the future growth, margin and earnings paths that would need to play out for the stock to be worth significantly more or meaningfully less than it is today on Simply Wall St's Community page. Instead of one static output from a ratio or model, these storylines describe the operating future that figure relies on so you can judge over time whether real world results continue to align with that script.
Community views on CNX Resources split between those who see more upside embedded in the long game and those who treat it as closer to fully priced.
Bull case: 13% undervalued
"Expansion into differentiated products (RNG, blue hydrogen, carbon-linked derivatives) and flexible participation in voluntary and compliance environmental markets position CNX to capture diversified, premium-priced revenue streams…"
Discover why this Narrative puts CNX Resources at 13% undervalued.
Bear case: roughly fairly valued
"The numbers and current valuation for CNX Resources suggest a fairly valued but bearish setup in which the share price already reflects meaningful benefits from hedging, low-carbon monetization, and disciplined capital returns, leaving limited margin for error…"
Explore why this Narrative puts CNX Resources at roughly fairly valued.
Before you move on CNX Resources still has one more angle to check
Valuation tells only part of the story for CNX Resources, since Simply Wall St's broader review has also flagged specific risk checks that deserve your attention before you lean on any numbers alone. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com