
3 U.S. Energy Stocks With Cash Flow Leverage to High Oil Prices
Markets are being squeezed by higher-for-longer interest rates, stubborn inflation and crude holding above US$100, so the usual playbook for U.S. energy producers and refiners suddenly looks less straightforward. That tension between expensive money and expensive oil creates both openings and tripwires for investors who move early. This article explains how that backdrop affects the sector and highlights 3 stocks exposed to this shift in conditions.
The three stocks below are just a starting sample, and the full screen surfaced 23 more U.S. energy producers and refiners with equally compelling investment stories that are not covered here.
To go wider and identify ideas that better match your own risk, income and quality filters, head straight to the U.S. Energy Producers and Refiners screener to analyze and prioritize the opportunities that best align with your highest conviction.
Northern Oil and Gas (NOG)
Overview: Northern Oil and Gas is a U.S. focused independent producer that acquires and develops crude oil and natural gas assets, giving investors direct exposure to upstream commodity prices within the U.S. Energy Producers and Refiners theme.
Operations: Northern Oil and Gas generates about US$2.0b of revenue from oil and gas exploration and production in the United States.
Market Cap: US$2.7b
Northern Oil and Gas matters for this screener because it lives at the production layer of the energy chain, where realized crude and gas prices directly shape cash generation and sensitivity to higher-for-longer interest rates.
"The company's disciplined shift toward acquisitions of long-dated, stable production assets amid a volatile commodity environment positions NOG to benefit from continued global energy demand and the ongoing importance of energy security. This supports more resilient long-term revenue and less volatile cash flows.
What happens to that balance between stability and growth depends heavily on how one unseen pressure plays out across its financing costs.
That financing pressure is the crux of the story, and the full narrative for Northern Oil and Gas shows how that risk could be masking an overlooked cash flow engine.
Helmerich & Payne (HP)
Overview: Helmerich & Payne provides onshore and offshore drilling rigs and digital drilling technologies to oil and gas producers, giving indirect leverage to higher crude prices.
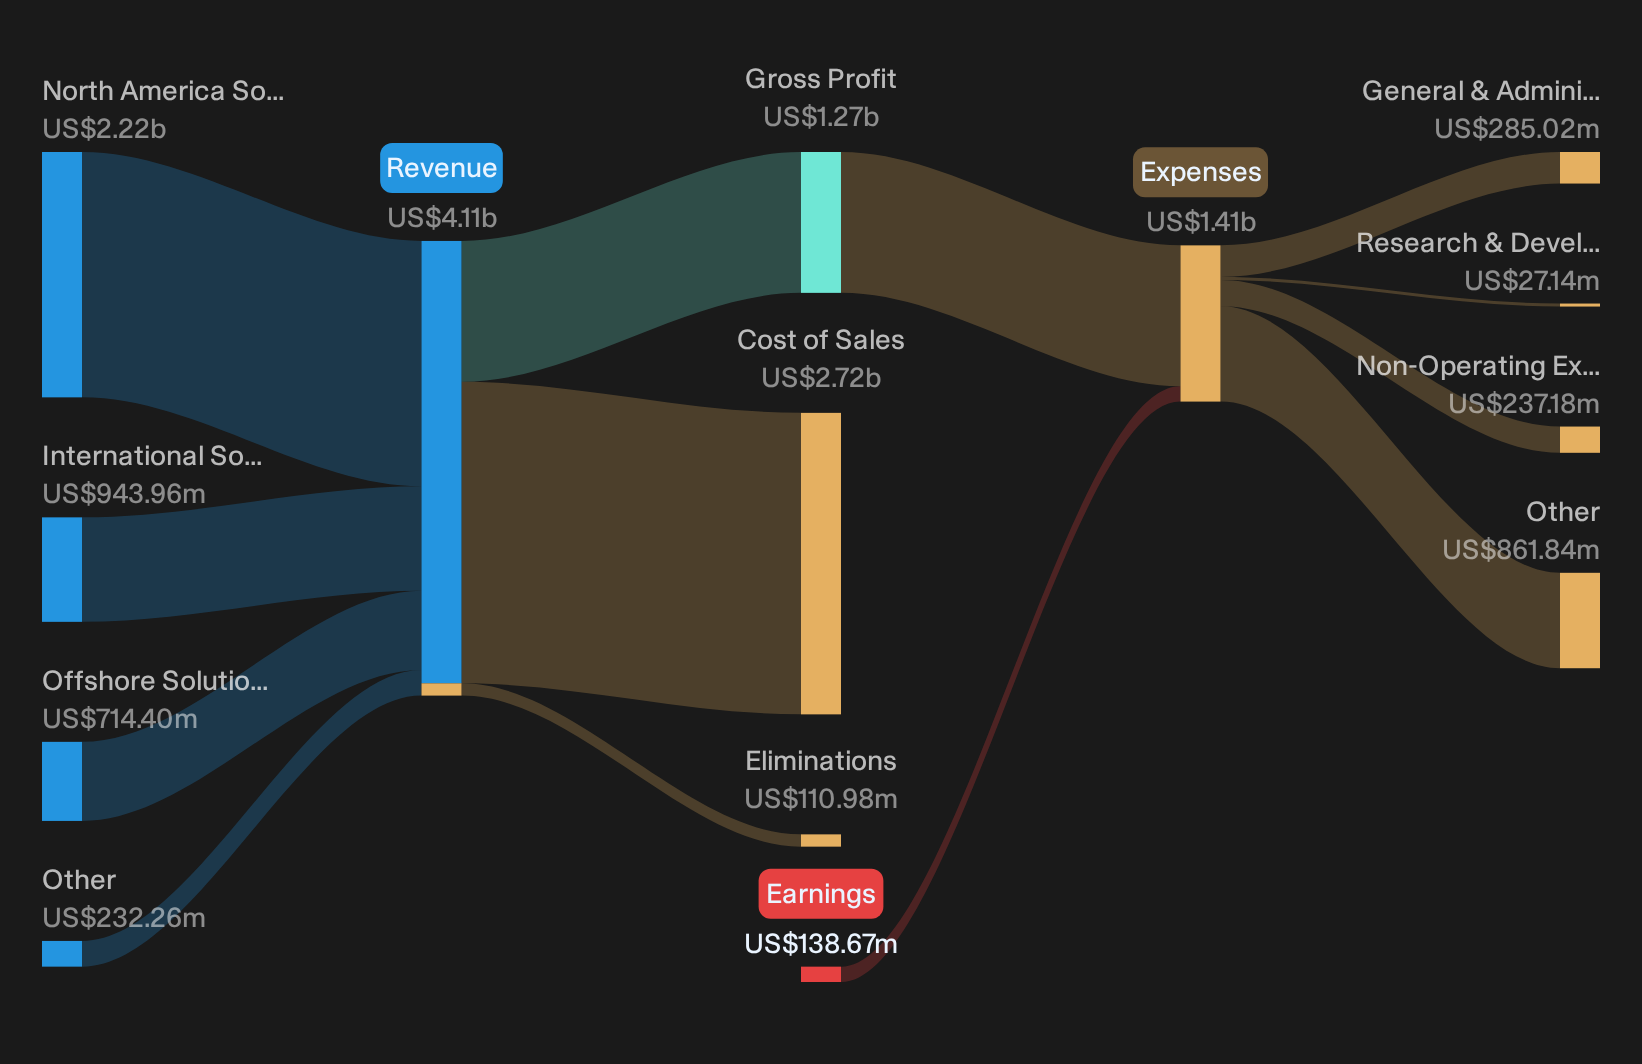
Operations: Helmerich & Payne generates about US$2.2b from North America Solutions, US$944 million from International Solutions and US$714 million from Offshore Solutions, with smaller contributions from other activities and eliminations.
Market Cap: US$4.1b
Helmerich & Payne matters for this screener because it sits one step behind the producers, with rig demand and pricing closely linked to E&P capital spending when oil stays expensive.
"Continued digitalization and automation of drilling operations, evidenced by a 20% year-over-year increase in app adoption and performance-based contracts, is driving stronger customer value creation and differentiated pricing. This supports higher revenue and margin expansion going forward."
What happens to that margin story hinges on how a single shift in customer drilling budgets ripples through rig utilization and pricing power.
When that spending shift hits, the full narrative for Helmerich & Payne shows how Helmerich & Payne’s pricing power, utilization and drilling tech momentum could be accelerating under the surface.
RPC (RES)
Overview: RPC provides oilfield services and rental equipment that support exploration, production and well maintenance for energy producers worldwide.
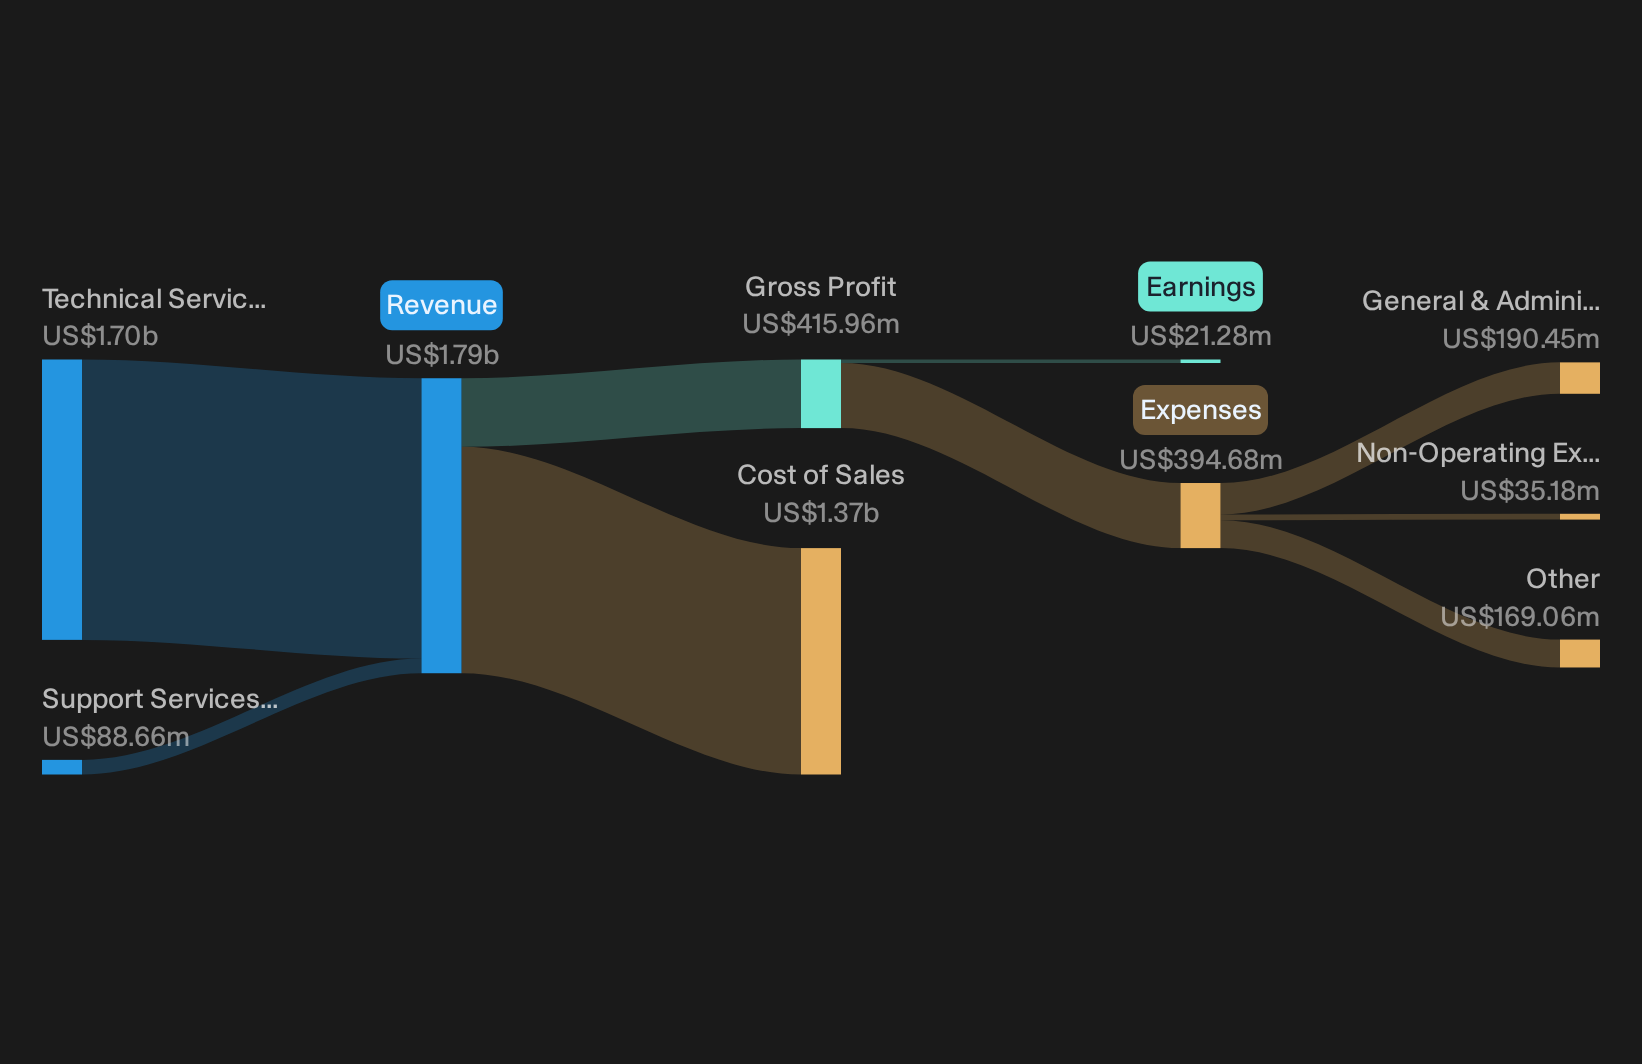
Operations: RPC generates about US$1.7b from Technical Services and US$89 million from Support Services, mostly from US$1.8b in United States revenue.
Market Cap: US$1.3b
RPC plugs directly into the U.S. Energy Producers and Refiners theme by supplying the completion, pumping and rental services producers rely on when field activity remains busy.
"Early adoption of advanced, low-emission technologies enables premium pricing and higher margins, positioning RPC ahead of industry modernization trends."
The extent of that margin potential depends heavily on how one unresolved constraint shapes pricing power across its most equipment-intensive lines.
That single constraint is the hinge, and the full narrative for RPC shows whether RPC’s low emission push is quietly accelerating returns or masking fresh pressure on capital.
Seeking Alternatives Before Momentum Flies
Fresh ideas move first, and by the time the crowd notices, the cleaner entry point can be gone. Scan these themed shortlists while the data still matters, then act now.
- Hunt for smaller companies with real balance sheet strength using the curated list of solid balance sheet and fundamentals (23 results) that keeps weak financial structures out of your watchlist.
- Track fast-moving opportunities that already produce cash with the focused 38 profitable AI stocks that aren't just burning cash before momentum is fully reflected in broader AI headlines.
- Target resilient income ideas that aim to keep distributions flying using a hand picked 7 dividend fortresses built for investors who do not want payouts dropping unexpectedly.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com